US Foreign Tax Credits for Singapore Residents
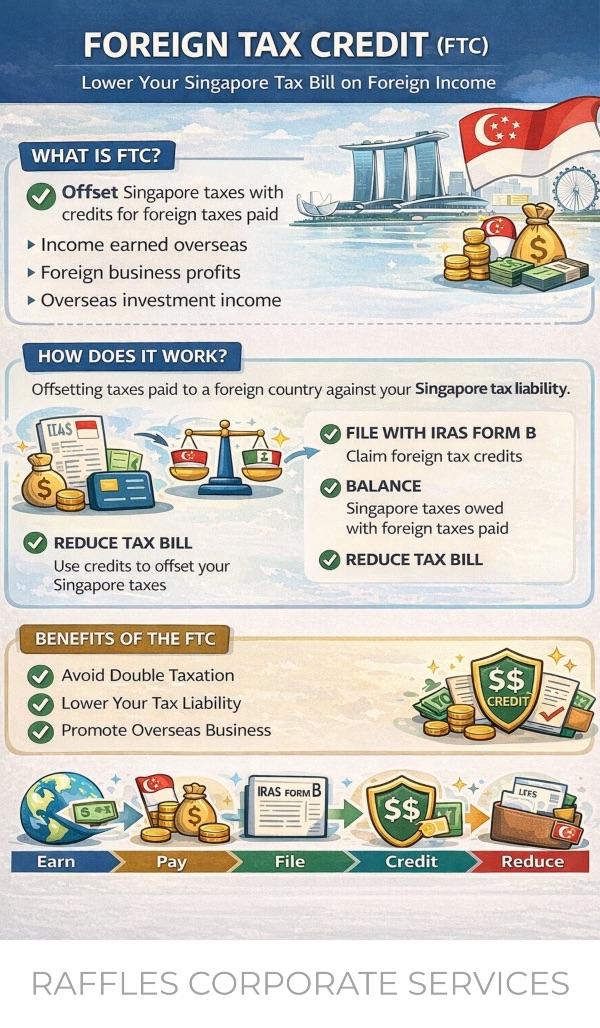
Most people living in Singapore think they can ignore US tax obligations because Singapore has no personal income tax. That assumption is wrong if you have US-sourced income, investments in US entities, or any connection to US tax law. The Foreign Tax Credit is one mechanism that prevents double taxation, but it works differently than most people expect. I spent several years handling US tax filings for Singapore-based individuals and companies before I understood exactly where the system breaks down.The basic structure is straightforward. When you earn income sourced from the United States, the IRS may withhold taxes at source. Singapore does not tax that same income because it operates on a territorial-like system for most individuals. Without relief, you would pay US tax and then nothing in Singapore. With the Foreign Tax Credit, you file Form 1116 with your US tax return and claim a credit for foreign taxes paid. The credit offsets your US tax liability dollar for dollar, up to a limit. The limit is the lower of your actual US tax liability or your foreign-source income divided by your total income, multiplied by your total US tax. This is the "overall limitation" under Section 904 of the Internal Revenue Code. Here is the part nobody mentions clearly. The FTC limitation is calculated separately for different categories of income. Passive income sits in one basket. General income sits in another. If you have US-sourced dividends in the passive basket and foreign-sourced interest in the general basket, you cannot cross-utilize excess credits from one category to offset tax in the other. I learned this the hard way in 2021. I had a client with significant Canadian withholding tax on interest income and US dividend withholding tax. Their total US tax liability was minimal because most of their income was from non-US sources. I filed Form 1116 using all available foreign credits against the US tax. The return was accepted initially, but six months later I received an IRS notice disallowing the excess passive credits that could not offset general income tax. The fix required amending the return with separate Form 1116s for each basket. It added roughly three hours of work and delayed their refund by four months. The lesson was simple and expensive: calculate each basket separately before filing. A common mistake people make is assuming that higher US withholding is always better for the credit. That is not true when your US-source income is low relative to your worldwide income. The limitation formula means you can only credit foreign taxes up to the proportional share of your US tax. If your US-sourced dividends generate $3,000 in withholding but your overall limitation allows only $1,200 in credits, the remaining $1,800 is wasted. It does not carry forward. This is why understanding your income composition matters before you claim anything.
Another issue that comes up constantly involves Singapore residents who receive US dividends through Singapore-domiciled funds. The dividends retain their US source character regardless of where the fund is headquartered. You still need to file Form 1116 to claim the credit, and the withholding certificate must come from the US payer or the withholding agent, not from the fund company in Singapore. I worked with a person who tried to use a Singapore fund statement as proof of foreign taxes paid. The IRS rejected it. They had to contact the US broker to obtain an official withholding statement. That process took eight weeks. There is also a nuance around treaty benefits. The US has an income tax treaty with Singapore, but the treaty primarily affects withholding rates on dividends, interest, and royalties. It does not change the FTC limitation calculation. Some taxpayers assume that a reduced treaty withholding rate eliminates their need to file Form 1116. That is incorrect. If you have US tax liability and paid foreign taxes, you must file the form even if the withholding rate was reduced to 15 percent under the treaty. Skipping the form means you forfeit the credit entirely and pay full US tax on that income. The Process 1116 actually requires you to convert foreign taxes paid into US dollars using the applicable exchange rate. The IRS accepts the average annual rate or the spot rate on the date the tax was paid. I recommend using the IRS published average annual rates because they reduce audit risk. Converting with a random rate from a currency app created a discrepancy once that triggered a second notice. The difference was only forty dollars, but the correspondence added unnecessary time.
If you hold US stocks directly and receive dividends, the broker should provide a Form 1042-S or a withholding statement showing the gross dividends and taxes withheld. Use those documents to complete Form 1116. If you hold mutual funds or ETFs, the withholding may already be factored into the fund's distributions, and you may not receive a separate withholding certificate. In those cases, you must reconstruct the foreign taxes from your account statements. I keep a spreadsheet that tracks withholding by year, fund, and currency. It saves about twenty minutes per filing and prevents the kind of errors that cause IRS correspondence. For Singapore residents with US business income or self-employment income, the calculation becomes more complex. Foreign taxes on business income fall into the general income basket rather than the passive basket. The distinction matters because the passive basket limitation is usually tighter for individuals with mostly passive income streams. Misclassifying business income as passive income can reduce your allowable credit by a significant amount. I had a consultant who reported his US consulting income as passive because he did not actively manage the work. The IRS reclassified it as general income during an examination, and his FTC limitation increased. He ended up owing additional tax plus penalties. Proper classification requires understanding whether the income meets the active trade or business test under Section 954. There is a scenario where the FTC does not help at all. If your total US tax liability is zero because your US-source income falls below the filing threshold or is offset by deductions, there is no credit to claim. Form 1116 requires a nonzero US tax liability to produce a usable credit. I once advised a client who had $800 in US dividend withholding and no other US income. Their US tax liability after the standard deduction was zero. Filing Form 1116 would have produced no benefit. We left the withholding as a final tax and did not file the form. It was the correct decision, but only because we calculated the limitation first.
Get the Full Details

Another thing to consider is the foreign earned income exclusion under Section 911. Some Singapore residents qualify for this exclusion if they meet the physical presence test or the bona fide residence test. The exclusion allows you to omit up to approximately $126,500 of foreign-earned income from US taxable income. However, you cannot claim both the exclusion and the FTC on the same income. Choosing the exclusion reduces your US tax liability, which in turn reduces your FTC limitation. In many cases, the FTC provides a larger benefit than the exclusion for high-income taxpayers with significant foreign taxes paid. The opposite is also true. I analyze both scenarios every year for my clients and use whichever produces the lower US tax. The difference can range from nothing to several thousand dollars depending on the income mix. Record keeping is the part that gets ignored until it causes a problem. The IRS requires you to maintain documentation of foreign taxes paid for at least three years from the filing date, or longer if a claim for credit or refund is pending. Keep withholding certificates, bank statements, fund distribution records, and any correspondence with brokers or tax authorities. I store everything in a dedicated folder organized by tax year and income type. The system takes about ten minutes to set up and prevents the chaos that comes from searching for a document during an audit. One edge case that deserves attention involves dual-status aliens. If you become a US resident partway through the year while maintaining Singapore residency, your filing status and FTC calculation change. You may need to file a dual-status return with a Form 1040 for the resident period and a Form 1040-NR for the nonresident period. The FTC limitation applies differently to each part. I handle these returns manually because automated tax software does not support the required segmentation. The additional time is roughly two hours per return, but it avoids the mistakes that come from forcing a dual-status situation into a standard return.
Finally, there is the question of whether to claim the credit or deduct foreign taxes. You can choose between a credit and a deduction on Schedule A if you itemize. The credit is almost always more beneficial because it reduces your tax liability dollar for dollar, while a deduction only reduces your taxable income. The deduction makes sense only in rare cases where your foreign taxes exceed the limitation and you expect the excess to be more valuable as a deduction in a year with higher taxable income. This is unusual for most Singapore residents with limited US income. The process is manageable if you understand the baskets, calculate the limitation before filing, and keep organized records. Most errors come from rushing the basket classification or skipping the limitation calculation. Take the time to do it correctly once, and you will avoid correspondence, amendments, and wasted credits. The savings from claiming the credit properly usually outweigh the time spent preparing the forms. For most people with straightforward US dividend income, the entire filing adds about forty-five minutes to their annual tax routine. The alternative is paying US tax without relief, which is an unnecessary cost.