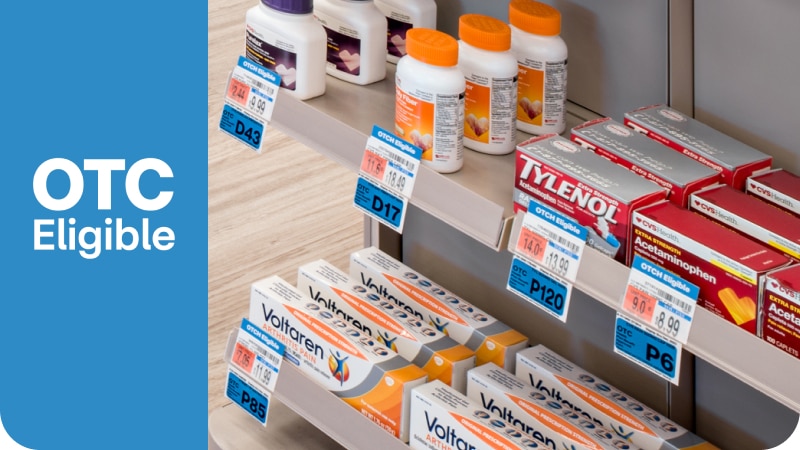
The OTC Card Nobody Explains Properly
Most people get their Aetna OTC benefit card in the mail and immediately treat it like a debit card. That approach wastes money because the system works differently than a normal payment method. You can buy pain relievers, vitamins, bandages, blood pressure monitors, and a handful of other categories, but only within the limits your specific plan sets. The funds reset quarterly. Unused money does not roll over. I learned this the hard way after spending $180 on a blood pressure monitor and a year's supply of vitamins in Q2, then sitting in Q3 with nothing to spend. The system had already reset my quarterly allowance and my prior purchases counted against the previous quarter. It happens to people constantly.Unlocking Savings And Access A Deep Dive Into Cvs Aetna And The Otc Revolution
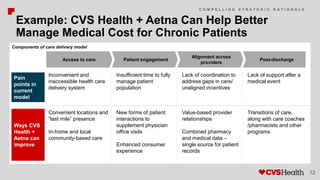
Aetna is owned by CVS Health. That ownership created the structure behind the OTC benefit program most members encounter today. Aetna members with qualifying plans receive a quarterly allowance loaded onto a dedicated benefit card or an approved digital wallet account. The card works at participating retailers. CVS pharmacies are the primary partner, but Walmart, Amazon, and a growing list of other vendors accept the card depending on your plan configuration. The actual savings come from treating the allowance as a targeted budget, not free money. Here is how I would structure it if I were managing this for someone who wants to minimize out-of-pocket health expenses.
How The Benefit Actually Works
Your plan document lists your quarterly OTC allowance. Most standard PPO and HMO plans fall somewhere between $100 and $400 per quarter per member. Some Medicare Advantage plans push higher, occasionally reaching $600 or more annually across four quarters. You do not earn interest. You do not accumulate balance. The window is strictly calendar quarters: January through March, April through June, July through September, and October through December. The card registers to your member ID. Before you make any purchase, you need to verify your registration status through the Aetna member portal or the mobile app. Unregistered cards decline at point of sale more often than people expect. I had a member try to use her card at CVS three times in one week and each transaction was declined. The issue was simple: she never completed the activation step in the app. Once she finished the biometric verification, the fourth transaction went through immediately. Eligible categories include:
- Over-the-counter medications like ibuprofen, antihistamines, and antacids
- First aid supplies including bandages, gauze, and thermometers
- Medical equipment such as blood pressure cuffs, glucometers, and nebulizers
- Vitamins and dietary supplements within plan limits
- Personal health items like sunscreen and allergy test kits
Non-eligible items include prescription drugs, alcohol, tobacco, cosmetic products, and general household goods. The system flags these at checkout. If a cashier scans something ineligible, the POS terminal either splits the transaction across your OTC card and a secondary payment method or rejects the entire basket depending on the retailer's configuration. You can order through three main paths. The Aetna online catalog pushes most members toward it because the interface lists eligible products with clear pricing. Standard shipping takes 7 to 14 business days. Rush shipping is available through select partners and cuts delivery to 3 to 5 business days for an additional fee. The mobile app mirrors the online catalog with the same delivery windows. Phone ordering through Aetna member services works but requires you to read product codes aloud and confirm quantities. I recommend having your member ID and plan number ready. Average hold time ranges from 8 to 22 minutes depending on the quarter and time of day. Calling midweek around 10 AM tends to be faster than calling on the last Friday of a quarter when everyone else remembers their benefits are expiring.
Get the Full Details
In-store purchases at CVS and participating retailers are the fastest option. You swipe or tap the card, the system checks your remaining balance, and you walk out. The catch is that in-store selections are narrower than the online catalog. A CVS shelf might carry twelve eligible pain reliever options while the online portal shows forty-eight. Price comparisons across vendors matter because the same product can appear at different price points. Aetna typically pre-negotiates rates, but the discounts are not always uniform.
A Specific Problem And The Workaround
Last year a member called me about a $240 glucometer she needed. Her quarterly allowance was $200. She assumed she could combine her current quarter's funds with the next quarter's allocation to cover the gap. The system does not allow cross-quarter pooling. The transaction would have been declined for the $40 difference and potentially rejected entirely if the retailer's system requires full coverage through the OTC benefit line. The workaround was straightforward but not obvious from the materials Aetna sends. I checked her plan details and confirmed she was enrolled in a Medicare Advantage plan with a supplemental wellness allowance attached. That wellness allowance sat in a separate bucket from the standard OTC benefit and applied specifically to durable medical equipment. She used the wellness bucket for the glucometer, exhausted the $200 OTC allowance on medications and first aid supplies over the following weeks, and spent zero out of pocket. The key was knowing the plan structure well enough to recognize the secondary allowance. Most members never see this because the summary documentation buries it in fine print.
Common Pitfalls
Quarter-end panic is the biggest one. People who wait until the final week of a quarter and then rush to spend leftover funds often end up buying things they do not need. The system logs every transaction. Repeated purchases of high-value items within a narrow window can trigger fraud review. Aetna's review process pauses your card for 3 to 5 business days while they verify legitimacy. I have seen this happen to legitimate customers who simply bought a seasonal allergy bundle in late March. The card freezes anyway. The fix is submitting proof of purchase and a brief written explanation through the member portal. Resolution takes another 3 to 7 business days after that. Another pitfall involves assuming the card works everywhere. The participating retailer list changes periodically. A store that accepted your card in Q1 may drop out of the network by Q2. Always verify participation before loading your cart. Amazon accepts the Aetna OTC card for eligible items, but only products marked as OTC-benefit-eligible during checkout. Add everything to your cart first, then proceed to payment to see the correct total.
The Limitations You Should Know About
This benefit is not universal. Not every Aetna plan includes OTC allowances. Some employer-sponsored plans exclude it entirely or cap it at $50 quarterly. Some Medicare plans offer it only to members in specific service areas. If your plan does not include the benefit, you cannot opt in by paying extra. The allowance is baked into the plan design. The product selection skews toward low-cost items. High-ticket medical equipment like CPAP machines, wheelchairs, and hospital-grade air purifiers almost never qualify. The system classifies these as durable medical equipment requiring prior authorization through your insurance claim process, not through the OTC benefit channel. If you need expensive equipment, do not try to force it through the OTC card. File a standard DME claim instead. Tax treatment is another area where assumptions cause problems. OTC benefit purchases are generally not considered pre-tax dollars. They do not reduce your taxable income. They also do not qualify for FSA or HSA reimbursement in most cases. If you have an HSA account, consult your plan administrator before attempting to double-dip. Aetna's system does not block dual-use, but the IRS does, and penalties apply.
What Actually Maximizes The Value
Plan your quarterly purchases around your health calendar rather than reacting to symptoms as they arise. If you know you get seasonal allergies in April, order your antihistamines and nasal sprays in March during the new quarter. If you rotate flu shots and related immune support in the fall, front-load those purchases into Q3 instead of spreading them across Q3 and Q4. The calendar-reset mechanic punishes drift. Compare prices between the online catalog and in-store pricing before committing. A $15 box of bandages online might be $12 at a CVS register. The difference is small per item but compounds quickly over a full quarter of purchases. Keep a running spreadsheet or note file of every transaction. The member portal provides purchase history, but it does not organize data in a useful way for budgeting. Logging each purchase as it happens lets you track your remaining balance in real time rather than discovering on checkout day that you have $3.12 left.
The OTC benefit through Aetna and CVS is a real, usable tool when you understand its mechanics. It is not a windfall. It is a quarterly allowance with strict boundaries, and the people who extract maximum value from it are the ones who plan ahead, verify their plan details, and avoid the common timing traps. Most other people leave money on the table or freeze their own cards through suspicious-pattern triggers. Either outcome is preventable with basic awareness of how the system operates.