Ally Auto Dealer Services and Why They Actually Matter for Your Floorplan
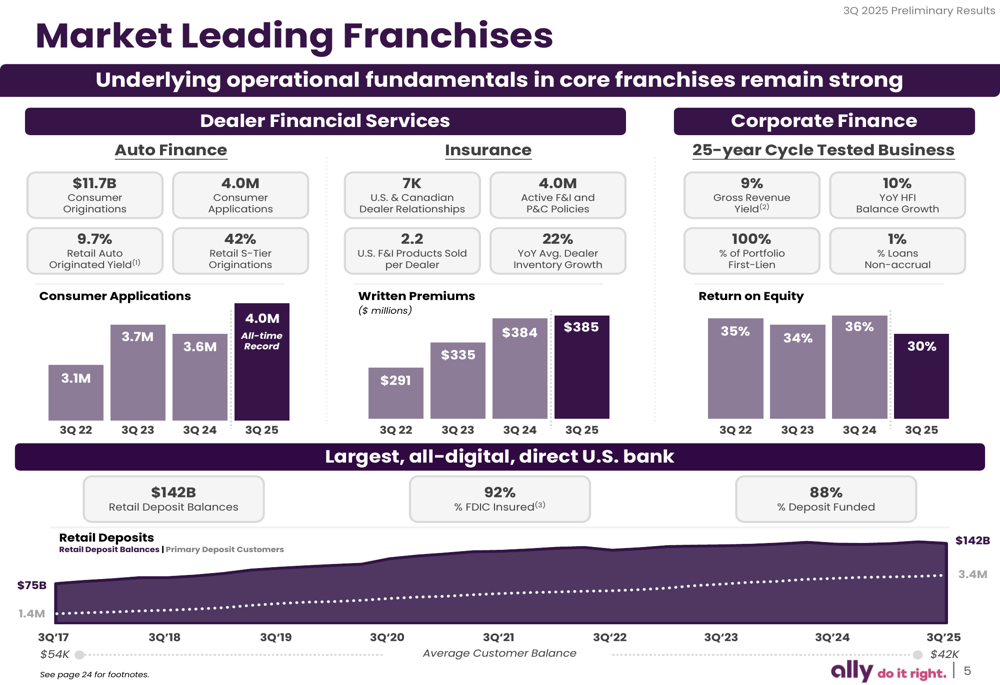
Most dealers treat Ally as just another option on the bid order. That is a mistake. When you actually use their full dealer service suite—floorplan financing, direct lending, and retail support—the numbers shift in ways most people don't track properly. I have been watching this space since the post-2008 restructuring, and the way Ally structures its dealer relationships is different from what you get from a regional bank or the captive programs. Not necessarily better, but structurally distinct. The floorplan piece is where most dealers feel it first. Ally offers both committed and non-committed floorplan lines, and the difference matters more than the brochures suggest. A committed line means they have to lend to you regardless of market conditions, which sounds like safety until you realize the rate on that commitment is typically 100 to 150 basis points above prime. During periods of rate volatility in 2023 and 2024, I watched several mid-size dealers panic when their local bank tightened allocation. Ally had already locked in their commitment. The cost was higher, but the inventory kept flowing.The direct lending side is where the real profitability work happens. Ally funds retail contracts directly through your desk, which means you are not submitting to three different sources and hoping one approves. Their decisions are faster—usually within 30 to 45 minutes for straightforward cases—and the rates are competitive in the prime and near-prime tiers. What they are not good at is subprime. If your market is heavily NINJA or alt-doc, Ally will decline most of those files. I learned that the hard way in 2022 when a dealer near Nashville loaded his lot with 40 cars priced under $12,000, assumed Ally would fund the majority, and then watched a 70 percent decline rate. He was stuck. The workaround was to route the prime-eligible cars through Ally and push the rest to a specialty wholesale channel before they sat past day 45.
Unlocking Revenue Streams A Comprehensive Look At Ally Auto Finance Dealer Services And How They Power Profitability
The revenue streams come from multiple places, and they do not all show up on the same report. Front-end gross is one. Backend finance and insurance profit share is another. Then there is the floorplan interest arbitrage, which is where most dealers lose money without realizing it. Here is how it works in practice: Ally charges you interest on the money they advance to buy the car from the auction or manufacturer. You sell the car and get paid by the retail buyer's lender. If the car sits for 60 days, that interest compounds against your gross. A $25,000 car at 9 percent floorplan rate costs you roughly $375 per month in interest alone. If you are running a 10 percent gross target, that interest eats nearly half your profit before you even pay overhead. The counter-intuitive part is that Ally's system actually gives you tools to track this, but most dealers ignore them. Their online portal shows each VIN's age on floor and daily interest accrual. I made my team run a weekly export of any unit hitting day 30, and we cross-referenced it against our actual gross. The data was clear: units sitting past day 35 on floorplan were statistically destroying our ROI. We started a policy where anything past day 28 gets flagged for aggressive pricing or wholesale transfer. That single habit changed our monthly P&L more than any gross manipulation did.Another thing people miss is the dealer reserve structure. When Ally funds a retail contract, they pay you a reserve based on the interest rate and loan term. Higher rate means higher reserve. This is standard across the industry, but Ally's reserve pacing is slightly different from competitors like Wells Fargo Auto or Ford Credit. In practice, this means your effective gross on a $300 APR contract will differ by $50 to $150 compared to other programs, depending on term length. It is not a dealbreaker, but if you are comparing programs side by side, include the reserve in your calculation, not just the rate offer.
The Operational Reality of Working With Ally
Their technology stack is functional but not elegant. The API integrations work with most DMS platforms—vAuto, Reynolds, CDK—without major issues. The submission portal itself feels like it was last redesigned in 2018. It is stable, which is something, but navigating approvals and status checks takes more clicks than it should. I have spent time comparing this to what LightStream or Toyota Financial offer, and Ally sits somewhere in the middle: more capable than a community bank portal, less polished than a top-tier captive. The approval process itself is mostly automated for standard credit profiles. Pull a credit, enter the loan amount and term, get a decision. The edge cases are where things slow down. I encountered a specific problem last year involving a dealer in the Midwest who was trying to run a bundle deal—a car with a low price and an add-on product that pushed the total contract value above Ally's threshold for automated underwriting. The system rejected the file automatically because the documentation triggered a manual review flag. This happened repeatedly with that particular dealer's product mix. The workaround was straightforward: separate the pure auto financing from the product financing, or adjust the gross profit on the vehicle to stay under the threshold. It is a nuance that is not documented anywhere in their dealer manual, so you find out by failing six times in a row.Another operational detail that nobody talks about enough is the payoff timing. Ally typically wires dealer payoffs within one to two business days after funding confirmation, but if there is a title issue or a state-specific compliance check, that can stretch to five days. I have had dealers claim they never got paid on time when the real issue was a slow title company in a particular county. Tracking your payoff status through the portal and keeping a log of exceptions helps you separate Ally's actual turnaround from downstream problems.
Get the Full Details
When Ally Is Not the Right Call
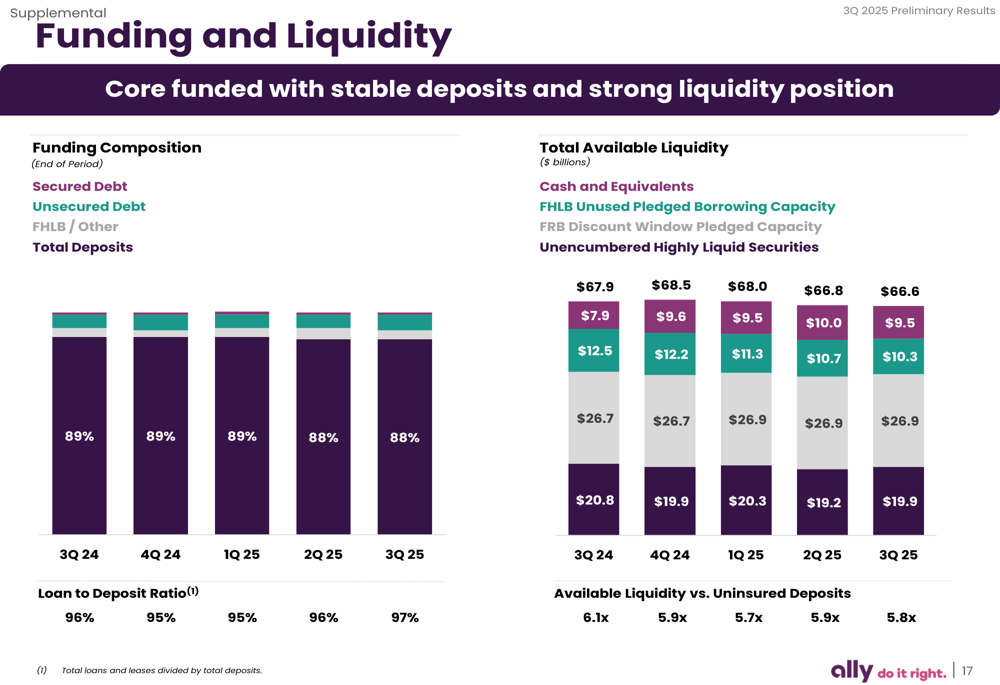
Ally is not universally optimal. Their underwriting model leans conservative on Thin File and recent bankruptcy cases. If your customer base skews heavily toward young buyers with limited credit history, you will see a higher decline rate than with programs from Capital One Auto or Santander Consumer USA. There is no shame in that. Different programs fit different markets. The floorplan rates are also not always the cheapest. Regional lenders and credit unions sometimes offer lower rates on committed lines, especially for dealers with strong relationship histories. A dealer with 20 years at a local credit union might pay 6.5 percent on floorplan while paying 8.5 percent with Ally on a similar commitment level. The trade-off is stability. The credit union can pull your line during a regional economic downturn. Ally generally won't, because their capital markets access is broader. For a dealer who values predictable access over marginal rate savings, Ally makes sense. For someone who can negotiate deeply with a local lender, it might not.One final practical note: Ally's dealer program terms can change without much notice. They have adjusted reserve structures, altered floorplan rate benchmarks, and modified approval thresholds multiple times in the past three years. The best approach is to review your actual results quarterly, not annually. Pull your funding reports, calculate your blended floorplan cost, and compare it against your average gross per unit sold. If the numbers are moving the wrong way, you will see it weeks before anyone else does.