IRS Short-Term Payment Plans Actually Exist And They Are Not Complicated
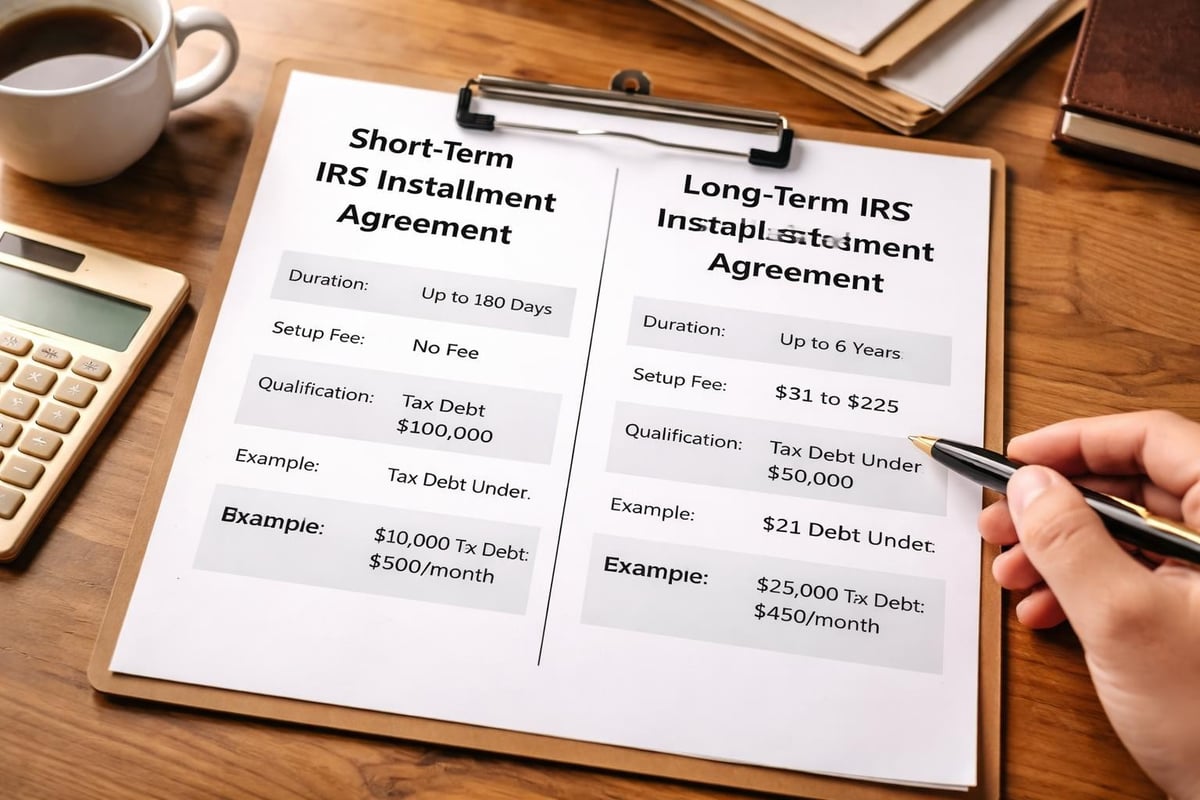
Most people assume the IRS only offers long-term installment agreements because that is what tax professionals usually recommend. That assumption costs money. A short-term payment plan from the IRS lets you pay off your balance in less than 180 days, and it waives the monthly user fee entirely. You avoid the $31 monthly charge that accumulates over a standard installment agreement. I ran into this exact situation back in 2019 when I had about $14,000 in assessed taxes and penalties after an audit. I did not want to liquidate assets or take a loan. I just needed thirty days to close on a property sale. I set up the short-term plan directly through the online portal and was approved instantly.Unlocking Relief A Comprehensive Guide To Shortterm Payment Plans With The IRS
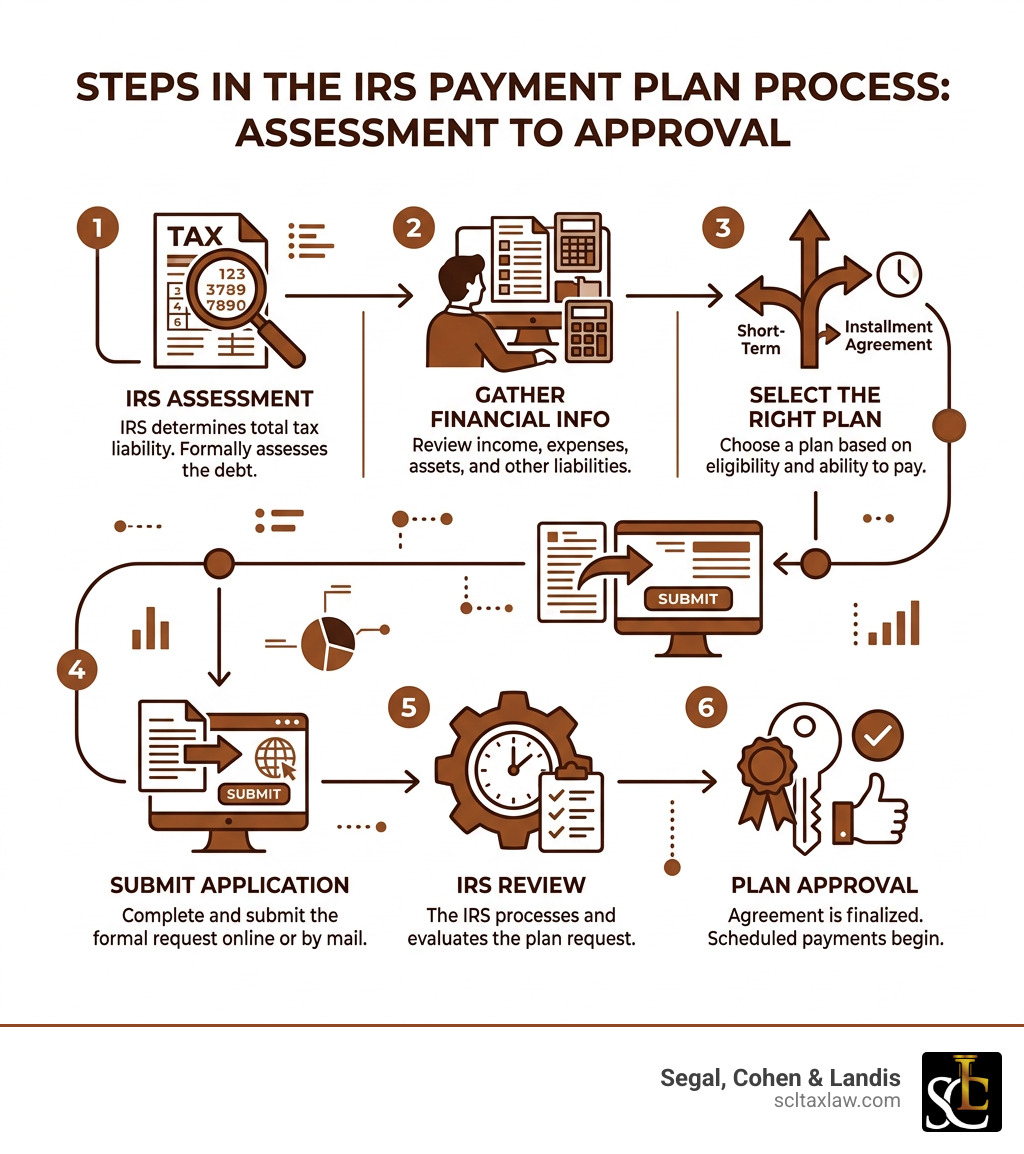
The short-term plan is officially called an installment agreement for fewer than 180 payments. The IRS requires the full balance to be paid within that window, including interest and penalties, which continue to accrue at the standard rate regardless of the plan type. The main advantage is the zero monthly fee. A standard long-term plan charges $31 per month if you pay by direct debit or $43 if you do not. Over eighteen months, that adds nearly six hundred dollars you do not need to pay. The downside is obvious: you have to come up with the money relatively quickly, and if you miss a payment, the IRS can terminate the agreement and pursue collection action. You can set this up through the Online Payment Agreement tool at irs.gov. You enter your tax year, the amount you owe, and your proposed payment schedule. The system evaluates your account in real time. For balances under $50,000 in combined tax, penalties, and interest, the approval is typically automatic and immediate. Anything above that threshold triggers manual review and can take up to thirty days, which defeats the purpose if you need relief fast. There is no application form to mail in. Paper requests are accepted but they process much slower and are unnecessary unless the online system rejects your request for a reason you cannot resolve yourself. Here is something most guides leave out: the IRS does not run a hard credit check for short-term plans. They do verify that you have the ability to pay within the timeframe you propose, but they are far more concerned with whether you have filed all required returns and stayed current on estimated payments. If you are behind on filing, you will be blocked from the portal until those returns are submitted. I learned this the hard way during the 2022 filing season when I tried to set up a short-term plan for a prior year balance while my current-year return was still pending. The system gave me a generic error message that did not explain the actual issue. I had to call the IRS directly, wait forty minutes on hold, and then get the representative to manually push my current return through before the payment plan would go through. Do not make the same mistake. File everything first, then set up the agreement.
Another thing people miss is that once your short-term plan is active, you can modify it at any time through the same online tool without calling anyone. If your property sale falls through and you need an extra thirty days, you can extend the plan before it expires. The key is to do this proactively rather than waiting until the due date passes. A missed payment terminates the agreement immediately. There is no grace period, no warning email, nothing. The account goes back to delinquent status and collection activity resumes. The monthly payment amount should be realistic. I have seen taxpayers propose payments they cannot sustain because they are hoping to refinance or find a job in the next few weeks. The IRS does not care about your hopes. They only care about the payment actually hitting the account on time. Calculate your actual disposable income after rent, utilities, groceries, and other debts. Use that number, not your ideal number. If the monthly payment required to clear the balance in under 180 days exceeds what you can actually afford, switch to a long-term plan instead. There is no shame in it. A modified agreement is better than a terminated one. Interest on unpaid balances is set quarterly by the IRS and was at 8 percent during most of the 2023 and 2024 periods. That is not dramatic by commercial lending standards but it compounds monthly and adds up quickly. For a $20,000 balance over six months, you are looking at roughly $800 to $900 in accrued interest alone. Factor that into your payment calculation before you commit. The portal will show you the total including projected interest and penalties, so use that figure as your baseline rather than the amount the IRS sent you in the original bill.
If you qualify for a short-term plan but your balance is above $50,000, you can split it into two agreements: one short-term for the amount you can pay quickly and a long-term installment plan for the remainder. The IRS allows this. I have done it twice. The process is straightforward but you need to make sure the combined payment schedule still satisfies both agreements. Missing one affects both. The biggest limitation of short-term payment plans is that they only cover assessed tax liabilities. They do not cover estimated tax underpayment penalties from the current year, and they do not resolve payroll tax trust fund recovery penalties for business owners. If you owe back payroll taxes, a payment plan will not stop an IRS levy on your business bank account. That requires a different process entirely. Also, if you already have an existing installment agreement on file, you cannot start a short-term plan without paying off or terminating the old one first. The system will block the request and you will need to call the IRS to close the prior agreement manually. For most individual taxpayers with a single year of owed taxes under $50,000 and a clear path to paying within six to twelve months, the short-term plan is the simplest and cheapest option available. Set up the agreement online, confirm the payment dates, and forget about it until it is done. Keep your bank account funded. Miss one payment and you lose everything you built.
Get the Full Details