Calculating NPV Without Overcomplicating It
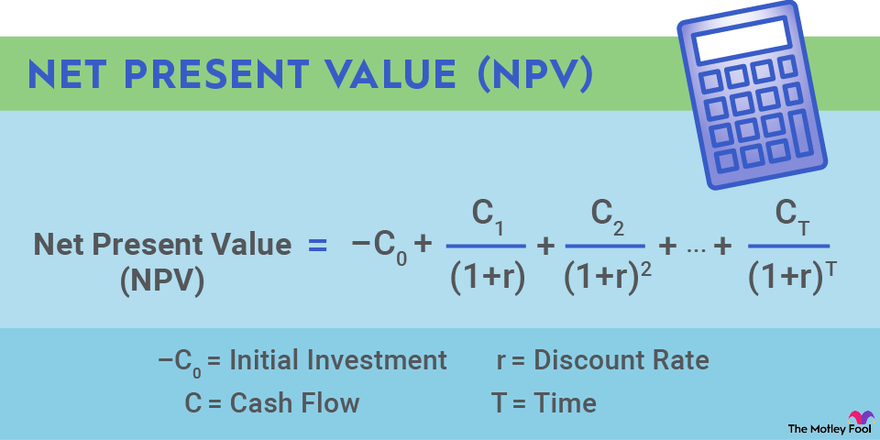
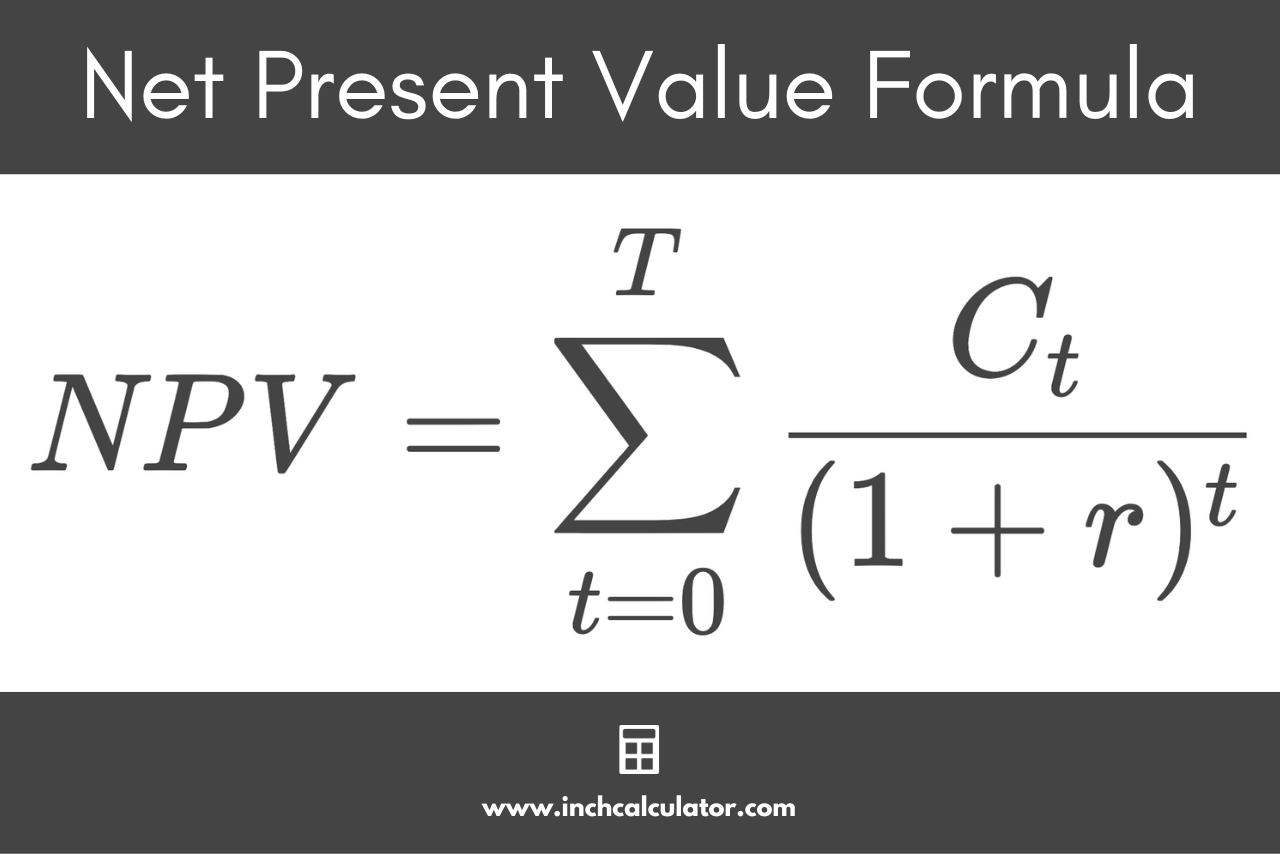
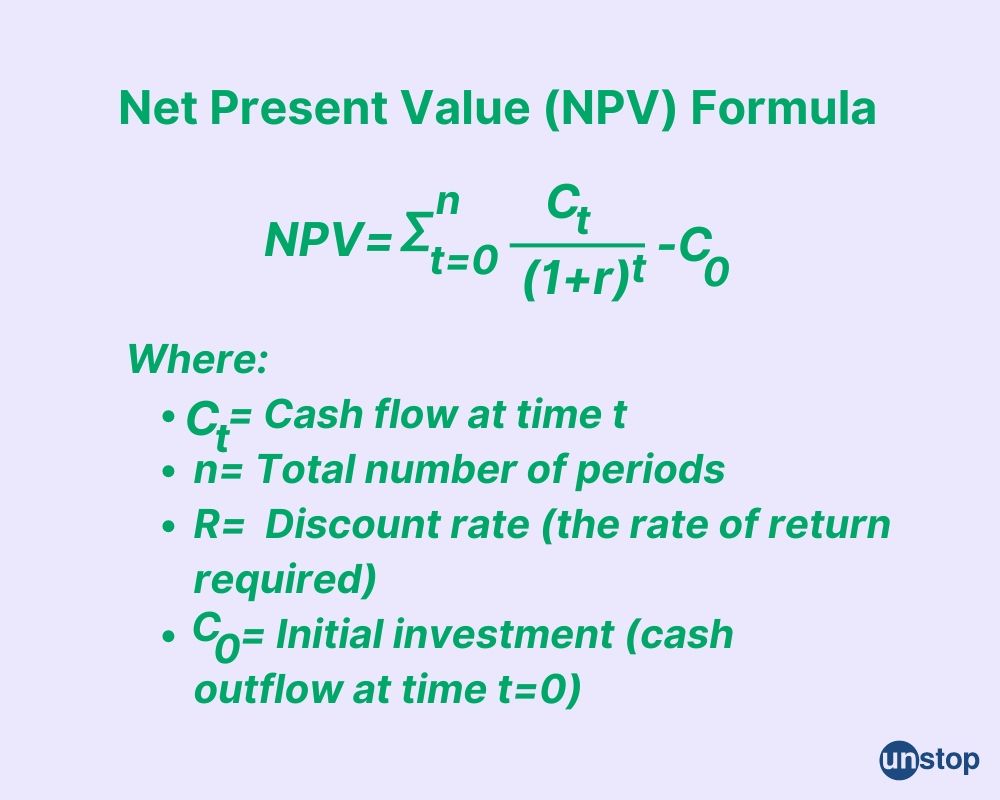
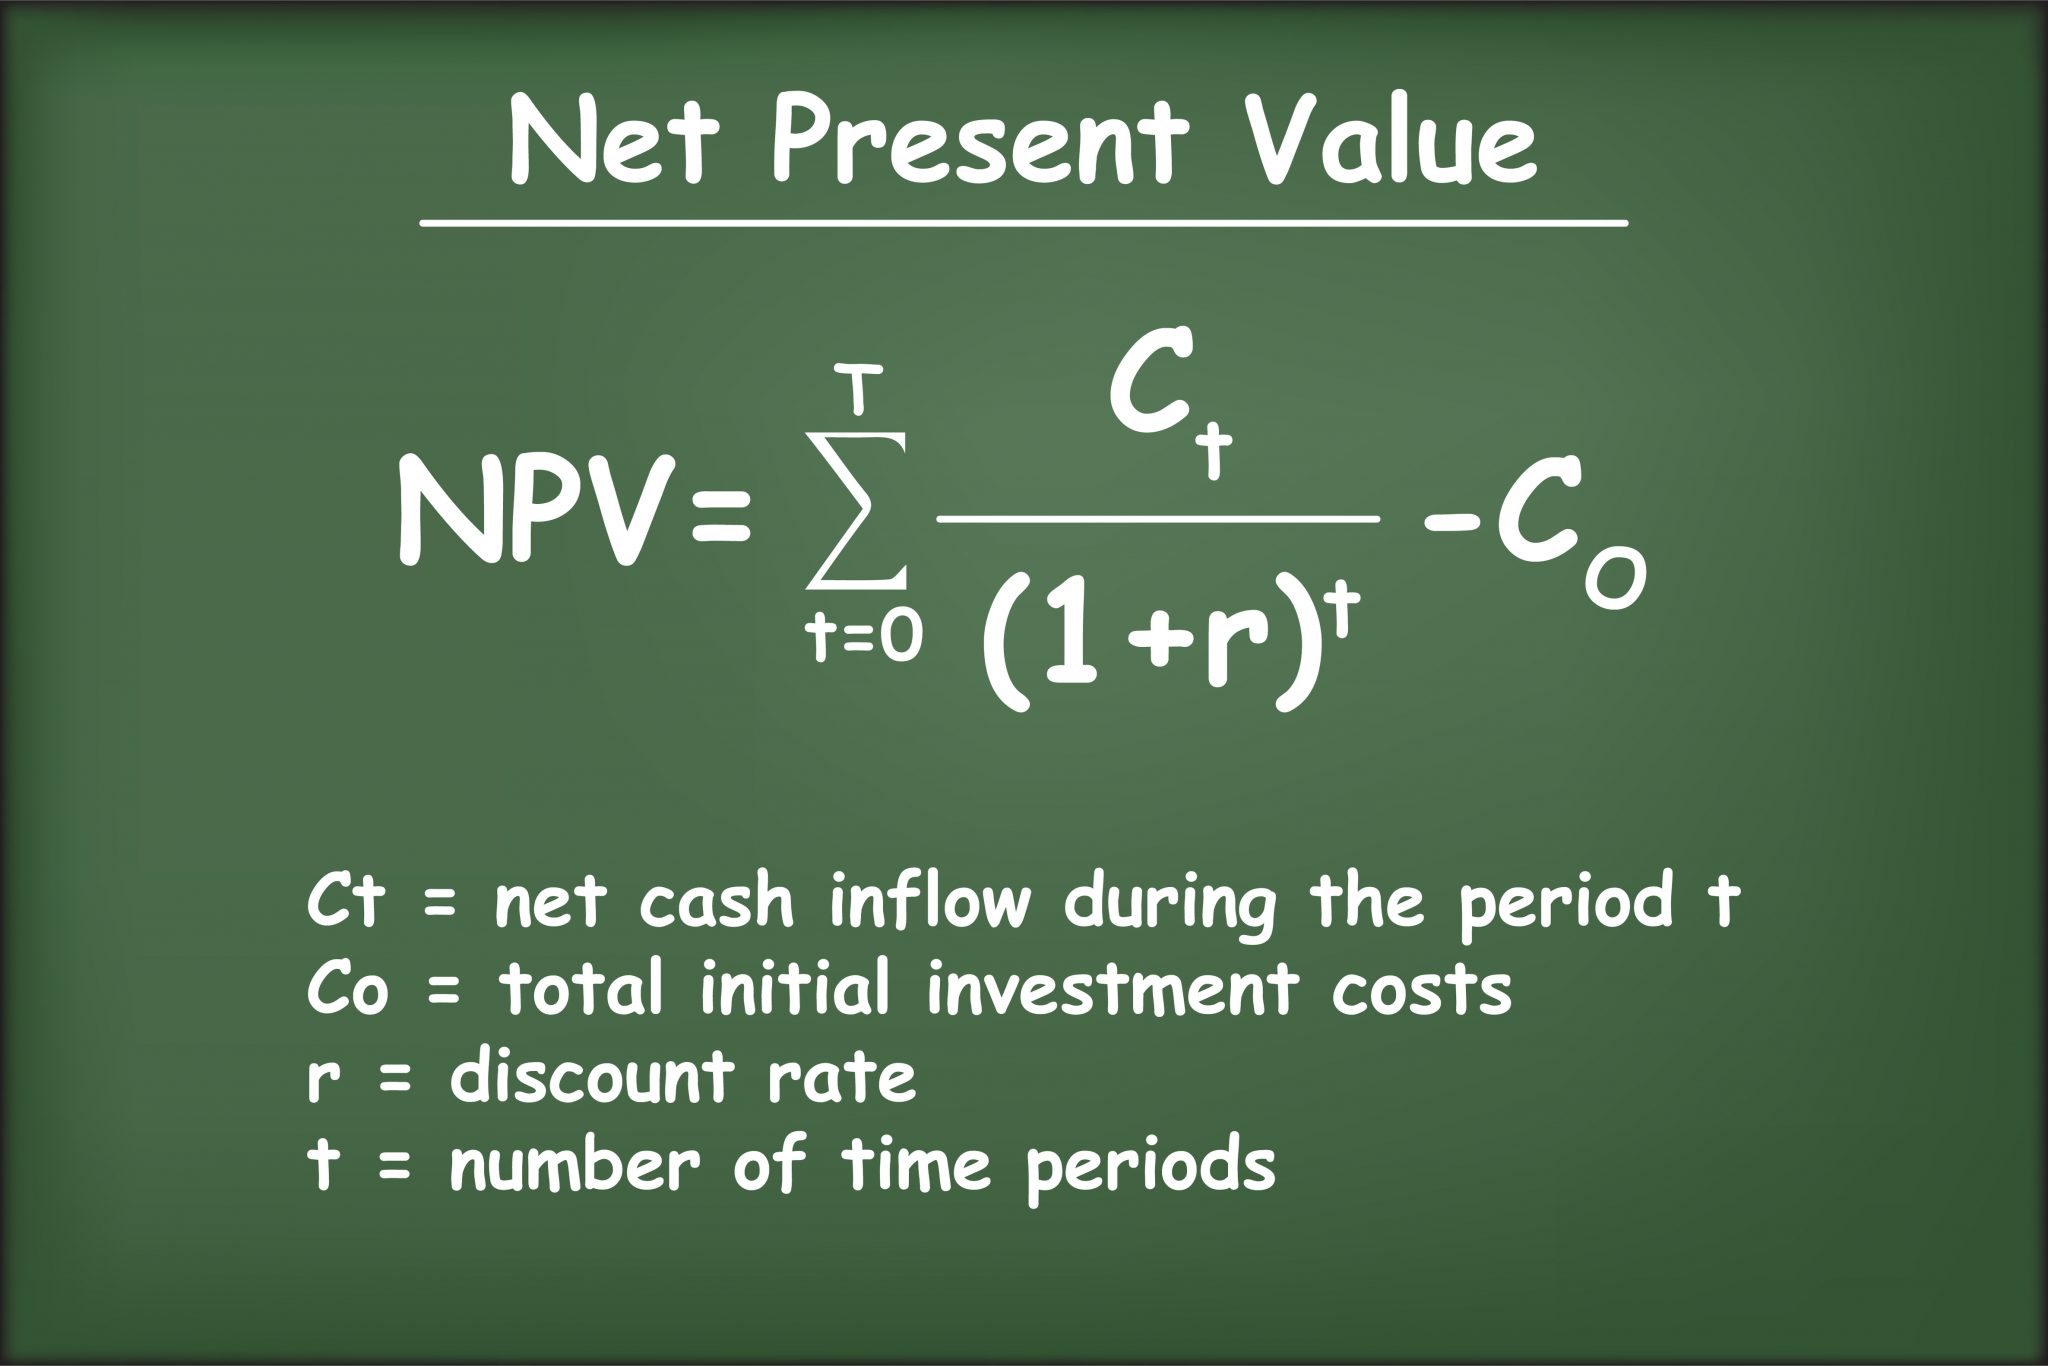
I spent years watching people treat NPV like it was some sort of crystal ball for business decisions. It isn't. It's a calculation that tells you whether a series of cash flows, discounted at a particular rate, adds or destroys value. That's it. The formula itself is straightforward. You plug in the numbers. The hard part is knowing what numbers to actually use. The formula looks like this on paper: NPV = [Cash Flow in period t / (1 + r)^t] minus the initial investment.
Or written out more clearly: you take each future cash flow, divide it by one plus your discount rate raised to the power of the period number, then subtract whatever you put in upfront. That's the entire thing. If the result is positive, the investment beats your required rate of return. If it's negative, you'd be better off parking that money elsewhere at the same risk level. Let me walk through an actual example. Say you're evaluating a piece of equipment that costs $50,000 today. It generates cash flows of $15,000 in year one, $18,000 in year two, $22,000 in year three, and $20,000 in year four. Your required rate of return, or discount rate, is 10 percent. Here's what the math looks like period by period: Year zero: minus $50,000. Year one: $15,000 divided by 1.10 to the first power, which is $13,636. Year two: $18,000 divided by 1.21, or $14,876. Year three: $22,000 divided by 1.331, or $16,529. Year four: $20,000 divided by 1.4641, or $13,661. Add up the discounted cash flows: $58,702. Subtract the initial outlay of $50,000. Your NPV is $8,702. Positive. The project clears the hurdle.
Now here's where most people go wrong. They pick a discount rate from a spreadsheet template or borrow someone else's WACC without thinking about what that rate actually represents. The discount rate should reflect the opportunity cost of capital for that specific investment, not just whatever the CFO says sounds right in the meeting. If you're comparing a low-risk utility project against a high-risk startup venture and you use the same 8 percent discount rate for both, your NPV numbers are meaningless. They'll look identical in structure but tell completely different stories about risk-adjusted returns. I ran into this exact problem back in 2019 when I was modeling a warehouse expansion for a mid-sized logistics company. The spreadsheet had a single discount rate of 9 percent baked in from the executive summary. But the expansion involved two distinct components: a ground-level storage addition with stable, inflation-linked lease income, and a mezzanine automation system whose payback depended entirely on labor cost trends over the next decade. Using one 9 percent rate for both meant the automation piece looked far more attractive than it actually was. I recalculated by splitting the project into two separate cash flow streams, applied 7 percent to the lease component and 14 percent to the automation component based on their respective risk profiles, and the combined NPV dropped by roughly $200,000. The board killed the automation portion before anyone wasted money on it. That's the value of getting the inputs right rather than trusting the formula to save you. There are a few things the standard NPV formula doesn't handle well, and you should know about them before you present the output to anyone who has budget authority.
Get the Full Details
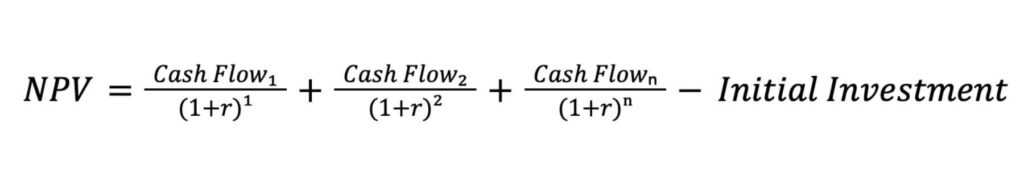
Sensitivity to the discount rate is extreme in long-duration projects. A difference of just one percentage point in your discount rate can swing an NPV by tens of percent when you're looking at ten or twenty years of cash flows. I've seen projects flip from "invest" to "pass" on a half-point rate adjustment. Always run a sensitivity table. Two or three columns for different rate scenarios takes ten minutes in Excel and saves you from looking careless in a review meeting. NPV assumes you can reinvest cash flows at the discount rate. That's a theoretical assumption baked into the math. In practice, you won't always have opportunities that yield your discount rate. When cash flows come in early, they sit idle or get deployed at lower returns. This tends to overstate the NPV for projects with front-loaded cash flows. If that describes your situation, consider using the modified internal rate of return instead, which lets you specify a separate reinvestment rate. It doesn't account for managerial flexibility. A plain NPV calculation treats a project as a one-way street. You commit now and ride the cash flows. But in reality, you can often expand, contract, defer, or abandon a project based on how things play out. That flexibility has value. Real options analysis captures it, though it adds significant complexity. For most day-to-day decisions, I just note the limitation in the margins of my model and move on. Not every decision needs a full real options framework, but you should acknowledge that your NPV is a floor, not a ceiling, on the project's true value.
If you want a practical file to work from, I keep a Google Sheets template at this link that lays out the periods, cash flows, discount rate input, and a built-in NPV calculation using both the Excel NPV function and a manual period-by-period breakdown so you can see exactly where each number comes from. The manual column catches errors that the single-function approach sometimes masks because NPV in Excel actually starts discounting from period one, not period zero, which trips people up if they feed it the initial outlay as part of the cash flow range. Speaking of that Excel quirk, it's worth mentioning explicitly. The NPV function in Excel and Google Sheets assumes your first cash flow occurs at the end of period one. If you include your initial investment in the same range, the function will discount it back one extra period and give you a wrong answer. The workaround is simple: calculate the NPV of only the future cash flows using the function, then subtract the initial investment separately. So it becomes NPV(rate, future_cash_flows) minus initial_outlay. It seems obvious in hindsight, but I've seen senior analysts make this mistake on pitch decks more than once. The other practical consideration is timing. If cash flows come in monthly rather than annually, you need to adjust the discount rate to a monthly equivalent. You can't just divide an annual rate by twelve and call it a day. The correct approach is to use the effective monthly rate, which is (1 plus annual rate) raised to the one-twelfth power minus one. For a 10 percent annual rate, that gives you roughly 0.797 percent per month instead of the 0.833 percent you'd get from simple division. The difference is small in the short term but compounds noticeably over multiple periods.
NPV is useful. It's not universal. When you're dealing with mutually exclusive projects of very different sizes, NPV can favor the larger project even if the smaller one delivers a better percentage return on capital. In those cases, pair NPV with an profitability index calculation, which divides the present value of future cash flows by the initial investment. That gives you a ratio that normalizes for scale and lets you compare projects on an apples-to-apples basis. A $1 million project with an NPV of $200,000 and a profitability index of 1.2 may look worse on paper than a $100,000 project with an NPV of $50,000 and an index of 1.5, but the second project is actually using capital more efficiently. For projects with uneven, irregular cash flows where the timing matters a lot, I usually build a month-by-month model rather than an annual one. Annual models smooth over important detail. A construction project might have zero cash flow for six months, then a massive outlay in month seven, followed by gradual revenue ramp-up. An annual model would lump all of that into year one and make the discounting almost meaningless. Monthly granularity adds maybe twenty minutes to the build time but catches timing mismatches that annual models completely miss. One more thing that people overlook: the discount rate should be pre-tax or post-tax consistently depending on how you treat the cash flows. If your projected cash flows are after-tax numbers, your discount rate needs to be an after-tax rate, typically your WACC adjusted for the tax shield on debt. Mixing pre-tax cash flows with after-tax discount rates, or vice versa, will give you a number that looks precise but is fundamentally wrong. I learned this the hard way on a cross-border acquisition model where one team used pre-tax cash flows and another used an after-tax WACC. The combined model showed an NPV of nearly $40 million. After reconciling the tax treatment, the real NPV was closer to $12 million. The deal still went through, but the purchase price got renegotiated aggressively.

Bottom line: the NPV formula is simple. Applying it correctly takes attention to the inputs, the timing assumptions, and the limits of what the model can actually tell you. Build the model carefully. Stress-test the rate. Acknowledge what it leaves out. The rest is just arithmetic.