Understanding the Saudi Financing Landscape
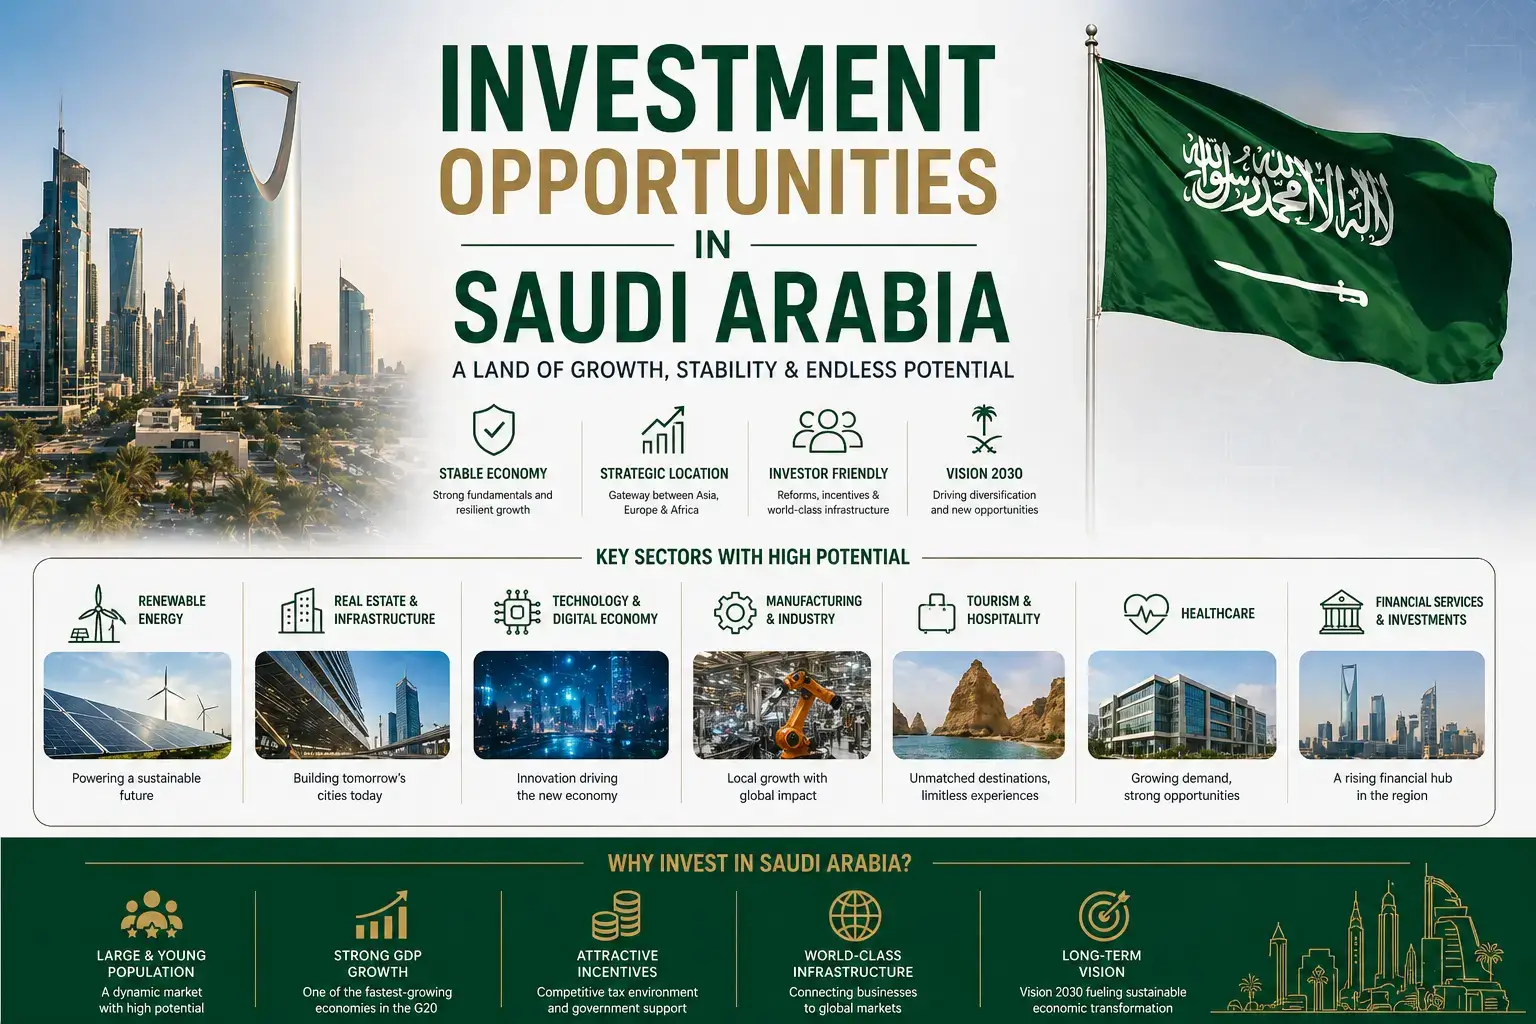
Saudi Arabia has undergone a massive shift in how businesses access capital over the past few years. The Kingdom's Vision 2030 pushed hard on SME financing, alternative lending structures, and digital-first financial services. If you're looking into financing options here, you need to understand that the traditional bank route is only one piece of the puzzle. There are government-backed programs, private fintech lenders, Islamic financing structures, and regional development funds that all operate differently. The term Unlocking Opportunities Oscecasc Financing In Saudi Arabia came up repeatedly in conversations with local business owners I've worked with over the years. It refers to the combined set of pathways — some formal, some less documented — that allow foreign and domestic enterprises to tap into capital that isn't immediately obvious from a surface-level search. Most people miss the less advertised routes because they only look at major bank brochures or generic government portals.
Unlocking Opportunities Oscecasc Financing In Saudi Arabia
The practical reality of accessing these financing channels starts with understanding the regulatory framework. The Saudi Arabian Monetary Authority (SAMA) regulates most lending activities. The Ministry of Investment (MISA) handles foreign ownership and licensing. Monsha'at — the Small and Medium Enterprises General Authority — runs programs specifically for SMEs. These three bodies interact in ways that aren't always clearly mapped out, and navigating them requires some patience. One thing that catches people off guard is how much the classification of your business affects which programs you qualify for. A company registered as a general trading LLC will have a completely different eligibility profile than one registered as a technology service provider, even if they're run by the same people and operating in the same city. I learned this the hard way when I was advising a client last year who had applied to three different government support programs and got rejected from all of them. The issue wasn't their creditworthiness or their business plan. It was their industry classification code. Once we reclassified under a different SIC-compatible category, two of those programs became immediately accessible. The whole process took about ten business days and cost roughly SAR 2,000 in government fees.
How the Main Financing Channels Actually Work
Bank financing in Saudi Arabia follows a fairly standard model, but the approval timelines and documentation requirements vary significantly between institutions. AlRajhi Bank, SNB, and Riyad Bank are the largest players, and each has its own internal risk model. Smaller banks like Bank AlJazira and Alinma tend to be more flexible with collateral requirements but charge higher margins. This isn't a universal rule, but it held true across the cases I've seen over several years of working with business owners in the region. Islamic financing structures — murabaha, ijara, and mudaraba arrangements — are not just for Muslim-owned businesses. Many foreign investors in Saudi Arabia opt for these structures because they can offer better terms than conventional loans, especially for asset procurement and working capital. The key difference is that the bank takes ownership of the asset and leases or resells it to you rather than simply lending you money. This changes the entire documentation chain. You'll need property valuation reports, title deeds, and warranty certificates that you wouldn't need for a standard loan. Allow an extra three to four weeks for this type of financing. Microfinance through the Enhanced Sustainability Program (ESP), formerly known as Khalis, is another route that most people overlook. It's designed for micro and small enterprises with annual revenue below SAR 3 million. The maximum facility is SAR 500,000 with a profit rate that's generally lower than commercial bank offerings. The catch is that they require a detailed business plan and often ask for a personal guarantee from the sponsor. I've seen applications approved in as little as seven days and others stuck in review for six weeks. The difference usually came down to how complete the initial submission was.
Get the Full Details

Common Pitfalls and What They Cost You
Foreign investors face a specific set of obstacles that Saudi-based entrepreneurs don't. The most significant is the requirement for a Saudi sponsor or a properly structured joint venture in many cases. Even with 100% foreign ownership now permitted in most sectors under MISA, lenders still prefer dealing with a local entity that has an established credit history. A newly incorporated company with no transaction history will find it nearly impossible to secure financing above SAR 200,000 without personal guarantees or collateral. Another issue is the credit bureau system. The Saudi Credit Bureau (SIMAH) aggregates financial data from all licensed lenders. If you have any missed payments, even on a personal credit card from years ago, it will appear on your business credit report. I had a client who was stunned to learn that a SAR 150 payment he forgot about on a dormant bank account in 2019 was blocking his ability to get a business line of credit in 2024. Getting it resolved required a formal dispute process through SIMAH that took about three weeks and coordination with his former bank. The visa dependency issue is real too. Many financing programs tie the sponsor's personal residency status to the business's eligibility. If your iqama is tied to a different employer or your sponsorship transfer is pending, your application will likely be deprioritized or rejected outright. This affects both expatriate business owners and Saudi nationals who are still working through sponsorship changes.
Practical Steps to Approach This
Start by getting your business classification right. Check your MISA license and ensure the activity codes align with the financing programs you want to access. This single step alone will save you months of rejected applications. Then build a relationship with at least two financial institutions before you actually need the capital. Walk into a bank with a pre-existing relationship and a clean credit profile and you'll get a fundamentally different experience than someone who walks in cold. Prepare your documentation package completely. Saudi lenders typically request commercial registration, MISA license, ten-year financial projections, three years of audited financials if available, personal credit reports for all sponsors, property valuations for collateral, and a detailed use-of-funds statement. Having everything ready before you submit cuts the average processing time from around forty-five days to roughly twenty days. I've also found that submitting a handwritten cover letter explaining your business in simple terms can actually help. It's an odd quirk of the system, but relationship-based lending still carries weight here more than in many Western markets. Consider alternative financing if traditional routes don't work for you. Invoice factoring through fintech platforms like Tamtem and other SAMA-licensed providers can give you cash flow relief without going through a full credit application. Equity crowdfunding is available through platforms like Thweeter and Rimal. For larger needs, venture debt and growth capital are becoming more accessible through funds like the Public Investment Fund's ecosystem and various private equity houses focused on the Gulf region.
The financing environment in Saudi Arabia is actively evolving. New regulations drop regularly, new programs launch, and some older ones get sunset. Staying current requires checking the SAMA announcements page and Monsha'at updates at least monthly. The people who succeed with this are the ones who treat it as an ongoing process rather than a one-time application exercise.