Setting Up INTP E-Wallet for E-Commerce 2 Payments
INTP e-wallet is a digital payment platform that's been gaining traction in Malaysia, particularly among small to medium enterprises in Kuala Lumpur looking to modernize their transaction processes. The E-Commerce 2 system integrates directly with their platform, allowing businesses to accept contactless payments, QR transactions, and online checkout flows without needing a traditional merchant account from a bank. I've been working with this system for about two years now, and honestly, it's functional but has some quirks you need to navigate. The basic setup process involves downloading the INTP app from either the Play Store or App Store, creating a business account with your SSM registration documents, and then linking it to your e-commerce platform through their API dashboard. The whole onboarding typically takes about 3 to 5 business days if your documentation is in order.
Unlocking Malaysias Digital Future Itng Ewallet Ecom 2 Revolutionizes Transactions In Kuala Lumpur
The actual transaction flow works like this: a customer scans a QR code or enters a payment link, funds are deducted from their e-wallet balance or linked bank account, and you receive the settlement in your INTP merchant account within one to two business days. The standard transaction fee sits around 1.5 to 2 percent, which is competitive compared to traditional card payment gateways that run 2.5 to 3.5 percent plus fixed fees. One thing that catches people off guard is the settlement timeline. Unlike some platforms that promise same-day settlement, INTP operates on a T+1 or T+2 basis depending on your transaction volume tier. If you're processing over 50,000 ringgit monthly, you can qualify for next-day settlement, but you need to apply separately through your merchant dashboard. I learned this the hard way when I had a client expecting same-day funds during a busy sales period and had to explain the delay. The API integration itself is straightforward for developers. INTP provides REST-based endpoints with documentation available on their developer portal. You'll need to generate API keys from the merchant console, set up webhook URLs for real-time payment notifications, and implement their signature verification process. The sandbox environment is functional and lets you test most scenarios before going live.
Here's a practical issue I ran into recently that the documentation doesn't really cover well. When customers have multiple payment methods linked to their INTP wallet, the system doesn't always prioritize the balance method automatically. I had a situation where a customer with sufficient e-wallet balance ended up being charged to their linked card instead, which caused confusion and support tickets. The workaround is to explicitly configure your checkout flow to display the available balance amount and prompt users to select their preferred payment method rather than relying on default behavior. Another nuance worth mentioning is the handling of partial refunds. INTP's system supports partial refunds through their merchant dashboard or API, but there's a quirk where refunded amounts go back to the original payment method, not as wallet credit. If your customers are expecting to receive refund balances they can reuse immediately, you need to communicate clearly that the refund returns to their source payment method and will follow that method's processing timeline. For fraud prevention, INTP includes basic chargeback protection, but it's not as robust as what you'd get from larger payment processors. Their fraud scoring is rule-based rather than machine-learning-driven, which means legitimate transactions occasionally get flagged while some sophisticated fraud attempts slip through. I recommend implementing your own additional verification layer for high-value transactions above 500 ringgit, especially for new merchants on the platform.
Get the Full Details
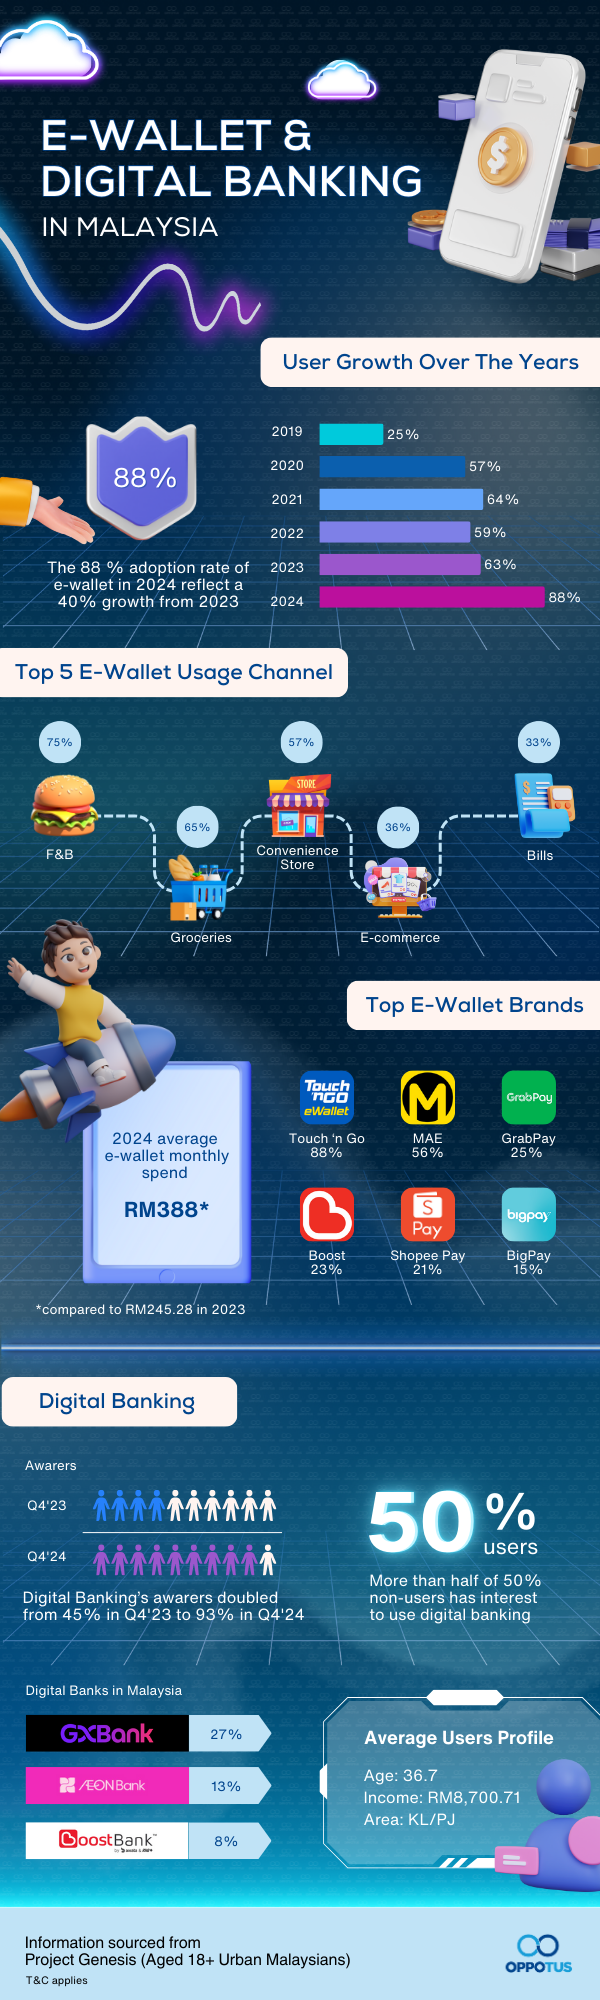
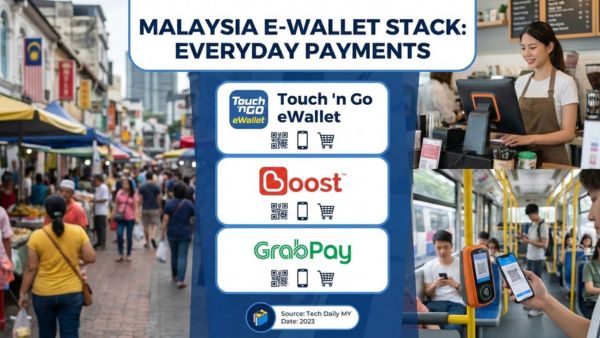
The customer support experience is mixed at best. Email support typically responds within 24 to 48 hours, and their phone support line has limited operating hours. During peak periods, wait times can extend significantly. If you're running a serious operation, having a dedicated relationship manager through their business tier would be worthwhile, though that requires minimum monthly transaction volumes of around 100,000 ringgit. If INTP isn't quite fitting your needs, alternatives like TnG eWallet's merchant solutions, Boost, or even traditional processors like iPay88 are worth evaluating. Each has different fee structures, settlement times, and feature sets. TnG, for example, has a much larger existing user base in Malaysia but charges slightly higher merchant fees. Boost offers good integration flexibility but has less brand recognition among older demographics. The key takeaway is that INTP e-wallet with E-Commerce 2 is a viable option for Kuala Lumpur-based businesses, especially those doing moderate transaction volumes. It's not a perfect solution, but it's functional and competitively priced if you understand its limitations upfront and build appropriate workarounds into your operations.