How real estate crowdfunding actually works on the ground in Kenya
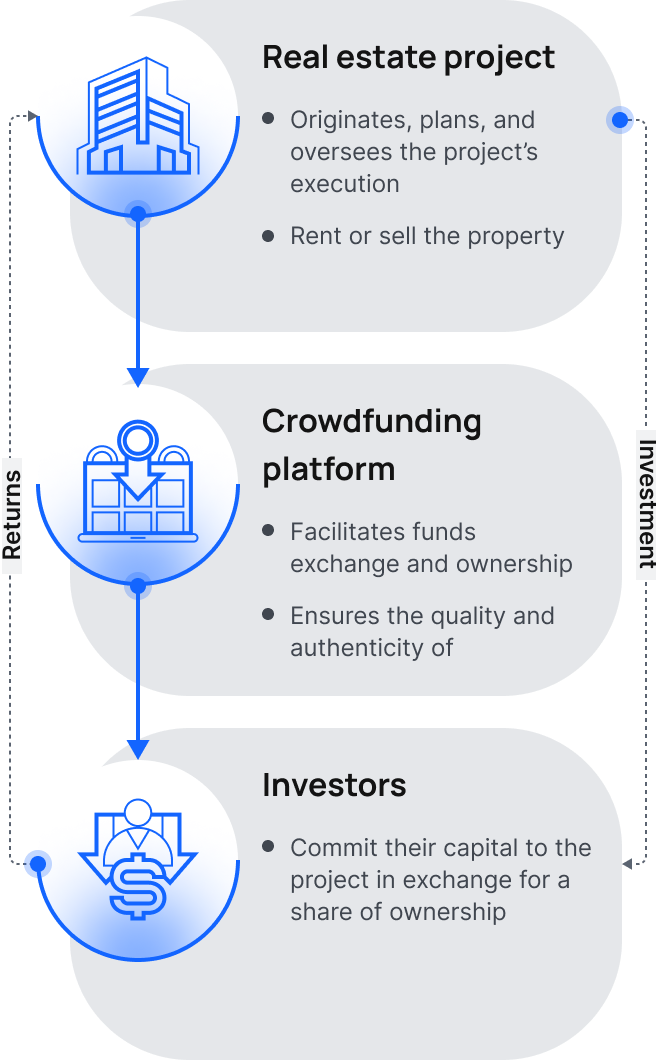
Most people stumble into this space because they see posts about property returns and assume it is simpler than it is. It is not simple, but it is structured enough that you can navigate it without losing money if you pay attention to the paperwork. I have spent the last few years watching platforms come and go, and I have put my own capital into several deals across Nairobi and the coastal region. The mechanics are straightforward once you strip away the marketing copy. You start by picking a licensed platform. The Central Bank of Kenya does not directly license these platforms, but the Capital Markets Authority has been moving toward regulation, so always verify that the operator is registered with the CMA or at minimum holds a valid business license from the Kenyan government. There are a handful of active platforms now — Rejuva, Stari Land, and PropertyCrowd Kenya among them — but the landscape shifts quickly. New ones pop up every quarter and some disappear within a year. I learned this the hard way after committing funds to a platform that was still in beta and essentially unregulated. The money was technically accessible, but the withdrawal process took forty-seven days instead of the stated fourteen. That was a valuable lesson in checking licensing status before transferring anything. The basic structure is this: a sponsor identifies a property project, usually a residential development in areas like Atherton, Syokimau, or Runda, or a commercial build in Westlands or Mombasa. They create a SPV — a special purpose vehicle — to hold the asset. Investors pool money through the platform to fund the project. You receive units or shares in that SPV. Returns come from rental income distributed periodically and from capital appreciation when the property is sold. The typical target yield sits between 12 and 18 percent annually, though actual payouts vary significantly depending on occupancy rates and how smoothly the construction phase goes.
Here is what nobody warns you about early on. The minimum investment on most Kenyan platforms ranges from 50,000 to 100,000 Kenyan shillings. That sounds accessible. The real issue is that your capital gets locked up for the entire duration of the project, which is typically eighteen months to three years. There is almost never a secondary market where you can sell your units before the property is ready or sold. I had an investor friend who needed liquidity during a medical emergency and tried to exit a half-finished project on Stari Land. The platform owner told him the transfer paperwork existed but that finding another buyer who wanted to take over mid-project was nearly impossible. He ended up waiting another fourteen months. This liquidity risk is the single biggest problem most newcomers ignore.
The due diligence process most people skip
Before you invest in any deal, you need to request and review three specific documents. The first is the feasibility study for the project. This should show land value, construction cost estimates, absorption rates for the area, and projected sales or rental income. If the platform cannot produce this document or the numbers look fabricated, walk away. The second document is the title deed and any encumbrance search. I always pull an official search from the Ministry of Lands myself rather than trusting the platform's copy. In 2023, a deal I was monitoring had a title that appeared clean on paper but carried an undocumented family dispute that surfaced during my independent search. The platform had no idea. The project was paused for six months and I pulled my money out before construction delays impacted returns. The third document is the SPV registration with the Registrar of Companies. This confirms that the legal entity holding the property actually exists and that your investment creates a legitimate ownership stake. Without this, you are just lending money to a platform with no legal claim to the underlying asset. I also check whether the platform holds investor funds in a segregated account or commingles them with operational money. Segregation matters enormously if the platform itself faces financial trouble. A commingled account means your money could get tangled in the operator's debts. The KYC process on these platforms usually takes between one and three business days. You will need your national ID or passport, a KRA PIN certificate, proof of address, and a completed risk profiling questionnaire. Some platforms require a bank statement from the account you will use for funding. The whole onboarding process typically takes about twenty minutes if you have your documents organized. I keep a dedicated folder on my phone with scanned copies of everything, which saves me roughly fifteen minutes per new platform registration.
Get the Full Details

What actually happens after you invest
Once your funds are committed, you receive regular updates. Most platforms send monthly progress reports with photos from the construction site and financial summaries. These are useful but also somewhat standardized. The real signal is in the delays. If a project that was supposed to complete in month eighteen is still in the roofing stage at month twenty, that is a warning sign. I track this by keeping a simple spreadsheet with the promised completion dates and comparing them against the actual progress photos. Over four projects, I found that platforms with consistent monthly photo updates had only one major delay, while those with sporadic reporting had two or three significant setbacks each. The frequency of communication correlates with project management quality more than you would think. Rental income distributions, when they occur, are typically paid quarterly via M-Pesa or bank transfer. Tax is withheld at source under the current Kenyan regulations. The withholding rate on rental income for non-resident investors is 15 percent, and for resident individuals it follows the standard PAYE brackets. Capital gains tax applies when you eventually sell your units or the SPV sells the property, currently set at 30 percent for individuals on the gain above the original purchase price. I consult a tax advisor once a year specifically for these holdings because the rules change frequently and the platforms do not always provide clear tax documentation.
When this approach does not work for you
Crowdfunded real estate is not suitable if you need access to your money within two years. It is also poorly suited for investors who want to actively manage their properties or make decisions about tenants, renovations, or sales. You have zero control over the asset. Your only recourse is voting rights on major decisions like selling the property early, and even those are limited. If you prefer direct ownership where you can fix problems yourself, buying a single room in a rental building through a traditional mortgage or outright purchase will give you more flexibility and likely better long-term returns after you factor in the time you save not dealing with platform disputes. I have also seen deals collapse when the sponsor disappeared with funds before construction began. This is rare but it has happened on at least two platforms that operated without proper escrow arrangements. An escrow account means the money sits in a bank account controlled by a third party and only releases to the sponsor as construction milestones are met and independently verified. Always ask whether your platform uses escrow. If they do not, treat that as a red flag equivalent to a missing title deed. The tax filing season for crowdfunding returns in Kenya runs from January through June of the following year. You will need to declare your rental income and any capital gains on your iTax portal. Platforms should provide annual summaries, but I have found errors in three separate reports across two different platforms. Double-check every figure before filing. The KRA does not accept platform summaries as final authority — the responsibility for accuracy falls on you.
If you are new to this, start with a single small investment on one of the more established platforms that uses escrow and provides monthly construction updates. Do not diversify across five different projects in your first year. You need to understand how the system works before you commit significant capital. My first two deals taught me more about risk assessment than any amount of reading prepared me for. The third deal was where I started applying those lessons properly and the returns reflected that difference.