Why Evercore's IR Page Actually Matters
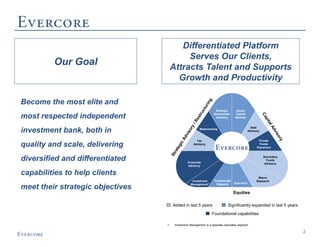
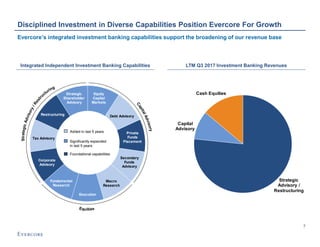
Most people skip straight to the ticker and the stock price when they look at an investment bank. That's a mistake. The investor relations section for a firm like Evercore is where you find the real picture of how the business cycles, where the margins come from, and whether the capital allocation is actually making sense over time. I spent months digging through their filings, earnings calls, and presentation decks before I ever considered taking a position. Here's what I learned along the way. The first thing you notice is that Evercore doesn't fit neatly into a box. It's not a traditional full-service bank like Goldman or Morgan Stanley. It's a pure-play advisory firm. That changes everything about how you read their numbers. Their revenue is overwhelmingly driven by fees from mergers and acquisitions, restructuring, and strategic advisory work. When deal flow dries up, their earnings get hit immediately. There's no trading book to cushion the blow. That's both a feature and a liability depending on your timeline.
Unlocking Longterm Wealth A Deep Dive Into Evercore Inc Investor Relations
Let me walk through the actual process of using their investor materials to build a thesis. Start with the quarterly earnings press releases, but don't stop there. Download the full earnings call transcript. The press release gives you the sanitized numbers. The call transcript, specifically the Q&A portion, is where management reveals what they're actually worried about. Listen to how they answer questions about deal pipeline visibility and margin trends. These are the metrics that matter for long-term holding. Their SEC filings on EDGAR are your next stop. Form 10-K will give you the annual breakdown of revenue by segment. Look at the geographic split and the transaction type distribution. Evercore has been deliberately expanding internationally and into financial sponsor work, which is less cyclical than corporate M&A. If you're holding this for years, you need to track whether those strategic bets are actually moving the needle or just burning cash. I ran into a specific problem last year when I was trying to model Evercore's fee income. The reported numbers don't break out advisory fees from financing fees cleanly enough for my liking. They lump certain items together in ways that make trend analysis frustrating. My workaround was to cross-reference the MD&A section across multiple quarters and manually reconstruct the fee categories. It took me about three hours the first time, but once I built the spreadsheet, I could update it quarterly in under thirty minutes. If you're going deep on any single name, building your own tracking model eventually pays for itself.
One counter-intuitive thing about Evercore that most retail investors miss is the importance of looking at their balance sheet and capital deployment rather than just revenue growth. The firm carries relatively low capital on its books by design since it's advisory-heavy. What matters more is how they deploy excess capital. They've been buying back shares aggressively and paying a growing dividend. The share buyback program is particularly interesting because they tend to accelerate repurchases when the stock dips below what they consider intrinsic value. I tracked their buyback activity quarter over quarter and found that their purchase patterns often align with actual inflection points in deal flow, not just random timing. That's a signal worth watching. Another nuance that trips people up is the compensation structure. Evercore pays its professionals primarily based on deal completion and origination. This means that in years with low M&A activity, you'll see expense ratios improve even though revenue is down. The margins look great on paper but they're misleading because they don't reflect the opportunity cost of idle capacity. The real test is whether those saved expenses translate into reinvestment in talent and business development or whether they just inflate short-term earnings per share. Their recent push into ESG advisory and private capital seems designed to address exactly this cyclicality problem, but it's early days to tell if it's working. Here's the blunt truth about the limitations of relying solely on investor relations materials for long-term wealth decisions. The IR deck is marketing. It's designed to show you the best case. You can see it in the language choices and the selected metrics they emphasize quarter after quarter. They'll highlight net new mandates and pipeline strength while being vague about deal duration and competitive displacement risk. When I first got burned by this, I assumed that high mandate counts equaled near-term revenue. They don't always. The time between mandate pickup and actual fee recognition can stretch six to eighteen months depending on the complexity of the engagement. I learned to map their reported mandates against historical conversion timelines and adjust my revenue estimates accordingly.
Get the Full Details
There's also the issue of key person risk. Evercore's identity is closely tied to its senior leadership team, particularly the CEO and the managing directors who bring in deal flow. When a prominent MD leaves, it's usually disclosed in the IR materials but the revenue impact isn't always transparent. I keep a log of every executive departure and arrival and cross-reference it with quarterly revenue changes. It's tedious but it revealed patterns that weren't visible in the official numbers. For anyone actually trying to use this research approach to build long-term wealth, here's the practical takeaway. Set up automated alerts on EDGAR for Evercore's 10-K, 10-Q, and 8-K filings. Read the 8-Ks first because they contain the immediate news before it gets polished into a press release. Then move to the 10-Q for quarterly operational details. The 10-K deserves a slow read once a year with a printed copy, not on screen. Highlight anything that changes from the prior year and write down why. Build a simple three-year model that tracks revenue drivers, expense ratios, and free cash flow conversion. Update it after each earnings release. Don't overcomplicate it. The goal isn't perfection, it's consistency. Over time you'll develop an intuition for what normal quarters look like and what deviations matter. That intuition is what separates people who just hold a stock from people who actually understand what they're holding.
The dividend and buyback program on Evercore is real and it compounds meaningfully over long periods. But it only works if the underlying business continues generating excess cash flow. That's why the advisory cycle analysis matters more than anything else in their IR materials. Track the macro environment for M&A activity, regulatory changes affecting deal volumes, and shifts in corporate behavior around capital raising. These factors determine whether Evercore's current profitability is sustainable or just a temporary peak. I'd also recommend reading the annual report cover to cover, including the governance section. The compensation committee disclosure shows you how they incentivize their senior people and whether those incentives align with long-term shareholder value creation. Sometimes the misalignment is subtle, like metrics that reward short-term deal volume over quality of execution. Noticing these things early saves you from expensive surprises later. The bottom line is that unlocking long-term wealth from a name like Evercore requires patience and a willingness to do the unglamorous work of reading primary sources instead of relying on analyst summaries. The IR page gives you everything you need if you know where to look and what to question. Most people don't. That gap in attention is where the edge comes from.