International Payment Gateways Are Not as Smooth as Vendors Claim
I have spent years watching businesses try to set up cross-border payments and then hit wall after wall. Currency conversion fees that make no sense. Settlement times that stretch to five business days. Chargebacks that get stuck in some middleman limbo. A recent example of the kind of infrastructure people are looking at now is Unlocking Global Commerce How Wwwgatewaygago Is Redefining International Payment Systems, which is a gateway focused on reducing the friction points that usually show up when you accept payments from outside your home country. The basic premise is straightforward. You create an account, add your merchant credentials, integrate the API or use a hosted checkout, and suddenly your customers in different countries can pay in their own currency while you receive settlement in the currency you choose. It sounds simple enough. The reality of integrating any payment gateway is almost never that clean.
Unlocking Global Commerce How Wwwgatewaygago Is Redefining International Payment Systems
Here is how the integration actually works in practice, based on setting this up for clients and on my own infrastructure. Step one is selecting your target markets and mapping the payment methods that matter in each one. In Southeast Asia, card payments account for maybe forty percent of transactions. The rest comes through digital wallets like GoPay, OVO, and DANA. If you only enable cards, you are leaving revenue on the table. In Latin America, BOLETO Bancário and PSE are essential. In Europe, SEPA direct debit and local card schemes dominate. A gateway that offers multi-method support out of the box saves you from stitching together three or four different providers later. Step two involves the API integration itself. Most modern gateways provide SDKs for JavaScript, Python, PHP, and REST endpoints. You will want to use server-side integration for handling sensitive payment data rather than putting everything client-side. Store the payment method token on your server. Do not touch the actual card number or account credentials in your own database. The gateway handles that compliance burden. If your team is building a custom checkout flow, the gateway should provide a test mode with sandbox credentials so you can validate every failure case before going live.
Step three is configuring your settlement and currency rules. This is where most people make mistakes. You need to decide whether to settle in your home currency or in the local currency of each transaction. Settling locally means the customer pays in their currency and you receive in that same currency, which reduces currency conversion friction for them but exposes you to exchange rate risk if you do not hedge. Settling in your home currency means the gateway converts the money at their rate, which is convenient but the exchange margin can eat two to three percent off each transaction. I learned this the hard way with a client who was making fifty thousand dollars a month in Brazilian reais and settling into USD without realizing the conversion spread was costing them nearly eight hundred dollars monthly. Switching to USD-only settlement with a forward contract arrangement cut that cost in half. Step four is testing end-to-end before launching. Run test transactions through every payment method you plan to offer. Test successful payments, declined payments, insufficient funds, and expired cards. Verify that your webhook handlers fire correctly when a payment succeeds or fails. Webhooks are the mechanism the gateway uses to notify your server about asynchronous events. If your webhook endpoint times out or returns an error, the gateway will retry, but you need to idempotently handle those retries or you will double-charge customers. This is not theoretical. I have seen production systems duplicate refunds because the retry logic was missing a deduplication check. Step five is going live and monitoring closely for the first thirty days. Watch your authorization failure rates. If they jump above five percent, investigate immediately. Common causes include your IP address being flagged by the fraud engine, your domain lacking proper SSL configuration, or your transaction volumes triggering fraud filters unexpectedly. Most gateways have configurable risk thresholds. Set them appropriately for your business model before the first real transaction comes through.
Get the Full Details

What Actually Happens Behind the Scenes
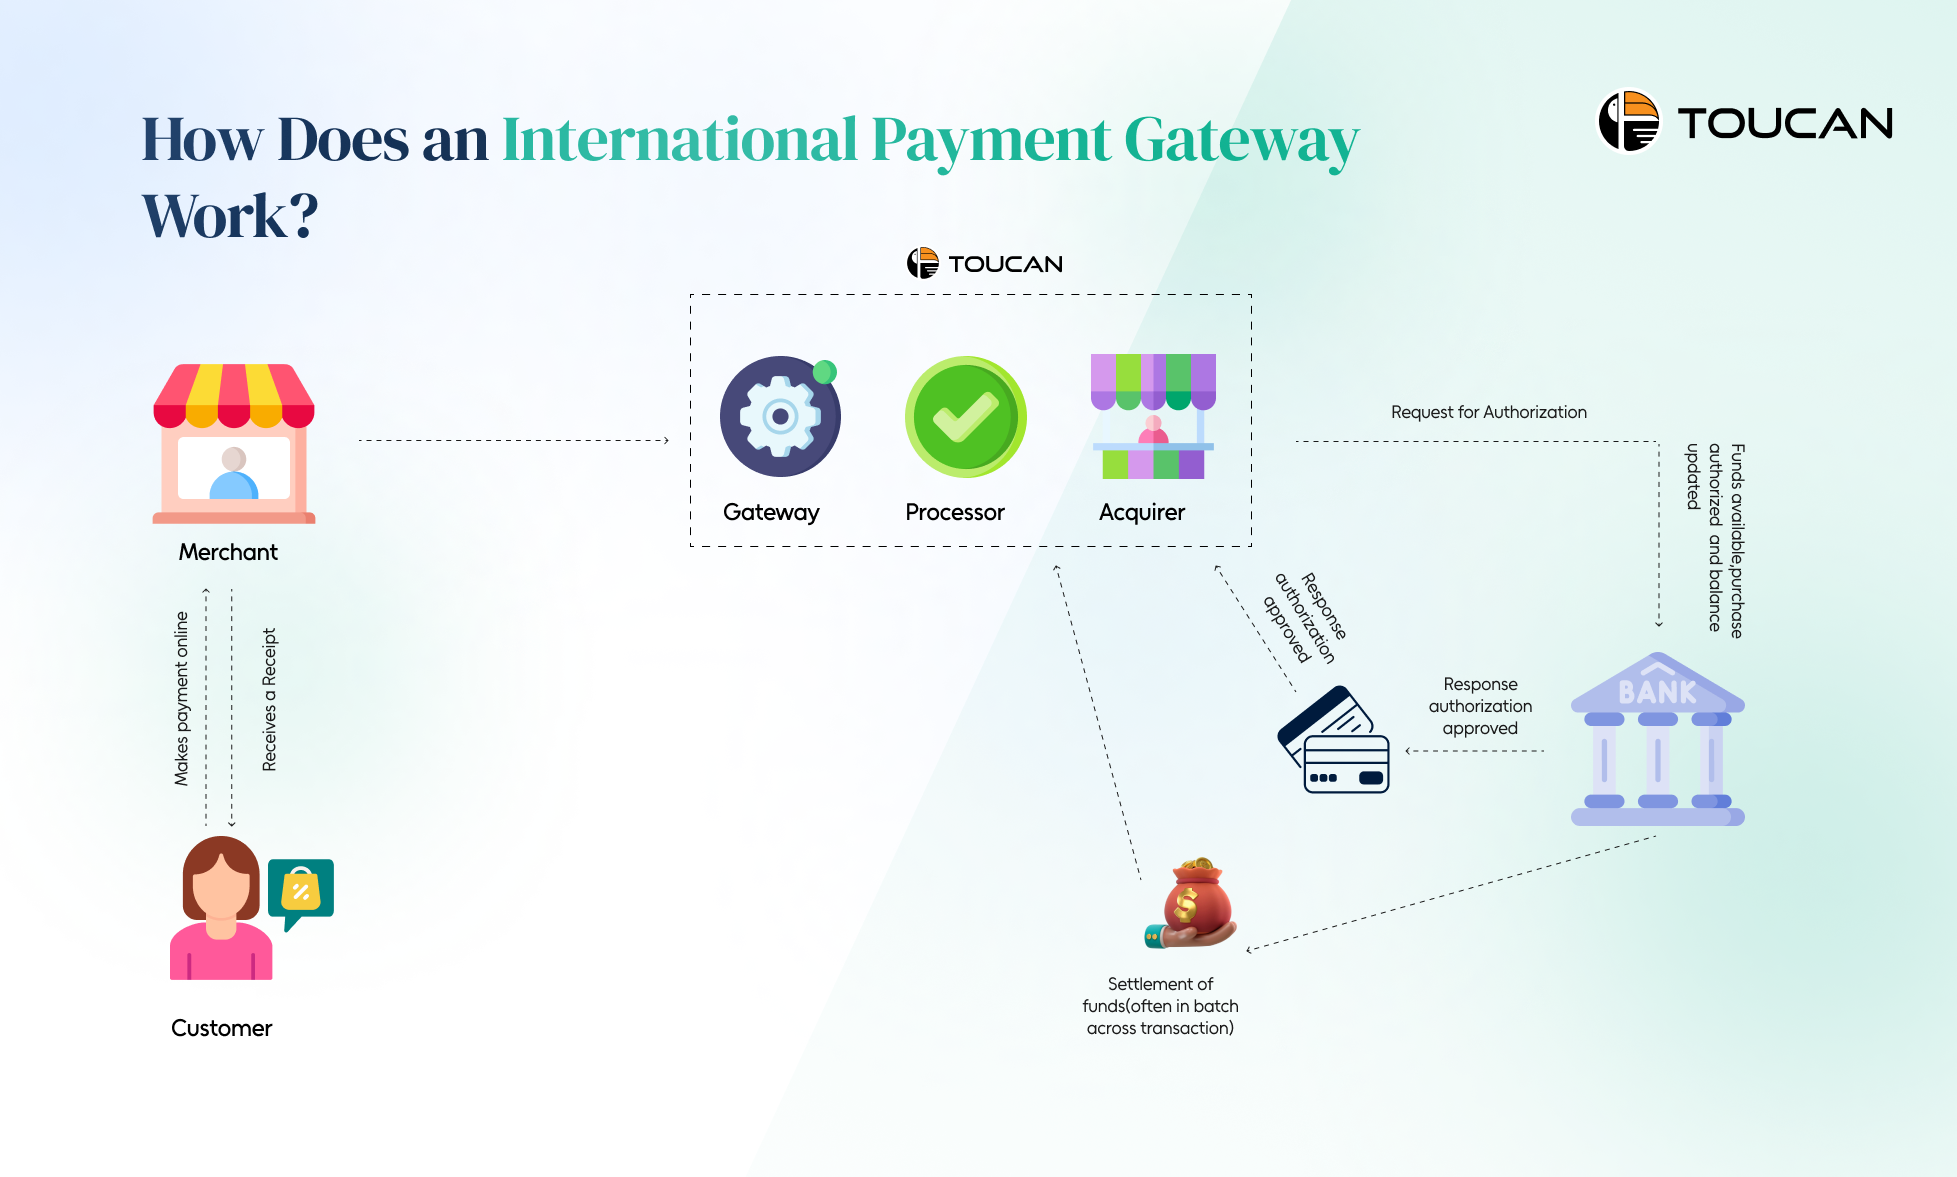
When a customer submits payment, the request travels from your checkout page to the gateway's API, which routes it through the appropriate card network or payment method processor, then to the issuing bank for authorization. The issuing bank either approves or declines, and that response flows back through the same chain. A successful authorization is not a completed payment. It becomes a capture when you finalize the transaction, which may happen immediately at checkout or later when you fulfill the order. The difference between authorization and capture matters for fraud prevention and for managing your cash flow. Settlement typically occurs within one to three business days for major markets, though some regions and payment methods take longer. Indonesia, for example, can have settlement timelines that extend to five days depending on the acquirer and the specific payment channel. This is important for your accounting and for planning your working capital. Fraud screening is another area where the quality of the gateway matters enormously. Basic gateways offer nothing beyond a binary approve or decline. Better ones integrate scoring engines that evaluate device fingerprinting, velocity checks, geolocation mismatches, and known fraud patterns. The best ones allow you to create custom rules that match your specific risk profile. A gateway like Gateway Gago positions itself somewhere in this spectrum, and the value you get depends on how aggressively you configure those fraud tools.
Common Pitfalls That Cost Businesses Money
Pitfall one is ignoring local compliance requirements. Different countries have different regulations around payment data, consumer protection, and tax reporting. The European Union requires Strong Customer Authentication under PSD2. Brazil has its own centralized payment system regulations. China has strict rules around cross-border payment processing. If you are targeting multiple regions, you need to understand which regulations apply to your business and ensure your gateway partner can help you stay compliant. Some gateways handle this automatically. Others expect you to figure it out yourself. Pitfall two is underestimating chargeback management. Chargebacks happen. The question is how you handle them. A good gateway provides a dashboard where you can view, respond to, and track chargebacks. It should also give you access to chargeback reason codes so you can identify patterns. I once worked with a merchant who was losing fifteen percent of revenue to chargebacks because they had no process for responding to disputes within the required timeframe. The gateway allowed responses, but nobody on the team knew they could fight them. Implementing a simple chargeback monitoring routine cut their losses by sixty percent in the first quarter. Pitfall three is assuming one gateway fits all use cases. If your business model involves recurring billing, subscriptions, or marketplace payouts, the standard checkout flow may not work. You need a gateway that supports these transaction types natively or through well-documented APIs. Some gateways charge significantly higher fees for subscription processing. Others cap the number of subscriptions per account unless you negotiate a custom rate. Read the pricing documentation carefully before committing.
The Limitations Nobody Talks About
No payment gateway solves every problem. Gateway Gago, like any platform in this space, has constraints. High-risk industries such as gambling, adult entertainment, and cryptocurrency face restrictions or outright bans on many platforms. Some countries remain unsupported due to regulatory complexity. Very small transaction values can be uneconomical when processing fees exceed a certain threshold. And no matter how good the integration documentation claims to be, you will encounter edge cases that are poorly documented or simply undocumented. There is also the question of vendor lock-in. Migrating away from a payment gateway is not trivial. Your customer data, transaction history, and reconciliation reports are tied to that platform. Switching costs are real. This means choosing your gateway should be treated as a strategic decision, not just a technical setup task. If your volume is very large, you should negotiate directly with the provider rather than accepting standard published rates. Gateway pricing is rarely fixed. The published fees are starting points. A business processing over a million dollars monthly can usually secure meaningful discounts on interchange-plus pricing, lower chargeback fees, and priority support channels.
Practical Recommendations
Start with a clear picture of your target markets and the payment methods your customers expect. Build a comparison matrix of at least three gateways, weighing integration complexity, supported methods, settlement timelines, fraud tools, and total cost including hidden fees. Test everything in sandbox before touching production. Monitor your first month of live transactions like a hawk. Set up alerts for abnormal failure rates or unexpected drops in authorization rates. Keep your webhook handlers idempotent. Store gateway-provided tokens rather than raw payment data. Maintain thorough transaction logs for reconciliation. Review your fraud and chargeback metrics weekly during the first ninety days. Do not ignore the small anomalies because they often point to larger systemic issues down the line. The international payment space is crowded and the vendors all sound similar in their marketing materials. The real differences show up during integration, during a fraud spike at two in the morning, and during month-end reconciliation when you discover a fee you did not expect. Pick a gateway that gives you visibility into all of those areas, not just the ones that look good on a sales page.