Setting Up Your CVS 401K Match Is Not As Easy As It Should Be
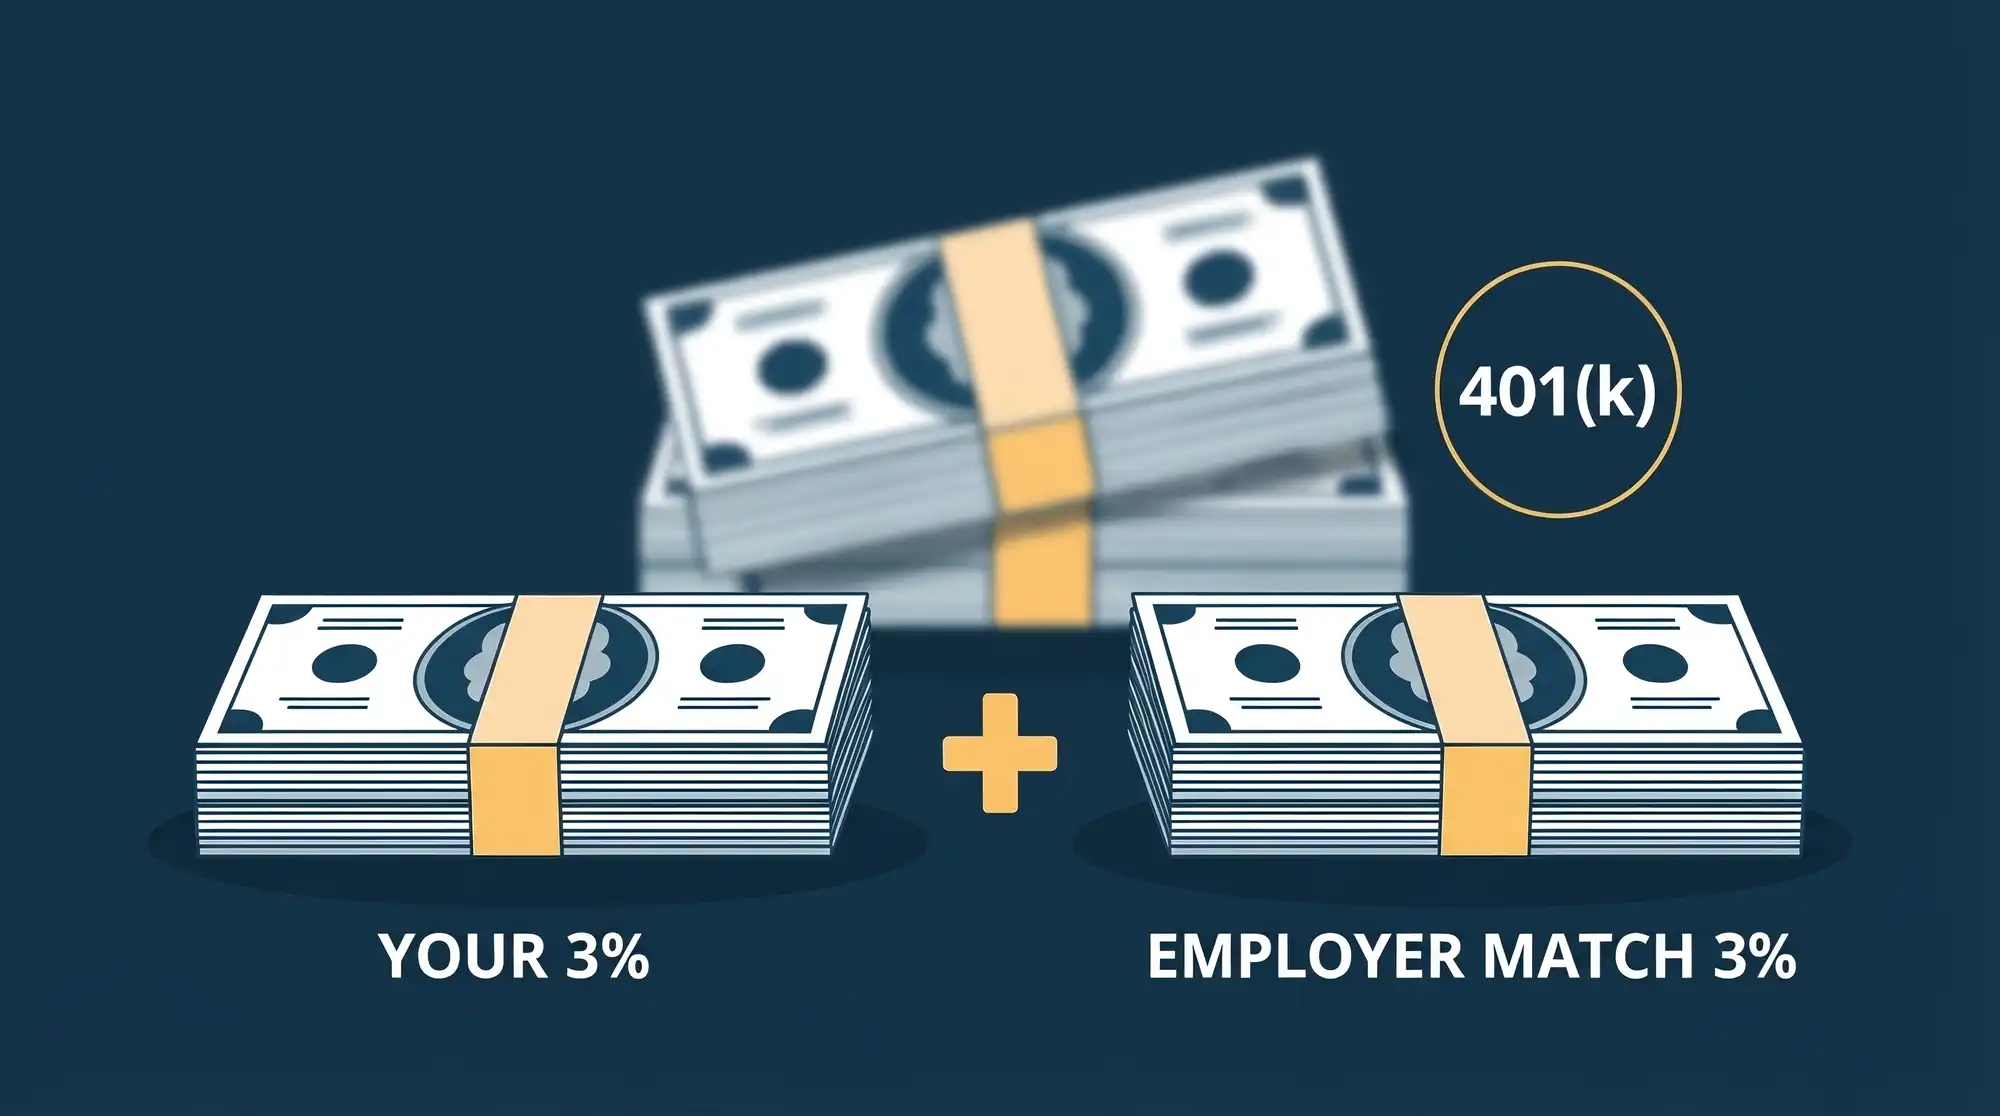
Most people find out about their employer match after they have already missed a quarter of free money. I learned this the hard way when I changed jobs and immediately dropped my contribution from 8% to 4% because I misread the vesting schedule on my old plan. That cost me roughly $1,200 in a single year. CVS Healthcare has a pretty standard but slightly tricky match structure that most employees walk past without understanding. The basic mechanism is straightforward. CVS matches a percentage of your salary contributions up to a certain limit. The current typical structure is a dollar-for-dollar match on the first 4% of your compensation that you contribute, and then a half-dollar match on the next 2%. That means if you contribute 6% of your paycheck, CVS is putting in the equivalent of 5% on top. If you contribute less than 4%, you are leaving money on the table. This is not theory. It is the actual formula. The catch is that CVS is moving toward a new retirement plan design. They acquired Aetna and have been integrating several different plan documents from acquired companies. If you work for a legacy Aetna division or a CVS pharmacy location that was formerly something else, your plan specifics could differ. Check your actual plan summary, not what a coworker says theirs is.
The Vesting Schedule Will Bite You
Employee contributions are always 100% vested immediately. Employer match contributions are not. CVS uses a graded vesting schedule. You become 20% vested after two years of service, then an additional 20% each year until you hit 100% at six years. If you leave before six years, you walk away with a portion of the employer match. This matters more than most people realize. I had a colleague who resigned after four years and lost roughly 40% of his accumulated match. That was about $8,000 at his salary level. If you are planning to move within two years, do not bother contributing enough to capture the full match. The vesting math works against you. Contribute just enough to get what you will actually keep. After two years it becomes worth optimizing fully.
How To Actually Get The Match
You need to log into the CVS benefits portal or the 401K platform they use, which has shifted over the years between Fidelity and other providers. Go to your contribution settings and set your deferral percentage to at least 6%. Some people go higher because there is no penalty for over-contributing relative to the match. The match tops out at 6% of salary regardless. Contributing 10% means you are getting the full match plus saving more for yourself, which is the smarter move if your budget allows it. Here is an edge case that almost nobody catches: CVS's match is calculated on base salary, not on overtime or bonus pay. If you are a pharmacy tech working a lot of overtime, your match will be based on your lower base rate. This quietly reduces the actual dollar value of the match by 15-25% compared to what the brochures imply. I ran the numbers for a friend who was making $45,000 base plus $8,000 in annual overtime. Her match was calculated on $45,000 instead of her actual $53,000 earnings. She was getting $2,700 in match instead of the $3,180 she would have received on her total comp. She updated her HR department but could not retroactively claim the difference for prior years.
Get the Full Details

The Catch-All Rule That Nobody Talks About
The IRS imposes an annual deferral limit. For 2025 it is $23,000 for employees under 50 and $30,500 if you are 50 or older with a catch-up contribution. CVS, like most large employers, has to test their plan annually for ADP compliance. If highly compensated employees contribute disproportionately compared to the general workforce, CVS could be forced to refund those contributions. This is extremely rare at CVS because they have a massive non-benefited hourly workforce that skews the average downward, but it is something that happens at smaller companies and could theoretically affect you. If you are making over $130,000 and your plan administrator contacts you about excess deferrals, it means the ADP test triggered a refund. It is an inconvenience, not a disaster, but it will show up as a surprise adjustment on your W-2. The most counter-intuitive thing about the CVS 401K match is that it is not actually free money in the way people think. The match is funded from pre-tax dollars, which means your taxable income drops. The benefit is real but you are trading current take-home pay for future value. A second missed detail: CVS offers a Roth 401K option now. If you expect your tax rate to be higher in retirement than it is today, converting your contributions to Roth means the match money grows tax-free. I switched half my contributions to Roth about three years ago and have not looked back. The match on the Roth side is still fully vested according to the same schedule. You get the same employer contribution whether it is traditional pre-tax or Roth. Another thing nobody mentions is that the match is deposited on a different schedule than your own contributions. Your paycheck deductions happen every pay period. The employer match may be deposited monthly, quarterly, or only at certain contribution windows depending on your specific plan year. I found out the hard way that CVS processes match contributions on a quarterly lag. If you increase your contribution mid-quarter, you do not start seeing the higher match until the next quarter's deposit. This means your effective annualized return on those contributions is lower than it appears if you are constantly changing your rate.
The practical takeaway is to set your contribution and forget about it. Every time you adjust your deferral percentage, you are resetting the clock on when that change takes effect for match purposes. I stopped tweaking mine about eighteen months ago and just let it compound. The simplicity paid off.
When The Match Does Not Help You
There are scenarios where optimizing for the CVS match is the wrong priority. If you have credit card debt above 15% interest, pay that off first. A 5% employer match is a guaranteed return, but a 20% credit card APR is a guaranteed loss that dwarfs it. If you have an IRA available to you, maxing a Roth IRA before going above 6% in the 401K can be the better move because of the broader investment options and no ADP testing risk. CVS does not match IRA contributions, obviously. The 401K match should be treated as the foundation, not the ceiling. One final note about accessing this money. Withdrawals before age 59½ from a 401K incur a 10% penalty on top of ordinary income tax. This applies to the match too. There are exceptions for hardship, disability, and a few other narrow categories, but CVS follows the standard IRS rules here. Do not touch this money unless you have a specific reason that outweighs the double penalty. I have seen people drain their 401K for car repairs and house down payments and regret it because the compounding they gave up was far more valuable than the liquidity they gained.