OCBC NISP Indonesia Banking Services: What Actually Matters
I opened my first OCBC NISP account back in 2018 when I was still getting comfortable managing multiple banking relationships in Indonesia. Like most people, I signed up because of the app interface and the reputation. What I didn't expect was how fragmented the experience would become over time. The gap between what their marketing materials promise and what the platform actually delivers is where people get tripped up. The core issue most users face isn't finding information about OCBC NISP services. It's knowing which features actually matter versus which ones are noise. Let me walk through what works, what doesn't, and the workaround I ended up using after three years of frustration.
Unlocking Financial Freedom With Ocbc Nisp Indonesia Your Guide To Banking Services
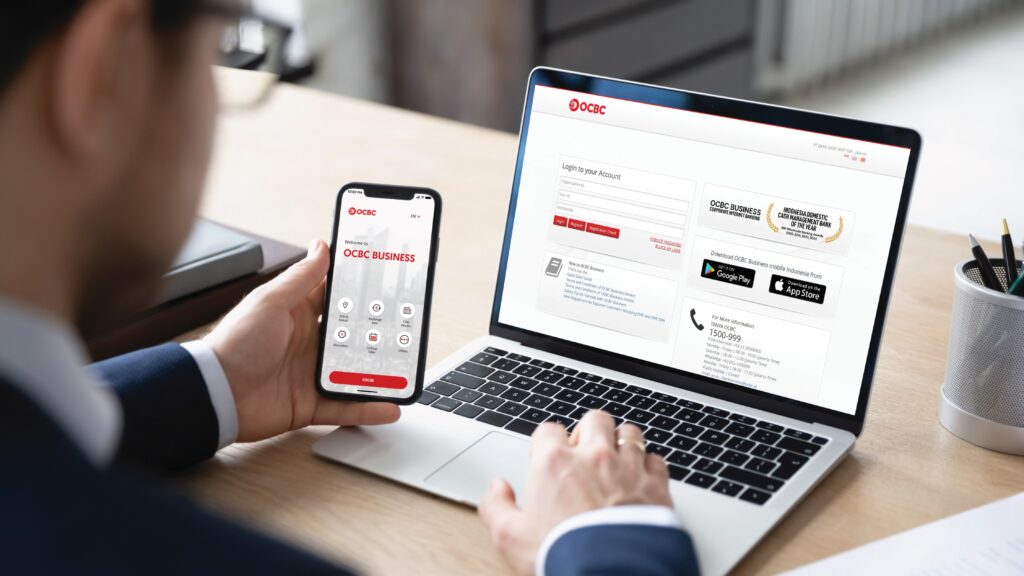
The onboarding process for OCBC NISP takes about twenty minutes if your documentation is clean. You need your KTP, NPWP, a proof of address (some branches accept a utility bill from the last three months), and a minimum opening deposit of IDR 500,000 for their Taplus account. The app download is straightforward - available on both Google Play Store and Apple App Store. I've seen people waste hours trying to verify through the wrong channel. Register directly through the official OCBC NISP application. Third-party links have caused problems for clients I know. Once your account is active, the real question becomes what you actually do with it. OCBC NISP positions itself as a full-service digital bank but the reality is more nuanced. Their mobile platform handles the everyday stuff competently - balance checks, transfers, bill payments, and savings management. That part works well. Where it gets complicated is with products that require human intervention or documentation that the digital system doesn't fully support. Take credit cards for example. OCBC NISP's credit card application process through the app is clean but the approval rates can be unpredictable. I personally hit a wall when applying for a business credit card because my NPWP classification didn't match what their system expected. The workaround was simple but not obvious - I visited a branch in South Jakarta and spoke to a relationship manager who manually overrode the classification mismatch. Took about forty-five minutes. Without that visit, the application would have been stuck in limbo for weeks.
Their savings products deserve a closer look. The Taplus account offers competitive rates for Indonesian banks but the terms shift frequently. Right now they're offering around 3.5 to 4 percent annually on savings, which is solid for a retail account. But here's what most guides don't mention - the rate is tiered. Anything above IDR 50 million in balance gets a different calculation. If you're managing larger deposits, you need to understand how the tiering works before committing funds. Some people discovered this the hard way after moving money in bulk expecting a flat rate.
Get the Full Details
Common Pitfalls People Miss
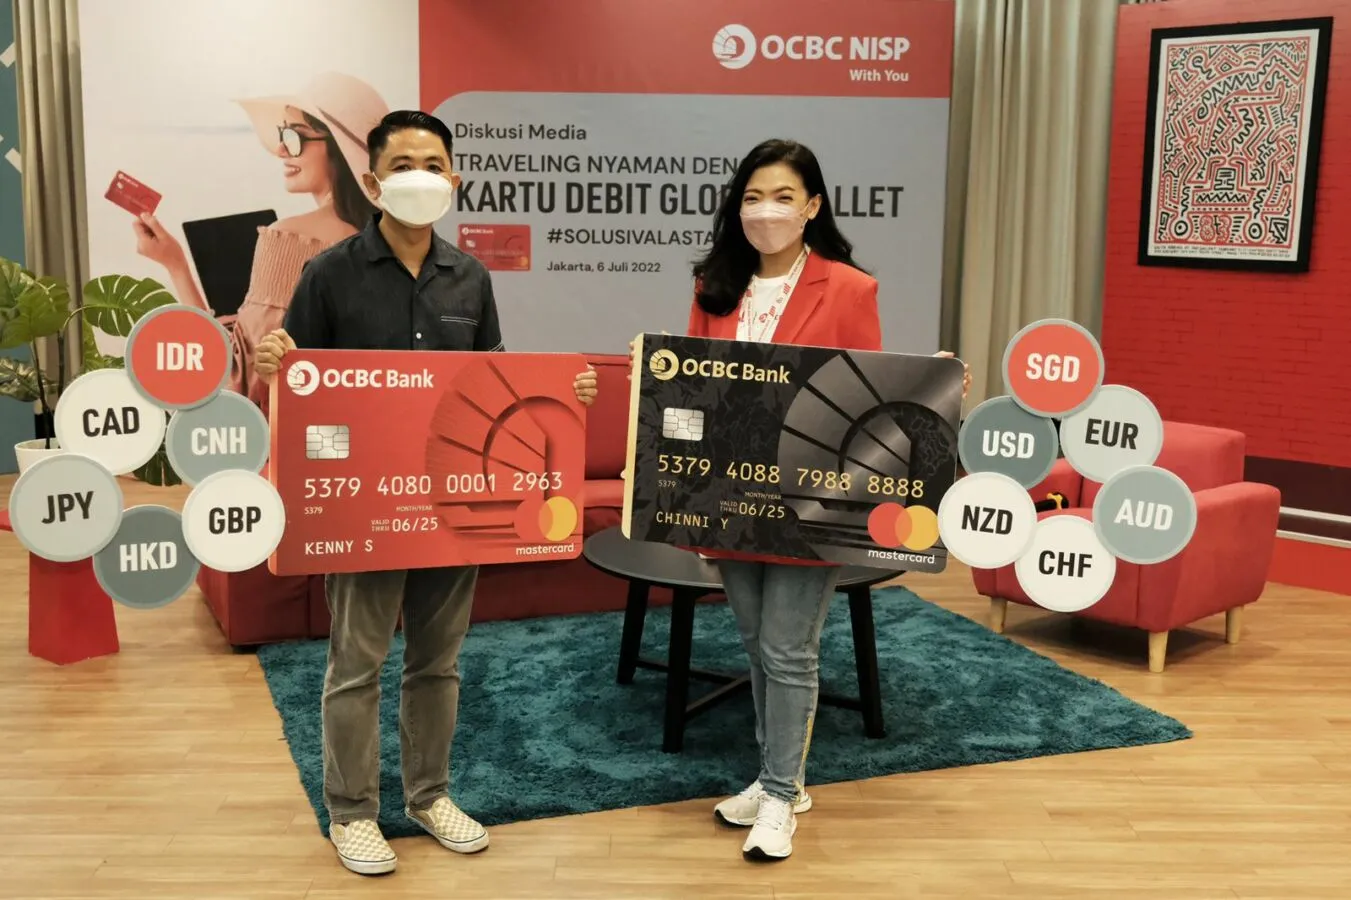
OCBC NISP's transfer limits are set per transaction and per day. The default limits for new accounts are relatively conservative - usually around IDR 25 million per transaction and IDR 50 million daily. These limits increase automatically over the first six months as your account history builds, but there's a manual pathway too. You can request a limit increase through the app by submitting a letter of intent. It typically processes within one to two business days. I've had clients who didn't know about this and got caught when trying to make a large payment for something like property down payments or equipment purchases. Another overlooked detail is the foreign currency handling. OCBC NISP supports multi-currency accounts but the exchange rates they offer are standard bank retail rates, not interbank rates. If you're moving money internationally or managing overseas expenses regularly, this spread matters. I found that pairing an OCBC NISP account with a separate multi-currency platform like Wise or Revolut for international transfers reduced my costs significantly. The OCBC account stayed useful for local transactions and domestic savings while the other handled cross-border movements. The customer service experience is mixed. Phone support during business hours is passable but wait times vary wildly. I once spent fifty minutes on hold during a Tuesday afternoon trying to resolve a billing discrepancy on a debit card. Chat support through the app is faster but not all agents have the authority to resolve certain issues. When they can't help, you get escalated to a supervisor call which can add another day to the resolution. Document everything during these conversations. Screenshots, reference numbers, agent names. It saves time when you have to follow up.
What the Platform Actually Delivers
OCBC NISP's mobile app has improved noticeably over the past two years. The interface is cleaner, transaction history loads faster, and the budgeting tools inside the app are functional if basic. They're not going to replace a dedicated personal finance tool but they work for tracking day-to-day spending patterns. Their investment products section connects to OCBC's broader wealth management offerings in Indonesia. You can access mutual funds and deposit certificates through the app. The fund selection is narrower than what you'd find through independent brokers but the convenience factor is real. For someone who doesn't want to manage multiple platforms, having investments accessible from the same app as your checking account reduces friction. Here's the practical thing nobody tells you - OCBC NISP's integration with GoPay and other Indonesian e-wallets is seamless. Loading money from your OCBC account into GoPay or OVO happens instantly. For daily transactions in Indonesia where QRIS payments dominate, this integration makes the account far more usable than it appears on paper. I transferred my primary spending account to OCBC NISP specifically for this reason after getting tired of maintaining separate accounts for different payment methods.
Loan applications through the platform work for smaller amounts. Personal loans up to a certain threshold process entirely online with decisions in under an hour. I used this feature for a short-term cash flow need and the approval came through quickly. Larger loans or business financing require branch visits and extensive documentation regardless of what the app suggests. Don't assume the digital promise applies uniformly across all product categories.

When OCBC NISP Is the Right Choice
This bank works well if you're looking for a reliable domestic Indonesian banking relationship with a modern app and don't need sophisticated international banking features. The customer base that benefits most are people who primarily transact in rupiah, want a single app for everyday banking, and value the OCBC brand stability in the region. If you need frequent international wire transfers or complex investment structures, you'll likely find the experience limiting. Opening an account is accessible. Most branches operate from eight in the morning until four in the afternoon on weekdays. Weekend hours vary by location. Bring your original documents as photocopies alone won't be accepted. New account setup can sometimes be completed during a single branch visit if all documentation is in order. The digital ecosystem around OCBC NISP in Indonesia continues evolving. Their recent partnerships with local fintech companies have expanded what's possible without leaving their app. Whether this direction addresses the gaps I mentioned earlier remains to be seen. For now, the account serves a specific use case well. Understanding that use case before committing is what separates people who recommend the bank from those who don't.
If you're currently using OCBC NISP and hitting friction points with limits, foreign currency, or service escalations, the branch relationship manager route is worth pursuing. The app can only take you so far and the people at the branches have context that the automated systems lack. I learned that distinction the hard way and it changed how I use the account going forward.