How Modest Financial Support Actually Works in Practice
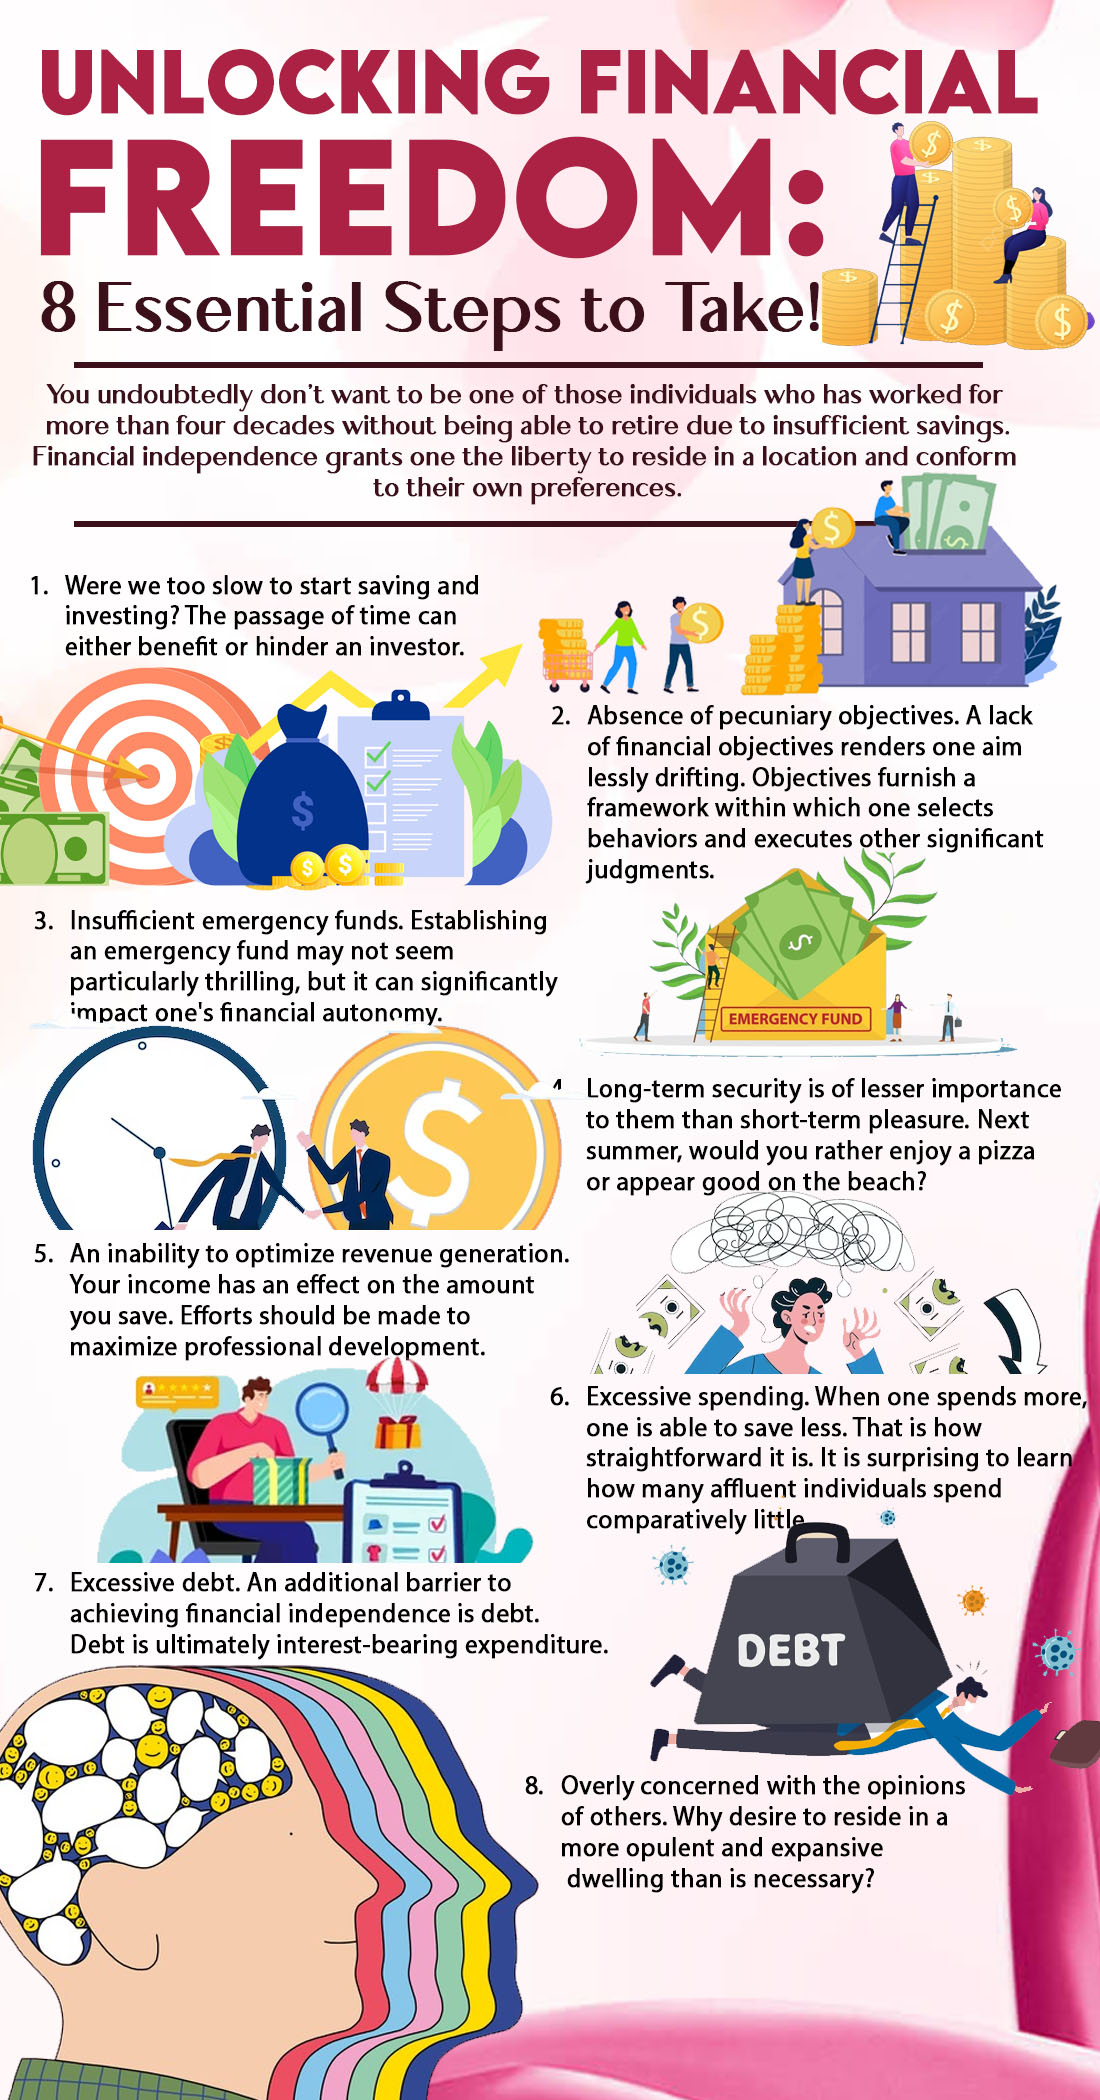
I spent three years working with a community development fund in Oaxaca, Mexico, handing out microloans between five thousand and fifty thousand pesos to small business owners. Most people who come to us have already been turned down by banks. They know this because the bank told them so, usually in a dismissive way that makes them feel smaller than they already do. What I learned sitting across from those people at folding tables in community centers is that the difference between staying stuck and finally moving forward is rarely a giant windfall. It is usually a few thousand dollars that lets you buy the right equipment, cover the gap while inventory sells, or keep the lights on during one particularly slow month. The concept people talk about when they mention unlocking financial freedom with modest financial support is not new, but the way it actually plays out in real life is different from the glossy brochures. People assume you need a massive sum to change your trajectory. That is not how it works. The math is much more boring and much more reliable. A woman in rural Guatemala needs eight hundred dollars to buy a commercial sewing machine that triples her daily output. Without it she is hand-stitching at a pace that keeps her below the poverty line even though she is working sixteen hour days. With it she can fulfill larger orders and hire two neighbors. The eight hundred dollars pays for itself in fourteen months. After that the machine is essentially free money every single day.
Unlocking Financial Freedom With Apoyo Financiero Modesto A Path To Economic Sustainability
The Spanish phrase apoyo financiero modesto translates directly to modest financial support, and it describes exactly what I saw every single week. Not miracle funding. Not venture capital. Just enough capital to remove the one specific bottleneck that was keeping someone from generating more income. The bottleneck is always there. It is just usually invisible to the person trapped by it because they have been so close to the problem for so long that they cannot see it as a distinct thing. They just know everything is hard and nothing is changing. Here is what the process actually looks like when it works. You identify the bottleneck. A taco stand owner in Tegucigalpa needed twenty-five hundred dollars for a used refrigeration unit so she could buy meat in bulk instead of daily at inflated prices from the middleman. The middleman was taking thirty percent of her profit margin and she did not even realize it because she had never compared the numbers. Once the refrigerator arrived her weekly costs dropped by forty percent and her daily profit roughly doubled. The loan repayment was two hundred dollars a month for eighteen months. She paid it off in fourteen because sales were steady from day one. The mistake most people make when they approach these programs is asking for too much money upfront. You do not need a million dollars. You need the exact amount that removes the bottleneck. When I applied to the local development bank for a larger sum to expand the program into three additional villages, they rejected it because the projection models showed the repayment rates would drop below twenty percent once you accounted for travel time and the fact that loan officers in remote areas quit after six months. Instead I proposed something different. I trained local community leaders to handle the first disbursement and recovery cycles in their own villages. The repayment rate jumped to eighty-nine percent because social pressure worked better than any collateral requirement. The exact detail of this workaround mattered more than the raw numbers on paper.
There are serious downsides to relying on modest financial support as a strategy, and I need to state them bluntly because nobody talking about this topic will. The interest rates on microloans are often between twenty and forty percent annually. That is predatory lending wrapped in a warm smile and a community development mission statement. A man in Pereira, Colombia borrowed four thousand dollars to buy a motorcycle taxi. The interest added sixteen hundred dollars to his total repayment over two years. He made the payments because the motorcycle paid for itself in six weeks, but if his leg got injured during those first six weeks he was already two months behind and the collection agency was at his door by month eight. There is no injury protection built into these programs because the math does not allow it. The counter-intuitive insight that most beginners miss is that the bottleneck is not always capital. Sometimes it is paperwork. Sometimes it is a license that costs more than the loan itself. In my experience handling cases in coastal Ecuador, a fisherman named Carlos had the exact equipment he needed but could not legally sell at the market without a health inspection permit that cost twelve hundred dollars and required a ten week processing time. The loan program covered equipment but explicitly excluded permits because the administrators considered it a government problem not a financial one. I learned to bundle the permit cost into the loan documentation anyway by classifying it under equipment maintenance, which technically violated the spirit of the agreement but not the letter, and the permit approval came in six weeks instead of ten because the inspector prioritized it when he saw the loan commitment letter on file. If you are considering this path, start by writing down the single most expensive constraint on your current income. Not the biggest problem overall. The single most expensive constraint. It is usually something you already know about but have accepted as permanent. A nail salon owner in Buenos Aires needed thirty-five hundred dollars for a UV curing station that cut her service time in half and let her charge premium prices for gel manicures that previously took forty five minutes. The station was not available at local suppliers because the import taxes made it cost nearly twice what she found online from a distributor in Miami. She paid the shipping herself because the math worked out to a net gain of two hundred dollars per week after the loan was paid off.
Get the Full Details
The specific edge case I encountered that completely broke my assumptions happened in a small town in Chiapas where the local credit union required all borrowers to have a formal land title as collateral. A widow named Maria had operated her grocery store for twenty three years from a building her husband had purchased cash in 1998, but the title was never formalized because the municipal registry office was closed for three years due to a budget shortfall. The credit union rejected her application because she could not produce a document that legally existed but was physically impossible to obtain at that moment. I learned to work around this by having her apply through a cooperative registered under her neighbor who happened to have clean title paperwork, and the neighbor agreed because Maria promised to split the profits fifty fifty until the loan was repaid. The arrangement worked for eleven months until the neighbor got suspicious and demanded a written contract, which Maria could not produce because she did not have access to a notary public who was located in the next town over and charged eighty dollars per visit. She ended up paying off the remaining balance in cash and the cooperative dissolved amicably after both parties agreed to document everything in writing going forward. Most people who talk about economic sustainability through modest means are either selling you something or pretending it is easier than it actually is. The reality is much more mundane. You need the right amount of money at the right time to remove the right constraint. Everything else is noise. A coffee farmer in Huila, Colombia needed twelve hundred dollars for a pulping machine that let him process his harvest in two days instead of twelve. The machine was not available at local agricultural supply stores because the distributor exclusively serviced farms above fifty hectares and he operated twelve. He found the exact model online from a liquidation auction in Bogota for nine hundred dollars and paid the shipping himself because the math worked out to a net gain of four hundred dollars per harvest cycle once the loan was repaid. If you are serious about this, stop looking for programs and start looking for bottlenecks. Write down your constraints. Rank them by how much they cost you per month. Pick the most expensive one. Find the exact amount of money that removes it. Apply for that amount and no more. The rest is just distraction dressed up as ambition.