So You Want to Use Affirm for Everything
I ran into this when I was trying to consolidate some larger purchases across different vendors. Bought a washing machine, a few pieces of furniture, and a laptop over a six-week stretch. Standard practice would be to run each through a separate BNPL app or finance them one by one. That worked okay until I started tracking the monthly outflows and realized I had three different payment dates, three different portals, and a growing sense that I was managing debt instead of managing money. That is where the Affirm card becomes relevant. It is not a magic wand. It is a prepaid debit-style card that links directly to an active Affirm loan or to your available credit within the Affirm ecosystem. You load it, you swipe it, and at the end of the cycle your loan balance gets paid down. The interface is clean. The customer support is... adequate. The real question is whether it actually moves the needle on your financial situation.
Unlocking Financial Freedom The Power Of Affirm Card
Let me be direct about what that phrase actually means in practice. It does not mean you get free money. It means you gain predictability. When you structure your spending around a fixed repayment schedule instead of carrying a revolving balance with compounding interest, your cash flow becomes something you can model. I built a simple spreadsheet for one client who was spending about four thousand dollars a month on discretionary purchases. We mapped out which items could be split into three- or twelve-month installments using Affirm and which had to stay cash. The result was not a windfall. It was visibility. They stopped missing payments because the due dates were baked into their calendar rather than hidden inside a vague minimum-payment requirement. Here is the practical how-to part.
How the Affirm Card Actually Works
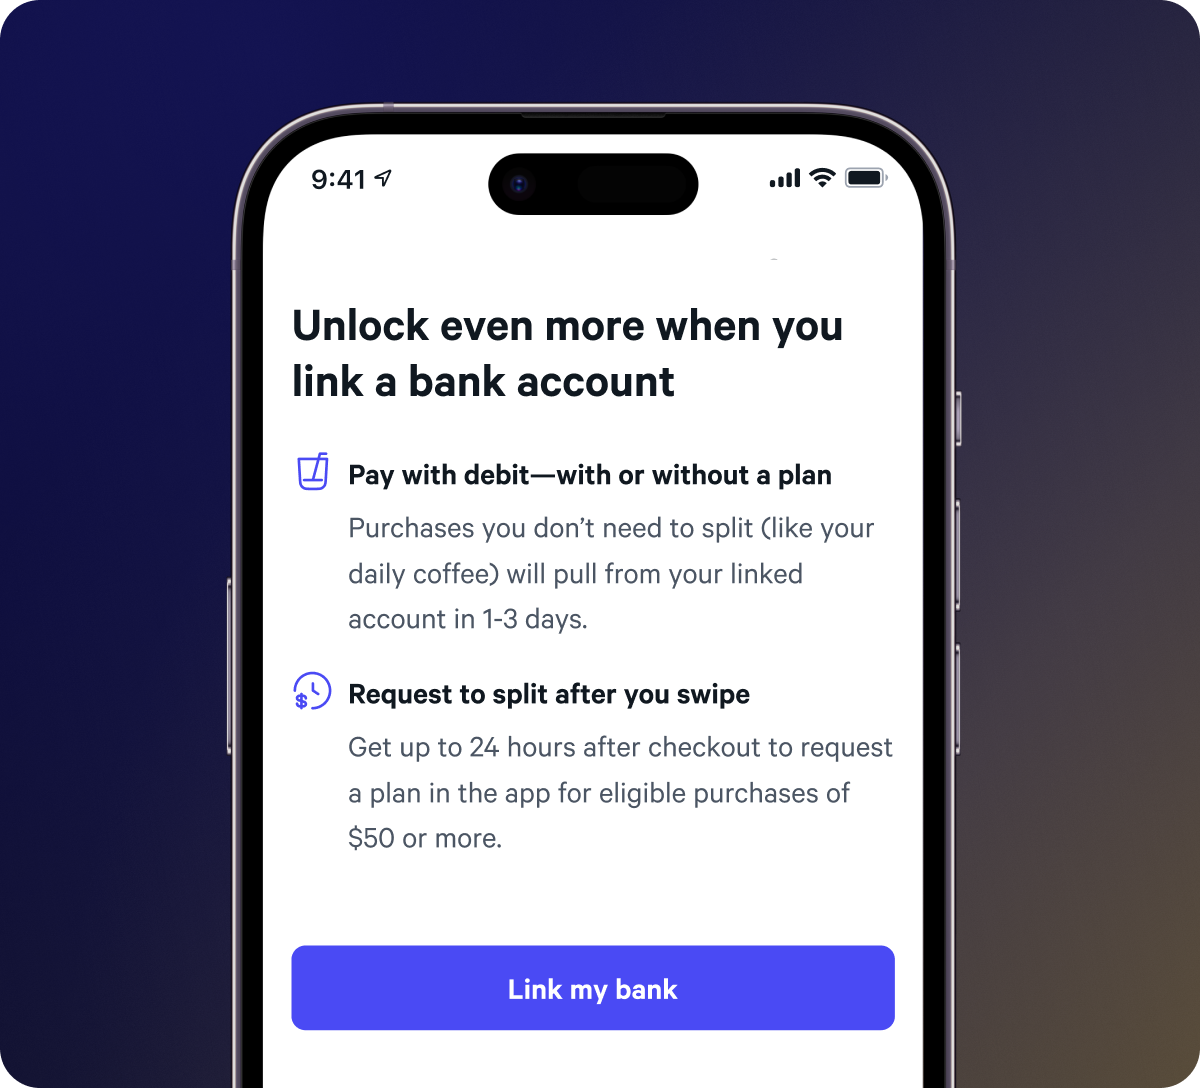
Step one: You need an approved Affirm account. This means a soft credit check, which usually completes in minutes, though hard pulls do happen depending on the loan amount and your credit profile. Step two: Activate the digital card inside the Affirm app. It is virtual-first. You get a card number, expiry, and CVV that you can add to Apple Pay, Google Pay, or your preferred wallet. Step three: Choose how you want it funded. You can tie it to a specific loan so every purchase draws from that loan balance, or you can set it to pull from your linked bank account on a schedule. Most people pick the bank account route because it gives them the option to prepay without touching the loan principal. Let me give you a concrete scenario. A small marketing agency owner I work with uses the Affirm card for software subscriptions, cloud hosting, and occasional equipment purchases. The card sits alongside a regular checking account. When the subscription bill hits, the card processes it. At the end of the month, the loan or installment balance is either paid off or rolled into the next cycle. She saves about twenty minutes per month on reconciliation because every charge maps cleanly to an invoice. That sounds minor. It compounds over a year.
Get the Full Details
Where It Actually Helps
The strongest use case is cash-flow smoothing. If your income arrives monthly but your expenses are irregular, spreading a large one-time cost across three to twelve months prevents a single month from breaking your budget. A dental procedure, a car repair, a professional certification exam fee. These are the things that show up without warning and force you into a high-interest credit card if you do not have liquidity. Affirm gives you a structured alternative that is usually cheaper than standard credit card APRs, which frequently sit between eighteen and twenty-five percent for people who have been burned by late payments. Predictable billing is the second real benefit. You know exactly what you owe and when. There is no surprise statement balance that spirals because you only paid the minimum. The fixed payment model forces discipline. That discipline is what most people are missing when they talk about financial freedom. It is not about earning more. It is about not losing ground to compounding interest on unpredictable purchases.
Where It Fails Completely
I need to be blunt here because most articles will not be. The Affirm card does not help you build credit in the way a secured credit card or a traditional credit-builder loan does. Affirm reports to some bureaus, but the reporting is inconsistent and often limited to collections activity rather than positive payment history. If your goal is to repair a damaged credit file, this is the wrong tool. Use a secured card instead. Pay it in full every month. That is a slower path but it actually moves the numbers. The card also does not work everywhere. It requires merchants that accept contactless payments or online checkout flows that support digital wallets. Cash transactions, certain government fees, and some recurring billers that only accept direct bank debits will not go through. I learned this the hard way when I tried to pay a municipal property tax installment. The portal rejected the card. Had to reroute to a wire transfer and eat the processing fee. Factor that into your mental model of where this card belongs in your financial stack. There is also a behavioral risk that is easy to ignore. When spending feels abstract, you spend more. I watched a friend of mine buy a $600 mechanical keyboard because he could split it into four monthly payments and the monthly hit felt manageable. He did not need the keyboard. He needed to stop treating installments as a discount on impulse. The math is the same. You are still paying six hundred dollars. The only difference is that you paid it slower.
A Workaround I Actually Use
Here is the edge case that trips people up. Suppose you get a loan for a large purchase but then you want to make a smaller follow-up purchase before the first payment is due. You might think you can just use the card again and the system will automatically allocate it. It does not always work that way. In my experience, the Affirm card routes charges to the newest open loan first unless you manually adjust the allocation in the app. So if you have a twelve-month loan for a refrigerator and you use the card again for a monitor, the monitor charge may attach to a fresh short-term loan rather than reducing your existing payment obligation. That changes your monthly cash flow in ways that are easy to miss. The workaround is simple but requires habit. Before every purchase, open the app, check your active loans, and manually assign the charge to the correct loan if the auto-allocation is not what you want. It adds maybe thirty seconds per transaction. Over a year, those thirty seconds prevent payment miscalculations that can cascade into missed deadlines or unnecessary fees.
Alternatives Worth Knowing
If your primary concern is credit building, look at Secured Mastercard or Discover it Secured. The rewards are thin but the reporting is reliable. If you need flexibility with no credit check, a prepaid Visa or Mastercard loaded from your bank account is the most straightforward option. It has no loan, no interest, no allocation confusion. The downside is that you must pre-fund it, which removes the smoothing benefit entirely. If you want cash back plus installments, some traditional credit cards offer promotional zero-percent APR periods that can beat Affirm on cost if you pay the balance in full before the promo window closes. That requires a higher level of financial discipline than Affirm demands, but the savings can be significant if you can execute it. Summary of the practical reality: The Affirm card is a utility, not a strategy. It works well for predictable large purchases that you can repay on schedule. It fails when you treat it as a way to extend discretionary spending without changing your spending habits. It does not rebuild credit. It does not replace an emergency fund. What it does do is turn chaotic debt into structured payments. For people who struggle with the chaos, that structure is worth something. For people who need it to be a miracle, it will disappoint you.