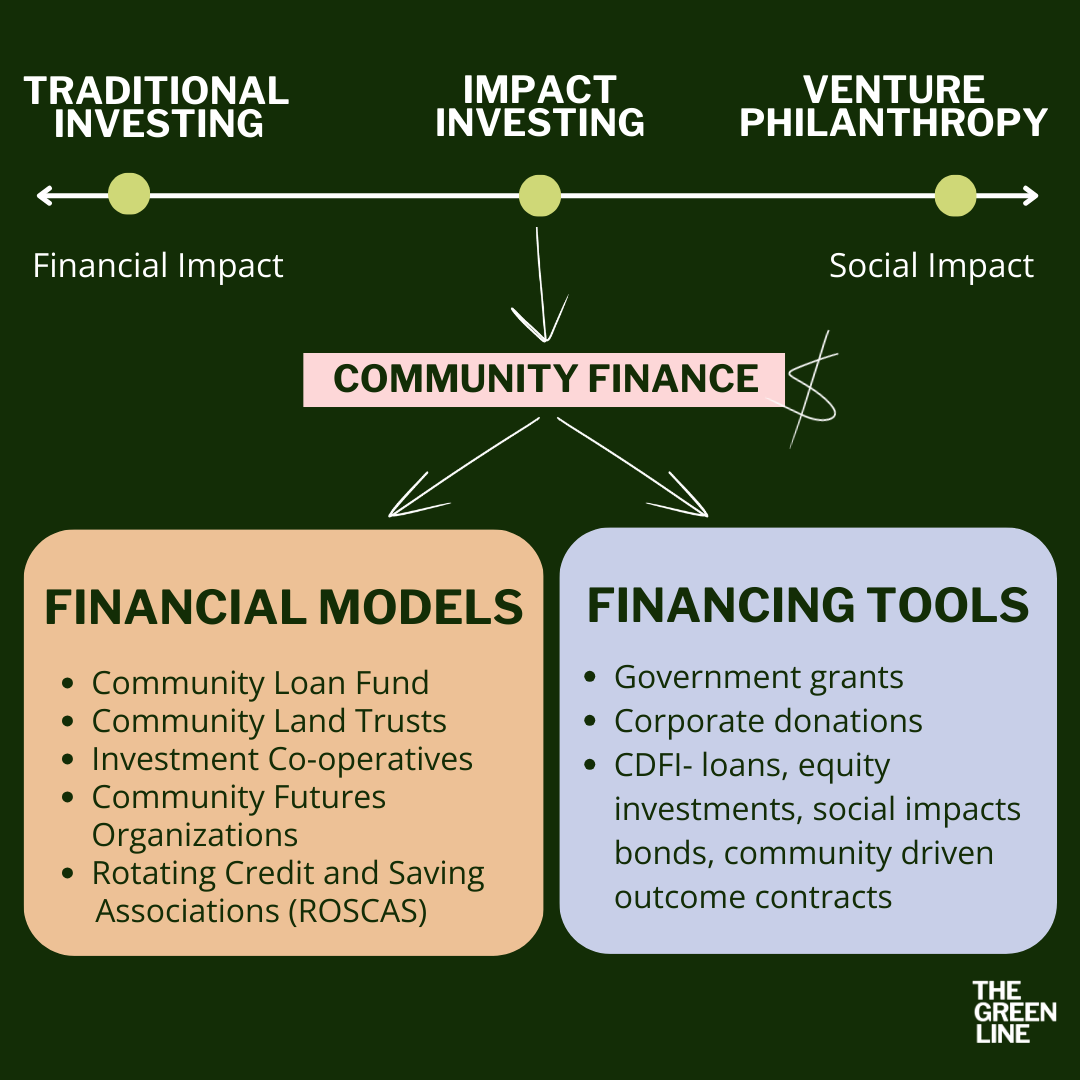
Community Finance Platforms Are Messy Until You Know How They Actually Work
I spent about eighteen months working with community finance protocols before I stopped second-guessing my setup every time a transaction failed. Osclms is one of the more notable solutions that has emerged in this space, and like most of these platforms, it sounds better on paper than it does during a morning when you are trying to submit a payment at 7 AM and everything is timing out. The core idea behind Osclms is straightforward enough. It provides infrastructure for community-based financial management where groups can pool resources, track contributions, distribute funds, and manage shared budgets without relying entirely on traditional banking structures. The appeal is real, especially for cooperatives, mutual aid groups, DAOs, and small community organizations that have historically been priced out of proper financial tools. What people do not always understand going in is that "community finance" does not automatically mean "simple." Osclms sits somewhere between a spreadsheet and a full banking system, and that middle ground has its own set of friction points that will bite you if you are not prepared.
Here is how the system actually functions under the hood. You create or join a community workspace. Each member gets assigned a role with specific permissions. Funds enter through designated contribution channels, which can be cryptocurrency or fiat depending on your configuration. The platform then applies whatever governance rules you have set up for disbursement, whether that is majority vote, multi-signature approval, or automatic distribution based on predefined criteria. Everything is recorded on-chain or in the platform's internal ledger, and reporting is generated from that data. The download and setup process varies depending on whether you are using the web interface or a self-hosted instance. The official Osclms portal provides a standard installer, and if you are running a Docker environment like I do, the containerized version deploys in roughly twenty minutes once you have your environment variables configured correctly. For smaller teams that do not need self-hosting, the web version is functional and does not require any technical background beyond basic account creation. Now here is something I learned the hard way. When you first connect Osclms to a blockchain network, the default gas estimation settings are almost never optimal for the networks you are likely using. I spent three weeks troubleshooting why my community's transaction fees were spiking to absurd levels before I realized the platform was using the wrong fee model for Polygon. Switching from the default EIP-1559 estimator to a legacy gas price oracle cut our average transaction cost from around four dollars down to about twelve cents per operation. That is not a marginal difference. It is the difference between a community finance tool that is viable and one that slowly bleeds resources until people stop using it.
Another thing nobody warns you about is the reconciliation gap. Osclms tracks transactions on-chain, but if your community also handles cash or external bank transfers, those entries do not automatically sync. I have seen multiple groups forget to manually log cash contributions and then spend six hours trying to figure out why their reported balance did not match their actual funds. The workaround is simple but requires discipline. Create a separate ledger tab inside Osclms specifically for off-platform transactions and make it a rule that anyone handling cash or bank transfers must log the entry within twenty-four hours. It feels like extra work until you are the one explaining a discrepancy to someone who brought physical donations. The platform does support smart contract automation for recurring distributions, which is genuinely useful if you are running something like a monthly stipend or a scheduled grant program. Setting up a recurring disbursement contract through Osclms typically takes about fifteen minutes once you understand the parameters. You define the recipient, the amount, the schedule, and the condition triggers. After that, the system handles execution without manual intervention unless a condition fails. There are limitations worth being honest about. Osclms works well for communities that are comfortable with digital wallets and basic blockchain interaction. It does not work well if your members are primarily non-technical elderly individuals or groups in regions with unstable internet connectivity. The platform requires consistent network access for real-time ledger updates, and if your community operates in an area where connectivity is intermittent, you will experience sync conflicts that are painful to resolve. I have dealt with a case where a rural cooperative lost three days of transaction data because the platform attempted to reconcile conflicting local and server-side states simultaneously. The data was recoverable, but the recovery process required manual hex-level inspection of the transaction logs, which is not something your average community treasurer should be expected to do.
Get the Full Details
Another honest limitation is the governance model. Osclms supports various voting mechanisms, but they are not as sophisticated as what you get from dedicated governance tools like Snapshot or Tally. If your community needs complex veto structures, quadratic voting, or delegation chains, you will find the built-in options limiting and end up building workarounds that introduce their own failure modes. For Fiat-to-crypto on-ramps, Osclms integrates with standard payment processors, but the fees from those processors are separate from the platform itself and can range from one to three percent per transaction depending on your region and provider. This is easy to overlook when you are calculating whether community finance is cost-effective compared to traditional banking. A typical community of fifty members sending five hundred dollars monthly through Osclms might pay roughly fifteen dollars in platform fees but another twenty to forty dollars in payment processor fees, which brings the total cost into a range that may or may not beat what a community credit union would charge. If your community is primarily focused on transparent budget tracking rather than blockchain-based transactions, you might be better served by a tool like Aeryo or EvenSplit, which handle the accounting side without introducing crypto complexity. Osclms adds value when you actually need the on-chain record-keeping or decentralized governance features. It adds friction when all you want is a shared expense tracker that does not require wallet management.
The platform does offer a free tier that covers basic community workspaces with limited members and standard reporting. The paid tiers unlock multi-signature requirements, advanced analytics, custom governance templates, and priority support. Pricing starts at roughly fifteen dollars per month for the basic paid tier, which scales based on community size and feature requirements. For a small group of twelve people, the free tier is usually sufficient for the first six to eight months of use before you hit any meaningful restrictions. The biggest mistake I see people make with Osclms is assuming that setting up the platform solves their coordination problems. It does not. A community finance tool is only as good as the rules and processes the community agrees on beforehand. I watched a group spend two weeks configuring Osclms with elaborate voting rules and then discover that half their members had never read the governance documentation. The platform was perfectly set up and completely unused because the humans involved had not aligned on how they actually wanted to make decisions. Before you install anything, write down your community's financial rules on paper. Not in the platform. On paper. Decide how contributions are tracked, who can approve expenditures, how disputes are resolved, and what happens when someone leaves the group. Then configure Osclms to match those rules, not the other way around. The platform should enforce your agreement, not replace the need for one.
If you are ready to try it, the official Osclms website provides installation packages for the major operating systems and a browser-based version that requires no installation at all. Documentation is available through their public wiki, though I have found that the community Discord is where most practical questions get answered faster than any support ticket ever would. The rise of community finance solutions like Osclms is not about replacing traditional banking. It is about giving groups that traditional banking has ignored or overcharged a functional alternative. It works, but it requires more deliberate setup and ongoing maintenance than a bank account. If you are willing to put in that effort, it can genuinely change how your community manages money. If you are looking for something that just works without any learning curve, this is probably not the right tool for you.