Getting Started With US Bank Access Online
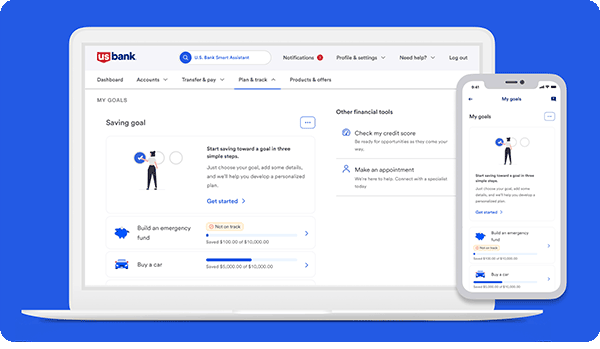
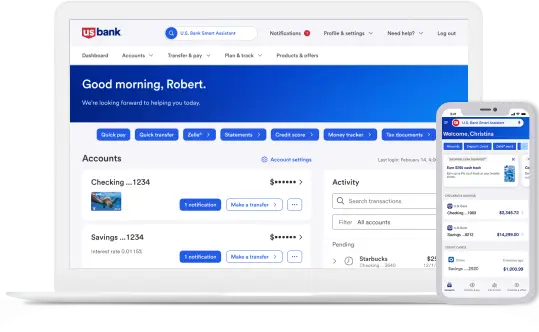
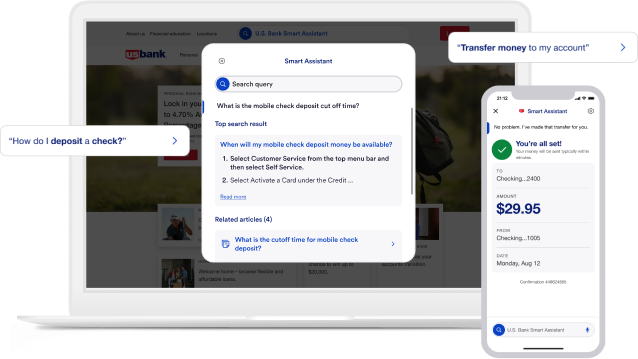
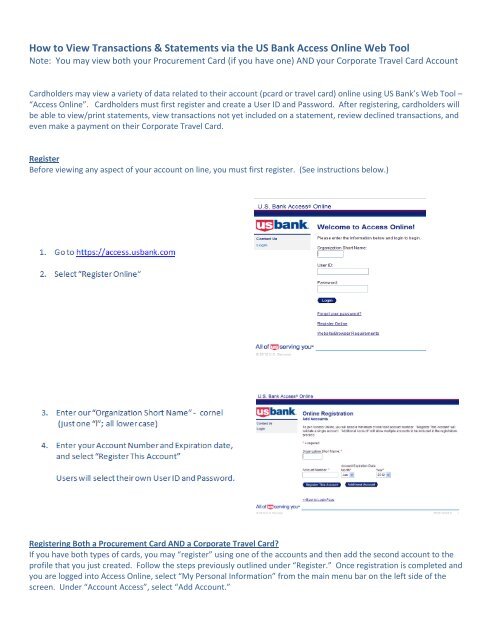
US Bank Access Online is the digital banking platform for US Bank customers. It gives you a way to check balances, transfer money, pay bills, and manage your accounts from a browser or mobile device without calling a branch or waiting in line. The basic setup is straightforward. You go to usbank.com and click "Enroll," enter your account number, Social Security number, and personal details, then create a username and password. After that, you set up a security profile with device registration and notification preferences. The whole process usually takes about ten to fifteen minutes if your information is accurate. Once you are enrolled, the actual workflow is fairly standard across large banks. Log in, view your accounts on the dashboard, select the account you want to work with, and choose from available actions. Transfers between your own accounts are instantaneous. Bill payments can be set up one-time or recurring. You can request checks, order a new debit card, and freeze a lost card directly in the app. Mobile check deposit lets you capture a check image with your phone camera and submit it for processing, typically crediting your account within one business day. I ran into a specific problem last year that most people do not expect. I needed to set up a direct deposit for my paycheck, but US Bank's system required the route number, account number, and a voided check image before accepting the setup. My employer's payroll portal would not let me submit the form without uploading that proof of account. I did not have a physical voided check handy at the moment. The workaround was to take a photo of the bottom of an old check, crop out the routing and account numbers, and use the bank's own "View Check Image" feature under account services to generate and download a verified check image. That took about five minutes and solved the issue. Some people miss that feature and end up emailing their employer asking for an extension.
The two-factor authentication system is one area worth paying attention to. US Bank uses a combination of a password, a security code sent to your registered mobile device, and sometimes a challenge question depending on the login context. The push notification verification through the mobile app is generally faster than waiting for an SMS code, so if you are on a slower cellular connection or traveling internationally, enable the app-based verification first. It cuts down login attempts from averaging forty seconds to around ten seconds. The SMS fallback should stay as a backup, not your primary method.
Common Mistakes and Advanced Settings
Many users enroll but never explore the deeper settings. Transaction alerts are one of those features. You can set custom thresholds for purchases, withdrawals, and balance minimums. A $0.01 alert on every transaction is noisy, but a single daily summary alert for any transaction over five hundred dollars is useful. Configure this under alerts in your account settings rather than relying on monthly statements. The monthly statement does not tell you what happened on day three of a problem; it only tells you at the end of the month. Another setting people overlook is the Zelle payment integration. It is built into the US Bank Access Online interface and lets you send and receive money using just a recipient's phone number or email address. The transfers are near-instant between US Bank accounts, and external bank transfers typically arrive within minutes during business hours. The catch is that Zelle payments are irreversible once sent. If you send money to the wrong contact or fall for a scam, there is no chargeback mechanism. I have seen this cause problems repeatedly. Treat Zelle the same way you would hand someone cash. Do not use it for anyone you have not verified personally. There are some limitations that matter more than the marketing materials suggest. The maximum mobile check deposit per day is generally five thousand dollars, with a monthly cap that varies by account type. If you deposit a check larger than that limit, the excess may not post until the next business day. Foreign transactions on a debit card linked to Access Online sometimes get flagged as suspicious and can result in a temporary hold while customer service verifies the activity. This is not a bug; it is the fraud detection system working, but it does mean you should notify the bank before traveling internationally if you plan to use your card abroad.
Get the Full Details

Password reset is another pain point worth noting. If you forget your password and your registered phone number has changed since enrollment, the automated recovery process will fail. The fix is not immediate. You need to verify your identity with a representative, which typically involves answering account-specific questions and providing a government-issued ID either in person at a branch or through a secure document upload. Expect the entire resolution to take anywhere from twenty minutes to two hours depending on branch staffing and upload queue times. Keeping your contact information current in the profile section prevents most of these situations.
What Actually Works in Practice
The online statement access is reliable. PDF statements are available for the past seven years, which is longer than most banks offer. If you are filing taxes or running a small business and need historical records, this saves you from digging through paper files. The search function within statements lets you filter by date range, amount, and payee. It is not perfect for fuzzy searches, but exact name matches and date filters work well. Bill pay through US Bank Access Online is functional but not as polished as newer fintech platforms. Recurring payments are supported, but you can only schedule them on specific calendar dates rather than dynamic dates like "the last business day of the month." If a scheduled bill falls on a holiday, you need to manually adjust it to the previous business day, or the payment may be delayed. I learned this the hard way when an insurance premium payment landed on a holiday and the provider applied a late fee. Adjust the schedule yourself before the holiday hits. Do not assume the bank will handle it automatically. Account linking is available for external accounts from other financial institutions. The process uses Plaid or a similar aggregator, and most major banks connect within a few minutes. Once linked, you can view balances and initiate transfers. Transfers between external accounts typically take one to three business days to complete because they go through the ACH network. If you need the money sooner, the instant transfer option exists but carries a small fee per transaction. Worth knowing about, but not something to use for routine transfers unless timing is critical.
The fraud monitoring dashboard shows recent transactions and lets you flag suspicious activity directly. Reported items are reviewed within one to two business days. Disputed charges usually result in a provisional credit while the investigation runs, but the credit amount depends on the situation and whether the bank determines the charge was clearly unauthorized. For legitimate billing errors where the merchant simply refuses to issue a refund, the dispute process is slower and less predictable. In those cases, chargebacks through the card issuer are more effective than the online dispute tool. Customer support accessibility through the platform is decent. The in-app chat feature connects you to a representative without a phone tree, which is better than average. Wait times vary by time of day, but off-peak hours between 10 AM and 2 PM on weekdays tend to have the shortest queues. Late evening and early morning slots often mean a twenty-to-thirty-minute hold even during normal business days. The phone support line is 1-800-955-8877, but use chat when possible for speed.

Security Practices That Matter
Logging out after every session is obvious advice, but some users rely on the "remember this device" feature across multiple computers and phones without reviewing which devices are registered. The device management page under security settings shows all active sessions. Review it monthly and remove any device you no longer use. Forgotten devices on old laptops or shared family computers are a common vulnerability. Password hygiene is another practical concern. The platform enforces minimum complexity requirements, but it does not check for password reuse across other websites. If you use the same password elsewhere and that other service suffers a breach, your banking credentials are at risk. A password manager that generates unique passwords for each account eliminates this problem. Update your US Bank password whenever you update another important account password, and do it on a trusted device, not a public computer. The app biometric login using fingerprint or face recognition is convenient, but it only protects the initial access layer. Once you are logged in, all transactions and settings changes are accessible without re-authentication unless the platform triggers a secondary verification for sensitive actions. This is standard behavior, but it means the convenience of biometric login comes with the responsibility of securing the device itself. A stolen phone with a weak passcode is a greater threat than the biometric feature can mitigate alone. Set a strong device lock screen and enable remote wipe through your phone's native recovery service.
Bottom Line
US Bank Access Online handles the everyday banking tasks reliably. Transfers, deposits, bill payments, and account monitoring all work as expected. The platform is not the most visually polished option on the market, and some workflows like holiday payment adjustments and Zelle reversibility require your attention rather than handling themselves. The deeper features like transaction alerts, external account linking, and the in-app chat support are worth spending time to configure properly after enrollment. Most problems people report stem from skipped setup steps or unupdated contact information, not from platform failures. Keep your profile current, review your registered devices periodically, and use the alerts and fraud tools before you need them rather than after.