Getting a Handle on Community Finance in Chicago
Chicago has been grappling with uneven economic health for decades. What makes it tricky is that most people don't have a clear picture of their own finances, let alone the financial health of their neighborhood. That's where organizations tied to Chicago Org Finance come in. They don't just hand out worksheets and hope for the best. They build systems that connect people to resources they didn't know existed. I spent three years working with a community finance initiative in the Englewood area before moving into consulting. The first thing I noticed was that nobody could explain how their local money actually moved. People were paying interest to predators because mainstream lenders wouldn't touch their zip codes. That's the baseline problem this whole field is built around.
Unlocking Financial Clarity How Www Chicago Org Finance Transforms Community Economic Health
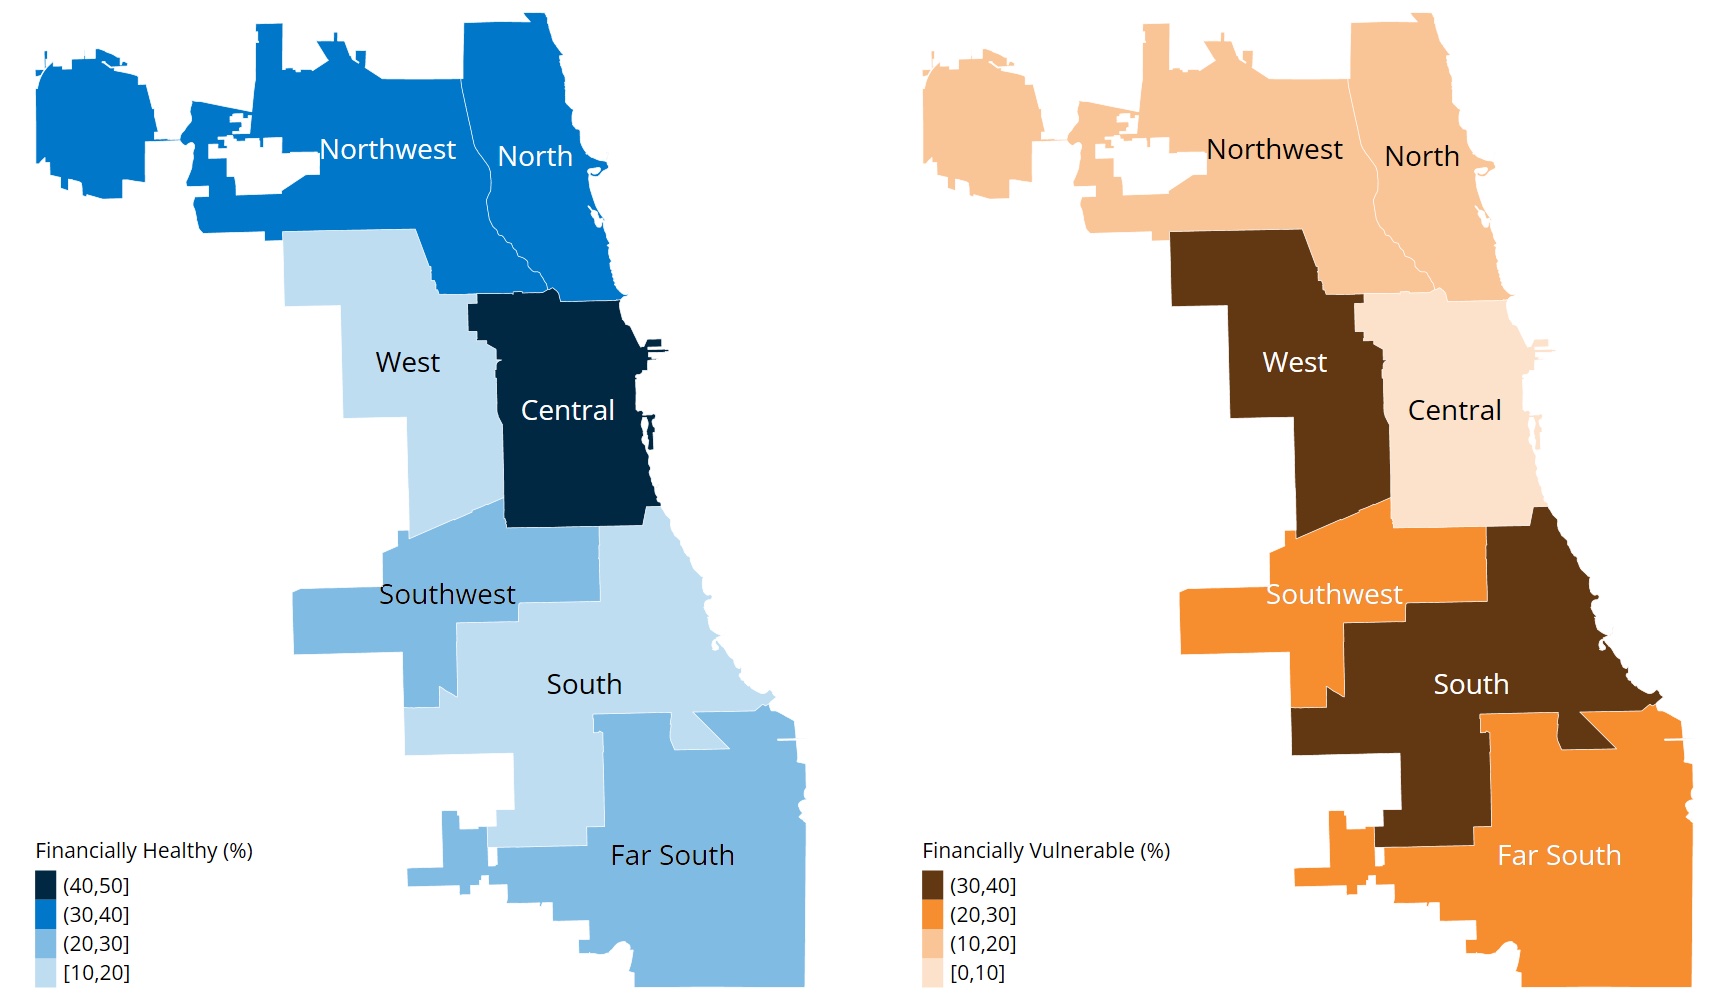
The phrase itself sounds like a mission statement from a grant application, but it's actually describing something real and measurable. Chicago Org Finance, or whatever group you're working with, starts by giving people access to plain-language financial tools. Not fancy apps with animations. Spreadsheets, budget templates, debt payoff calculators that actually work in plain English. The barrier isn't intelligence. It's that most financial literature assumes you already know what you're doing. The transformation part is where things get specific. Community economic health isn't an abstract concept. It's the number of households that can cover a four-hundred-dollar emergency without going into debt. It's the rate of small business formation in a given ward. It's how many people have a legitimate savings cushion. These are hard numbers to shift, which means the work takes time. Here's how the process actually works in practice. You start with a community assessment. Not a survey you send out via email. I mean sitting in a church basement with twenty people who've agreed to talk honestly about what they're earning, what they're paying, and where the gaps are. You listen for patterns. You're looking for the same three problems coming up over and over again: unexpected medical bills, car repairs that wipe out a month's cash, rent hikes that make existing budgets impossible.
Once you've mapped those patterns, you build a resource directory. This is the part that most initiatives skip because it's tedious. Who actually provides what service? Who gives free credit counseling? Who has emergency grant programs with no income floor? Who processes applications in under two weeks instead of six months? I learned this the hard way when I tried to refer someone to a food assistance program that turned out to have a three-month waiting list. The person needed help that month.
Get the Full Details
What This Looks Like Day to Day
Financial clarity work is mostly teaching people to read their own statements. Bank accounts, credit card bills, loan agreements. Most folks can't tell the difference between an APR and an annual fee. Once they can, everything changes slightly. They stop accepting terms they don't understand. They start noticing patterns in their spending that they weren't aware of before. The community side involves group workshops. Not lectures. Small groups of six to eight people working through the same budget scenario, comparing notes, asking questions they wouldn't ask in a one-on-one setting. There's a peer accountability element that formal education never captures. People show up when they know others are counting on them. One counter-intuitive thing I discovered early on: the people who benefit most aren't the ones in deepest crisis. They're the people sitting just above the surface of financial disaster, the ones whose emergencies aren't dramatic enough to qualify for aid but are significant enough to erode their stability over time. A single missed payment on a auto loan. A medical bill that sits unpaid for six months. These slow leaks compound into full damage. The toolkit needs to catch them before they become emergencies.
Common Mistakes That derail These Programs
Most community finance initiatives fail because they invest in tools before they understand the problem. They buy software licenses, print materials, hire coordinators. Then they discover that the people they're trying to serve don't have consistent internet access or the time to attend scheduled sessions. Nothing kills participation faster than requiring digital literacy from a population that was already shut out of the digital economy. Another failure point: treating financial education as a one-time event. I watched a program offer a single workshop on credit repair and consider the job done. Credit repair isn't a workshop. It's a daily practice of monitoring disputes, tracking utilization ratios, and maintaining payment history. You can learn the concept in an hour. Living it takes months of repetition and support. There's also the problem of assuming that access equals usage. Just because an emergency fund exists doesn't mean community members will trust it. I encountered this firsthand in a South Side project where we had secured a revolving loan fund with zero interest. People were skeptical. They'd been burned by predatory lenders before. The workaround wasn't more marketing. It was having trusted community members — pastors, barbers, teachers — vouch for the program and sit through the application process alongside applicants. Trust transfers faster than information ever will.
Measuring Real Impact
Most organizations report on attendance numbers and materials distributed. Those metrics mean nothing if the underlying economics don't shift. The real measures are harder to track: household savings balance changes, reduction in high-interest debt, small business retention rates, eviction filing statistics in the neighborhoods you serve. If you can't connect your work to these numbers, you're not demonstrating transformation. You're demonstrating activity. The data collection itself is another operational challenge. Participants often won't share exact income figures or debt amounts in early sessions. You have to build enough rapport before they'll be honest, and even then the numbers may be approximate. What I found works is asking people to bring their actual documents to later sessions, not the first meeting. The first meeting is just establishing whether the program is worth their time. If you're looking to start something similar in your area, begin with the assessment phase and spend at least three months on it. Don't rush into programming. The wrong program is worse than no program because it wastes the trust you're trying to build. Chicago Org Finance and its network have shown that the model works, but the work is granular and unglamorous. It's reading spreadsheets in people's kitchens and following up on loan applications.