How The Sam's Club Credit Card Actually Works
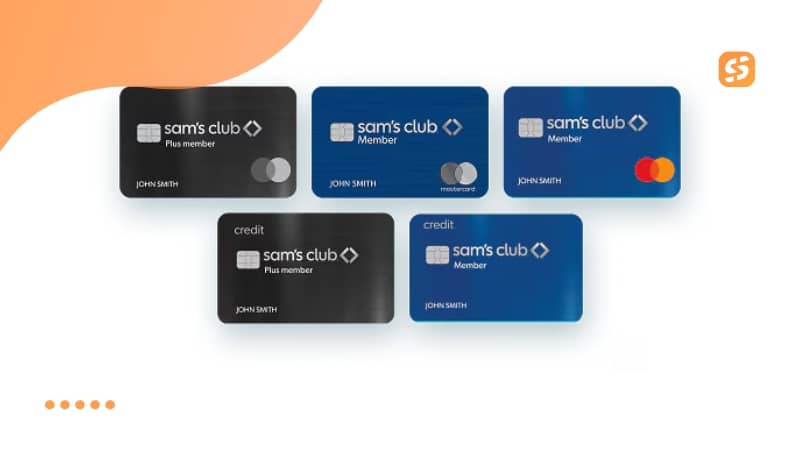
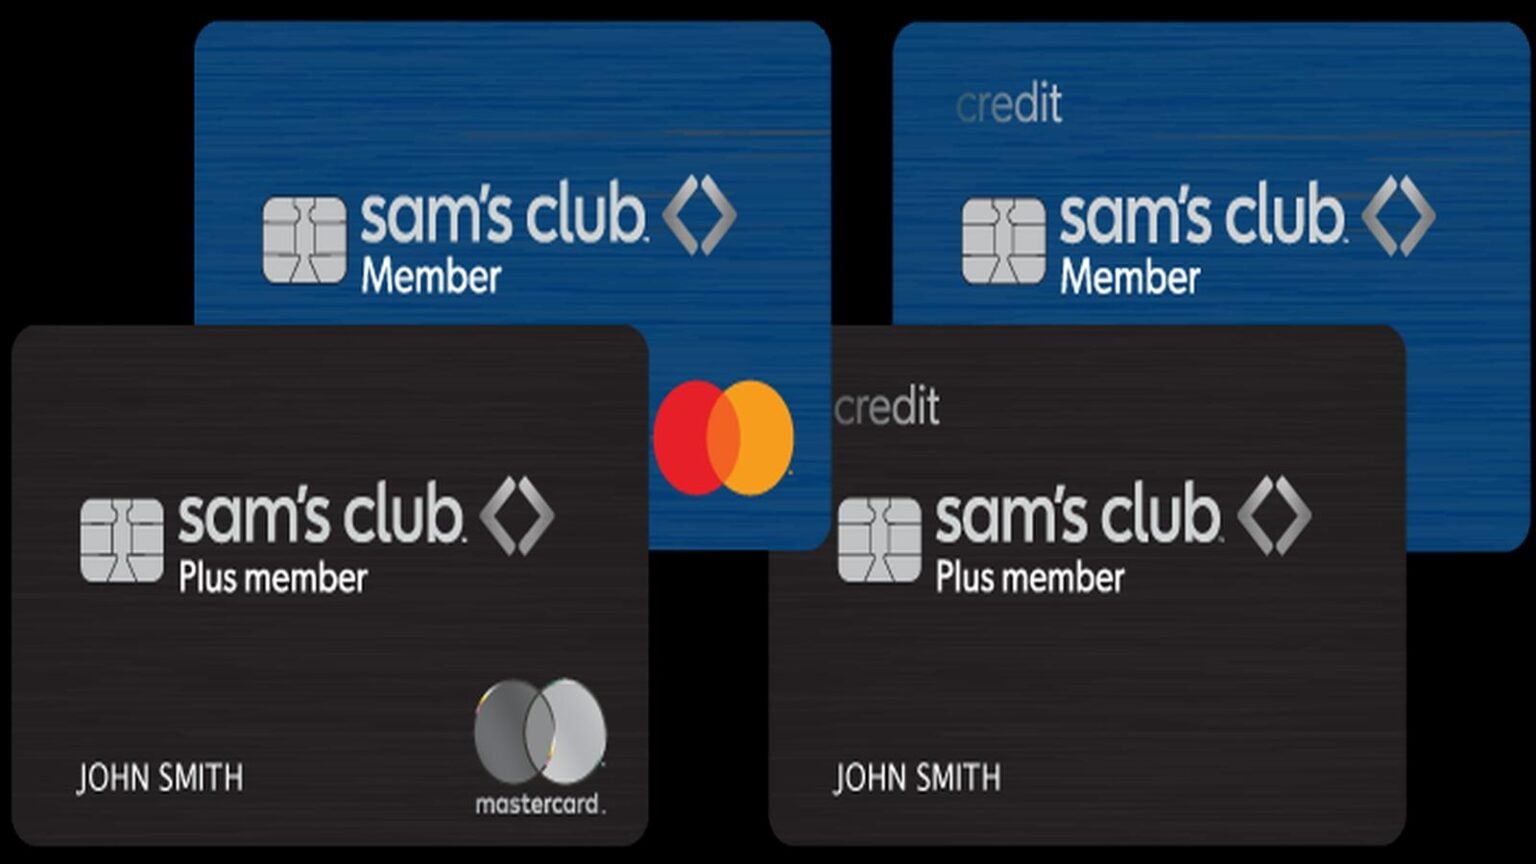
The Sam's Club Credit Card from Synchrony Bank is a store-credit product tied to the Warehouse membership ecosystem. It gives you 5 percent back in Rewards on Sam's Club purchases, 3 percent at gas stations and on travel, and 1 percent everywhere else. The rewards show up as a certificate you can redeem next time you walk through the doors. Most people treat it like any other credit card and miss the structural advantages, which means they leave money on the table. Here is what actually matters beyond the headline percentages. The card unlocks pricing that is not visible at checkout until you select it as your payment method. That includes member-exclusive deals that rotate weekly, early access to fire sales, and the ability to stack the 5 percent back on top of already-discounted items. I saw this play out last November when I bought a case of paper towels marked down to $18.97 during a Member Event. Using the card dropped my effective price by another dollar and forty cents. On paper it sounds trivial. On a recurring grocery run it adds up to roughly two hundred and sixty dollars a year for someone who spends around five thousand annually at Sam's Club. The real friction point people run into is that the card does not automatically apply to every transaction type. If you are buying groceries through Instacart or using a third-party payment link, the rewards tier drops to 1 percent and sometimes the promotion does not register at all. I hit this exact problem when I ordered party supplies through the Sam's Club online portal using Express Checkout. The order showed 5 percent Rewards in the cart, but when the shipment arrived the certificate was missing from my account. The workaround was to call Synchrony with the order number and receipt, verify that the purchase went through the official Sam's Club payment gateway, and request a manual adjustment. It took twenty-two minutes and they credited the certificate the same day.
Structural Details Beginners Miss
The 5 percent Rewards are not a direct discount at the register. They accumulate as a Sam's Club Rewards Certificate on a quarterly schedule. You earn based on eligible purchases during the quarter, then receive the certificate roughly thirty days after the quarter closes. The certificate amount usually comes out to two decimal places, and you can apply it toward membership renewals, in-club purchases, or eligible online orders. It does not come back as cash or a statement credit unless you specifically redeem it through the app. Another thing that trips people up is that returns reduce your Rewards earning for that quarter. If you buy a four-hundred-dollar television and return it two weeks later, the system recalculates your 5 percent back on that transaction, which can drop your certificate from something like twelve dollars to zero if that was your only qualifying spend. This is documented in the terms but most members never read them. The fix is to time large purchases near the end of a quarter so the return window falls in the next cycle. It is a minor scheduling adjustment that prevents unexpected certificate erosion.
When The Card Makes Sense And When It Does Not
This card is strong if you shop at Sam's Club at least twice a month and spend over three thousand dollars annually. The 5 percent back on those purchases alone typically exceeds the cost of an Executive membership over a twelve-month period. The gas and travel categories are secondary benefits but they do compound if you use the card for everyday driving. I fill up at Costco on some weeks and Sam's on others. When I switched my primary fuel spend to Sam's locations near my route, the 3 percent back on gas added another forty-five dollars annually to my total return. The downside is immediate. This is a secured-or-unsecured retail card from a subprime-adjacent issuer. Synchrony reports to all three bureaus and the approval odds correlate heavily with FICO scores above six hundred and seventy. If your credit is thinner, you will likely get a lower limit and higher APR. The standard APR range sits between eighteen and twenty-eight percent variable, which is not competitive compared to general-purpose cash-back cards. If you carry a balance, the interest cost swallows the Rewards quickly. I once kept a three-hundred-dollar balance from a mistaken auto-renewal charge and paid roughly eighteen dollars in interest over ninety days. The Rewards earned during that same window were fourteen dollars. It is a net loss. There is also a membership requirement that gets overlooked. You cannot use the card for in-club purchases unless you hold a valid Sam's Club membership. The free trial membership that comes with card approval only lasts until your first statement cycle ends. After that you need to maintain a paid membership, which starts at fifty dollars for the Club tier and one hundred and one dollars for Executive. If you only shop at Sam's Club three or four times a year, the membership fee plus the card's opportunity cost makes a general-purpose card like the Citi Cash or Amazon Prime Rewards Visa a better fit. Those cards deliver 2 percent back on a broader set of categories without requiring a warehouse subscription.
Get the Full Details
Practical Setup Steps
To actually activate the rewards flow you need to link the card to your Sam's Club account after approval, enable digital wallet usage if you want mobile pay, and opt into the automatic certificate delivery setting. Without linking the accounts the 5 percent still posts to your Synchrony balance, but you lose the stacking advantage with Member Events. The app shows the certificate in the Rewards tab each quarter, but it will not apply automatically at checkout. You have to manually select it from your wallet during payment. I learned this the hard way during my first renewal cycle. My certificate sat unclaimed for eleven days because I assumed it would process automatically. The next quarter I set a calendar reminder five days before the certificate post date and applied it manually before any large purchase. That small habit has prevented at least one instance of certificate expiration over three years of use.
Edge Cases Worth Noting
Prescription purchases, money orders, and certain pharmacy transactions are typically excluded from Rewards earning. Grocery delivery fees and installation charges also often fall outside the eligible purchase definition. I encountered a situation where a tire installation quote included a seventy-dollar service fee that was bundled into the total but not counted toward the 5 percent back. The system only rewarded the tire product cost. I filed a dispute through the Synchrony portal with the itemized receipt and won the adjustment after forty-eight hours. Keeping receipts with line-item breakdowns has become standard practice in my routine. If you use the card for seasonal bulk buys like holiday decorations or winter gear, watch for promotional financing offers that Synchrony occasionally runs. These are separate from the Rewards structure and carry their own APR terms. I once financed a eight-hundred-dollar purchase with a zero-percent offer for twelve months and missed a payment by two days. The retroactive interest kicked in at the standard twenty-three percent APR on the full original balance, which wiped out any Rewards gain for that year. Never miss a payment on promotional financing. The penalty is disproportionate. The application itself takes about four minutes with a soft pull that does not affect your score. Approval decisions are near-instant in most cases. Card delivery arrives within seven to ten business days. Once activated, the digital card is available the same day through the Synchrony mobile app, so you can use it for online orders immediately. There is no annual fee on the card itself, but the membership requirement is the hidden cost. Factor that into your break-even calculation before submitting.