What macroeconomics actually teaches you
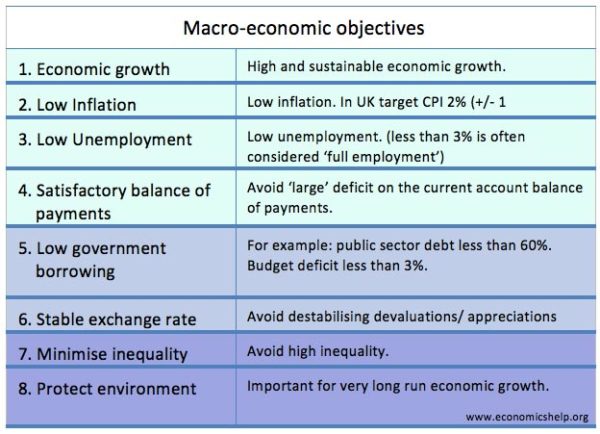
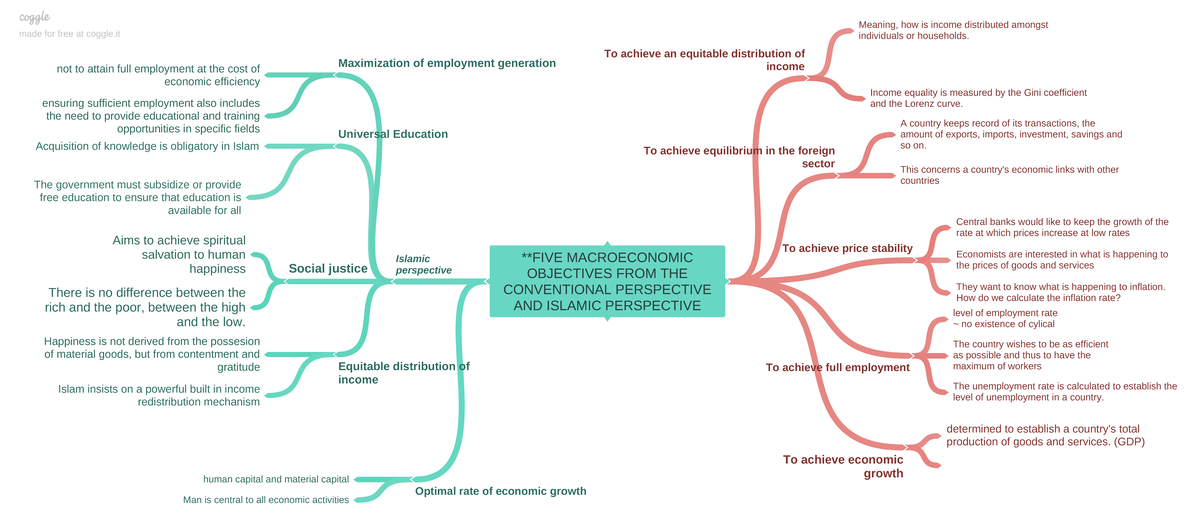
Most introductory courses list the five main goals before you've even figured out what a GDP deflator is. It's not that they're unimportant. It's that presenting them as a checklist makes the whole system look cleaner than it really is. I spent years working in policy analysis and the gap between textbook objectives and what shows up in government briefings is where most people get confused. The five macroeconomic objectives are economic growth, low unemployment, stable inflation, balance of payments equilibrium, and equitable income distribution. That's the standard list from the UK Treasury, the Fed, and most central banking frameworks. The problem is they don't all move together. You can chase any one of them and the others will react in ways that aren't always gentle.Unlocking Economic Success Explaining The Five Macroeconomic Objectives With Realworld Examples
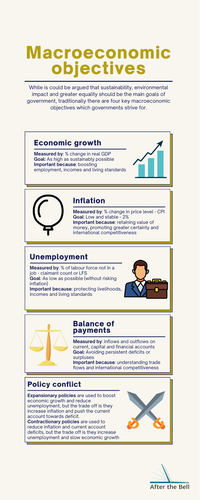
Economic growth is the one everyone cares about most. It's measured by the percentage change in real GDP over a year. Real means you've stripped out inflation so you're looking at actual output, not just prices rising. The UK targets something close to 2 to 2.5 percent sustainable growth. The US Federal Reserve doesn't have a fixed number but historically sees 2 to 3 percent as healthy for a mature economy. The growth number matters because it drives everything else. Revenue, tax receipts, employment levels. When growth stalls below one percent for multiple quarters, governments start panicking. When it runs above three percent for too long, central banks get nervous about inflation. I remember sitting in a briefing around 2022 when the German economy technically contracted. The headlines said recession but the underlying private consumption data was still positive. The discrepancy mattered because it changed whether the Bundesbank leaned hawkish or stayed accommodative.
Unemployment and what the headline number hides
The unemployment rate sounds straightforward. It's the share of the labour force that's actively looking for work and can start within a couple of weeks. But the official rate misses a lot. Discouraged workers who've stopped looking don't count. Part-time workers who want full-time hours don't count. The US measures this as U-3, the headline rate, but also publishes U-6 which adds those groups. U-6 is usually two to three points higher than U-3 during normal times and sometimes five points higher during downturns. Low unemployment is desirable until it gets too low. When the rate drops below what economists call the natural rate of unemployment, wage pressures build. Firms compete for workers, bid up salaries, and those costs flow into prices. The UK natural rate has floated between 4.5 and 5 percent for decades. The US version is probably closer to 4 to 4.5 percent now than it was in the 1990s. I worked on a forecasting model once where we kept underestimating wage growth because we were using an old NAIRU estimate. The model predicted inflation would stay flat. It didn't. The fix was updating the natural rate assumption and adding a lagged wage-price pass-through coefficient.
Inflation stability is more nuanced than most people think
Central banks target 2 percent inflation in most advanced economies. The ECB, the Fed, the Bank of England, the Bank of Japan all sit somewhere near that number. The target isn't zero because a small positive rate gives policymakers room to cut real rates during recessions without hitting the zero lower bound. It also prevents deflationary spirals where consumers delay purchases expecting cheaper prices tomorrow. Stable means predictable, not stuck. A gradual rise from 1.5 to 2.5 over two years is stable. A jump from 2 to 6 in six months is not. The UK experienced exactly that problem in 2022 and 2023. Energy prices spiked after geopolitical events, core inflation ran above 5 percent, and the Bank of England had to raise rates aggressively. The cost was a sharp slowdown in construction and automotive output. The benefit was inflation falling back toward target within eighteen months. I've seen analysts argue over whether 2 percent should actually be the target. Some economists in New Zealand and Canada have publicly suggested 3 percent might be better because it provides more monetary policy buffer. The argument is real, not theoretical. Countries that adopted higher targets historically saw slightly more employment stability during downturns. The counterargument is credibility. Once you move the goalpost, markets discount future communications harder.
Get the Full Details

The balance of payments constraint
This objective gets less attention in public debates but it's the one that constrains policy most directly for open economies. The current account records trade in goods and services, investment income, and transfers. A persistent deficit means the country is consuming more than it produces and financing the gap with foreign borrowing or asset sales. The UK has run a current account deficit for roughly thirty years. That hasn't collapsed the pound or triggered a crisis because the deficit is financed by deep capital markets and the city of London attracts steady foreign investment. Japan runs persistent surpluses instead. That creates different pressures: currency appreciation risks, export sector strain, and domestic demand that stays weak. I once advised on a scenario model for a medium-sized European economy that was running a 6 percent current account deficit. The textbook answer was devaluation or austerity. The reality was more complicated. The deficit was partly driven by capital goods imports supporting long-term productivity. Cutting those imports to improve the balance would have lowered future growth. The workaround was accepting the deficit temporarily while monitoring external debt sustainability. When external liabilities exceeded 100 percent of GDP, that's when you pull the trigger on adjustment measures.
Income distribution and why it keeps getting added to the list
The fifth objective isn't always taught as clearly as the first four. Income distribution refers to how evenly or unevenly national output is shared across the population. Gini coefficients measure this. The OECD average sits around 0.31. The US is closer to 0.39. Scandinavian countries run near 0.27. Higher inequality correlates with slower growth over medium horizons because it constrains human capital investment among lower-income households. Policies that affect distribution include progressive taxation, minimum wage adjustments, union bargaining power, and transfer payments. The tradeoff with growth isn't always straightforward. Some redistribution slows growth if it reduces incentive to work or invest. Other forms of redistribution, particularly in education and healthcare access, boost long-term productivity. The evidence leans toward the latter being more effective in developed economies.
How the objectives interact in practice
The Phillips curve used to describe the inflation-unemployment tradeoff. It's not dead but it's much flatter than it was in the 1970s. Central banks learned that lesson the hard way. Since the early 2000s, the relationship has weakened considerably. That's partly because globalization kept import prices down and partly because inflation expectations became better anchored. The growth-inflation relationship is also less linear than textbooks suggest. Moderate growth rarely triggers runaway inflation in economies with spare capacity. But growth above potential for extended periods does. The US in 2021 and 2022 is a recent example. Fiscal stimulus pushed demand beyond what supply chains could handle. Inflation jumped from 1.4 percent to 9.1 percent over twelve months. The Fed raised rates from near zero to over 5 percent within eighteen months. Growth slowed but didn't enter recession, which is the outcome everyone was shooting for. What beginners miss is timing. Each policy instrument has lags. Monetary policy affects the real economy with a delay of twelve to eighteen months. Fiscal policy moves faster but gets tangled in legislative process. Supply-side reforms take years. If you time everything correctly, you're either extremely lucky or you're inside a government with unusually smooth coordination. The UK Treasury and the Bank of England have formal independence arrangements since 1997. That helped during the 2008 crisis and again during the 2020 pandemic response. It didn't prevent missteps in 2022 when fiscal announcements conflicted with monetary tightening.
When the framework breaks down
These five objectives assume a relatively stable economic environment. They don't handle well when you face simultaneous supply shocks, financial crises, and demographic collapse. Japan in the 1990s showed how demographic aging can make all five objectives harder to achieve at once. Low growth, persistent deflationary pressure, high public debt, an aging population reducing the labour force, and a current account surplus that masks weak domestic demand. No single policy tool fixes that cluster of problems. Another failure mode is hyperinflation or currency crises. Zimbabwe in the late 2000s, Venezuela in the 2010s, Turkey intermittently since the 2000s. When prices double every few months, the concept of stable inflation becomes meaningless. The objective shifts from price stability to survival. Macroeconomic policy in those environments is less about managing cycles and more about establishing basic monetary credibility through dollarization, currency boards, or radical fiscal consolidation.
Practical takeaways
If you're studying this for an exam, memorize the five objectives and the standard policy tools associated with each. Fiscal policy for growth and distribution, monetary policy for inflation and unemployment, supply-side policy for long-term growth potential, exchange rate policy for the balance of payments. That's the framework. It works well enough for most textbook problems. If you're actually working in the field, learn to track the indicators that matter most for your specific context. For the UK, watch the ONS unemployment rate, the BoE inflation report, the Treasury fiscal forecasts, and the IMF balance of payments data. For the US, watch the BLS jobs report, the Fed's Summary of Economic Projections, BEA GDP estimates, and the Treasury international capital system data. The signals are noisy. You need to read multiple sources before forming a view. The hardest part isn't knowing the objectives. It's accepting that achieving all five simultaneously is rare. Most policy decisions involve choosing which objective to prioritise and which to tolerate suboptimal performance on. That tradeoff is where the real work happens.