
Setting Up Regions Bank Online Banking Without Losing Your Mind
Most people treat online banking like it is some kind of tech challenge. It is not. It is just a website with a login box. The actual process of getting set up and then using it every day is where people make mistakes that stick with them for months. I spent years helping people untangle their own banking setups. Not because the banks are complicated, but because nobody reads the fine print on the enrollment screens and then gets confused when something does not work the way they expected. So here is how Regions Bank online actually works, what you need to get it running, and the things that usually trip people up once they have been using it for a while.
Regions Bank Online Banking Guide Unlocking Convenient Banking
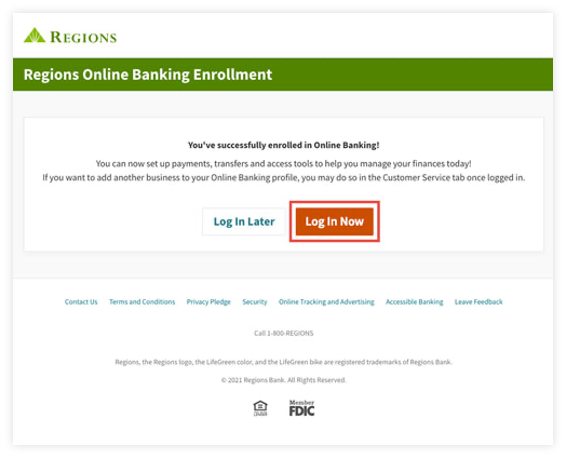
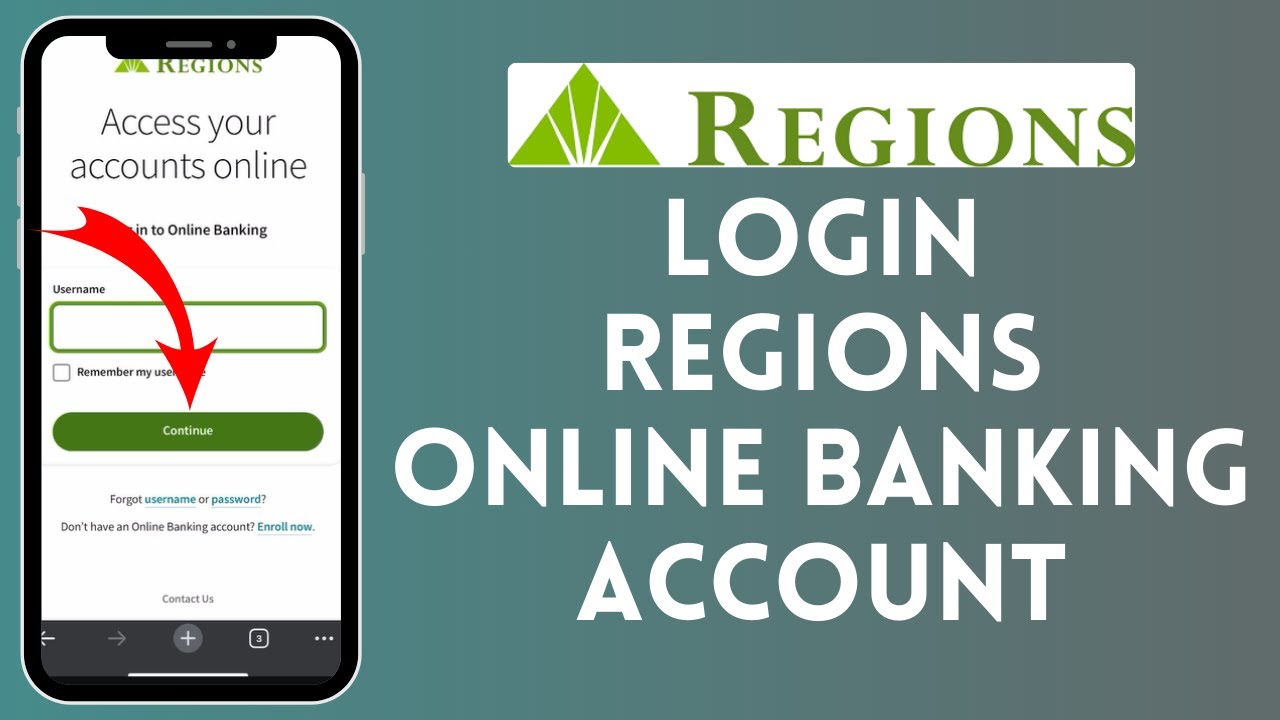
The first step is getting your account linked to the digital platform. You need your account number, your social security number (or the equivalent tax ID for business accounts), and the email address you plan to use for notifications. Go to the Regions Bank website and click the enrollment link for new customers. If you already bank there in person, the enrollment is faster because your account information is already in their system. You might be asked to verify your identity through a series of security questions that they pulled from your account history. I ran into a specific issue last year with a customer who had opened a joint account with his wife about eight years ago. When he tried to enroll online, the system kept rejecting his login attempts even though he was typing everything correctly. The problem was that the online portal treated joint accounts differently than individual ones during registration. The workaround was simple but not obvious: he had to call the customer service line and ask them to manually activate the digital profile on the joint account before he could enroll. Took about twelve minutes on hold, but it saved him from trying to re-register three different times. After enrollment, you will get a username and a password. Choose something you can remember without writing it down, but that is also not something a password manager would guess in a single attempt. Regions uses multi-factor authentication now, so you will be prompted to verify your identity through a code sent to your phone or email when you log in from a new device. This is actually a good thing, even though it feels like extra friction.
The dashboard layout is straightforward. You see your account balances at the top, a recent transaction list below that, and a navigation menu on the left side. The mobile app mirrors most of these features. I prefer the desktop version for anything involving transfers or bill payments because the interface gives you more screen space and the menus are slightly faster to navigate than the mobile app, which tends to be a bit laggy when you are switching between account views.
Get the Full Details
What You Can Actually Do Once You Are Logged In
Beyond checking your balance, the platform handles most routine banking tasks. You can transfer money between your own accounts instantly. External transfers to other banks take one to three business days depending on the receiving institution. Bill pay is built in, and you can schedule recurring payments or one-time sends. Mobile check deposit is available through the app if you snap a picture of the front and back of a check. One feature that people overlook is the ability to set up account alerts. You can configure notifications for low balances, large transactions, wire transfers, or even when a direct deposit hits your account. These alerts go to your email or phone. I recommend turning on at least a couple of them. It saves you from discovering an unauthorized charge three weeks later when you are trying to reconcile your statement. The Zelle integration is worth mentioning separately. It is built directly into the Regions app and lets you send and receive money from other Zelle users. Transfers are usually instant if both parties are enrolled. The downside is that Zelle transfers are basically irreversible. If you send money to the wrong person or get scammed, your options are very limited. I have seen too many people lose money this way because they did not double-check the recipient before confirming the transaction.
Here is a detail that most guides do not mention: Regions Bank places a temporary hold on newly deposited checks depending on the amount and your account history. For direct deposits, funds are usually available within one business day. For paper checks deposited via mobile, the first five hundred dollars tends to be available the same business day if you deposit before the cutoff time, which is typically around 8 PM Eastern. Anything above that amount may be held for two to five business days on the first deposit. This is standard across most banks, but people still get surprised by it when they expect immediate access to a large check.
Common Problems and How to Fix Them Without Calling Support
If you forget your password, the reset process goes through your registered email or phone. You should set up both methods during enrollment. If you only have one and you lose access to it, you are stuck waiting for customer service. I learned this the hard way with a client who changed his phone number but never updated it in the banking system. He locked himself out for four days. Another issue is when the website says your session has expired mid-transaction. This happens frequently if you leave a tab open for more than fifteen minutes. The platform terminates idle sessions for security reasons. The fix is to simply restart the transaction. Nothing is lost unless you were in the middle of submitting a form, in which case you may need to re-enter some information. The mobile app occasionally fails to recognize checks during deposit. The most common reason is poor lighting or a blurry photo. Make sure the check is flat on a dark surface with good overhead lighting. Remove any cases or stands. If the app rejects it twice in a row, do not keep retrying. Take the check to a branch and deposit it in person. There is a limit on the number of mobile deposits you can make per day, and burning through those limits on failed attempts just wastes time.
One thing the platform does not handle well is complex estate planning or trust account management. If you are dealing with accounts that involve multiple beneficiaries, power of attorney arrangements, or revocable trusts, the online system has limited functionality for updating those details. You usually need to visit a branch or speak with a representative to make changes to trust structures. The online portal is fine for basic account maintenance but falls apart when the account structure gets complicated.
Security Practices That Actually Matter
Enable two-factor authentication if you have not already. This adds a second verification step beyond your password. Regions has made this default for most new accounts, but if you enrolled a long time ago, check your settings to confirm it is active. You do not want someone guessing your password and then having unrestricted access to your accounts. Avoid logging in from public Wi-Fi networks. Coffee shops, airports, and hotels are fine for browsing, but banking on an unsecured network gives attackers a chance to intercept your credentials. Use your phone's cellular data instead, or connect through a VPN if you must use a public network. It is a small habit that prevents a lot of headaches. Review your transaction history at least once a month. Most people log in, check their balance, and close the tab. That is not enough. Skim through the last thirty days of activity and look for anything that does not match your memory. Set up alerts for transactions over a certain amount if you want an extra layer of monitoring.
There is also a feature called Regions Identity Guard that offers some identity theft protection services. It is an add-on, not free, and the coverage has limitations. It is not essential if you already use a dedicated identity protection service, but it is convenient if you want something integrated into your banking platform. Just read the terms carefully before subscribing. The cancellation process is not always intuitive.
What the Platform Cannot Do
Online banking will not replace a branch visit for everything. Cash deposits are not available through the digital platform. If you need to deposit cash, you have to go to an ATM or a branch. Some ATMs owned by other banks may accept cash deposits for Regions accounts, but the fees and processing times vary. This is a structural limitation of digital banking, not a Regions-specific problem. The wire transfer process through the online portal has strict cutoff times and maximum limits that vary by account type. Domestic wires typically need to be initiated by 2 PM Eastern to process the same business day. International wires have additional requirements and can take several days. If you are sending a large wire, call your branch ahead of time to confirm the details and ensure there are no holds or additional verification steps required. Account statements are available digitally, but if you need a certified copy for legal or loan purposes, the online system does not generate those. You need to request a certified statement from a branch representative. They can print and stamp it for you. This is a minor inconvenience that catches people off guard when they are in the middle of a mortgage application or an audit.
The search and filter tools within the transaction history are functional but not particularly powerful. You can sort by date and amount, and you can search by keyword, but you cannot create custom filters like transactions from a specific merchant category over a date range with a minimum amount. If you need detailed spending analysis, you will likely end up exporting your data to a spreadsheet or using a budgeting app that connects to your account through Plaid or a similar aggregator. The bottom line is that Regions Bank online covers the majority of everyday banking needs adequately. It is not the fastest platform on the market, and it is not the most polished, but it gets the job done for most account holders. The main things to watch out for are the joint account enrollment quirk, the Zelle irreversibility problem, and the fact that complex account structures require in-person assistance. Set up your alerts, enable two-factor authentication, and review your statements regularly. Everything else is just routine maintenance.


