So You Want to Understand Banco Rio and Brazilian Finance
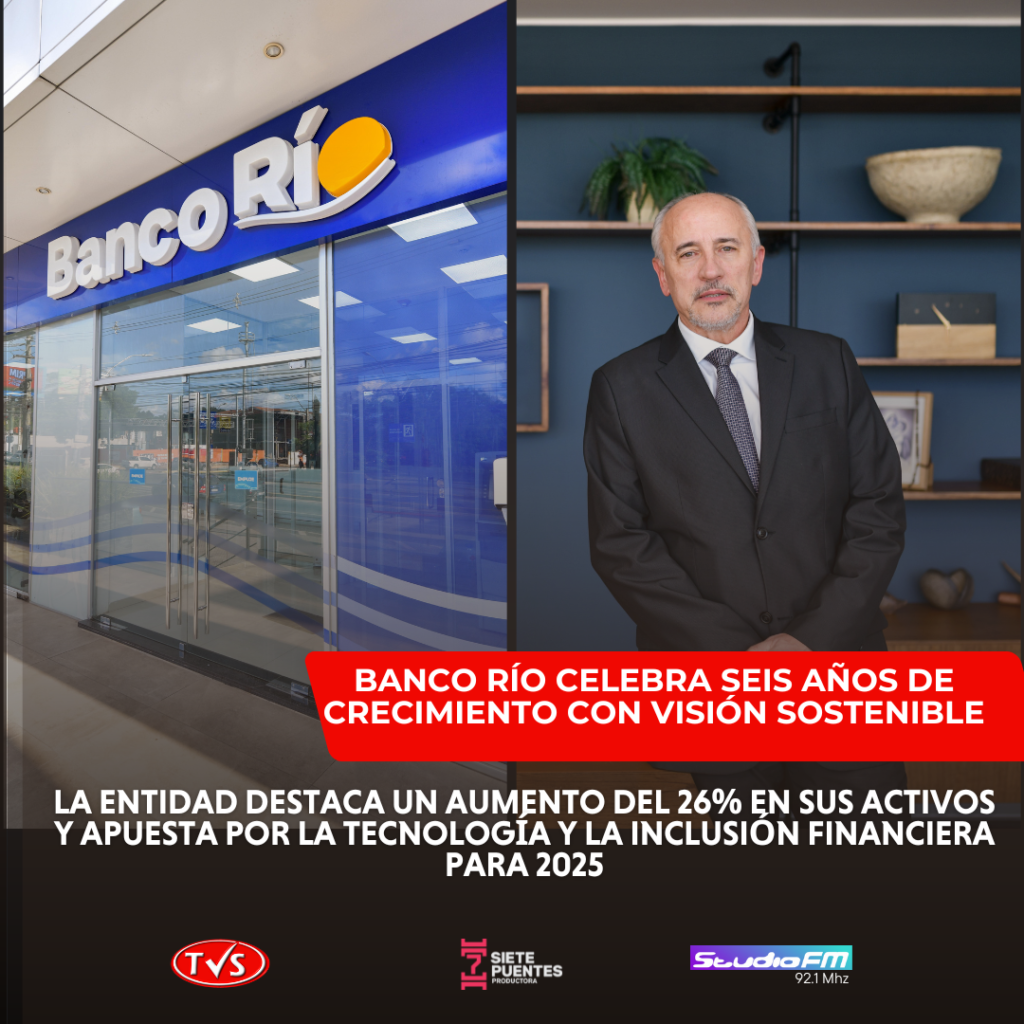
Banco Rio is one of the older private banks in Brazil, headquartered in Rio de Janeiro, and it has been around since 1963 when it was originally founded as Banco Rural. It went through ownership changes, got acquired by the Itaú group, and later rebranded. The bank operates mainly in retail and commercial banking across the Southeast region, but its reach extends further. If you are looking at Brazilian financial institutions from the outside, Banco Rio comes up because it sits at the intersection of traditional banking and the broader push toward financial inclusion that has been happening across Latin America over the last decade. The phrase gets tossed around a lot in investment circles, and honestly most people using it have not actually looked under the hood. What it really refers to is the combination of Brazil's large unbanked population, the growth of digital payment infrastructure like Pix, and how mid-sized regional banks are positioning themselves to capture that market without the baggage of the oversized national banks. Banco Rio is one example. It is small enough to move quickly, large enough to have compliance infrastructure, and embedded in a state with significant commercial activity. I spent about three years working on cross-border payment flows involving Brazilian accounts back in the late 2010s, and dealing with banks like Rio in that context was a lesson in how fragmented the system still is. The digital side has improved massively since Pix launched in 2020, but legacy account opening procedures, document requirements, and internal risk scoring models at these mid-tier banks still create friction. I once had a client try to set up automated recurring payments through a Banco Rio commercial account and hit a wall because their API documentation for transaction webhook notifications was incomplete and the support team pointed us to a outdated PDF from 2018. The workaround was to use the sandbox environment, confirm endpoint behavior through trial and error with three different transaction types, and then cache the webhook response structure locally before going live. That saved us about two weeks of back-and-forth that would have otherwise gone nowhere.
One thing most people miss about Brazilian banking is that the regulatory environment creates a weird incentive structure. The Central Bank of Brazil has been aggressively pushing for interoperability and open banking, which sounds good on paper, but the reality on the ground is that smaller banks often lack the engineering capacity to implement the APIs properly. So you get situations where the framework exists, the rules are clear, but the actual integration work is botched or half-finished. When you are evaluating whether a bank like Banco Rio can serve as a reliable conduit for capital flows or financial products, do not just look at their public digital offerings. Check their open banking participation tier, look at their actual API response times under load, and verify whether their compliance team is keeping up with recent regulatory changes around KYC and anti-money laundering reporting. These are the things that break deals months after they appear signed. Another counter-intuitive point is that Banco Rio's regional focus is both its strength and its limiting factor. The bank has deep relationships in Rio de Janeiro state, which means better underwriting decisions for local businesses and lower customer acquisition costs in that geography. But when you try to scale operations beyond that region or integrate with national-level fintech platforms, you run into capacity constraints. Their technology stack is not as mature as Itaú or Bradesco, and while they have been investing in digital channels, the pace of improvement does not match the speed at which the market is moving. If you are a small business owner in São Paulo or Brasília looking to bank with them, expect longer processing times and less intuitive digital tools compared to the digital-first banks like Nubank or Inter. The practical side of working with Banco Rio comes down to knowing when it makes sense and when it does not. For businesses already operating out of Rio de Janeiro with straightforward domestic transaction needs, it is a viable option, especially if you can negotiate relationship-based terms. For anyone trying to use it as a primary gateway for international operations or high-volume cross-border payments, you will likely need a secondary account at a larger bank anyway. The bank is not positioned for that scale.
If you want to explore their services, the main is through their official website at bancorio.com.br, where you can open retail accounts or apply for commercial products. There is no universal download link because banking apps vary by product type, but their mobile application is available on both the Apple App Store and Google Play under the name Banco Rio. Corporate clients should request direct access to their API documentation through a relationship manager rather than relying on public resources. The documentation quality gap I mentioned earlier is real, and having a human contact on your side makes a noticeable difference in implementation time. The broader story about Brazil's financial potential is not going away, but it is more complicated than the promotional language suggests. Banks like Banco Rio are part of the picture, but they are not the whole picture, and they have real limitations that become obvious the moment you try to use them beyond their comfort zone. Just keep that in mind before you commit any capital or build operational dependencies around them.
Get the Full Details