Mobile Home Financing Is a Different Beast Entirely
I spent four years working with manufactured housing lenders before I figured out the actual workflow. Most people treat mobile homes like regular houses and that's where everything falls apart. The paperwork, the appraisal process, the permitting - it doesn't map onto site-built housing at all. If you're looking into Pitts mobile homes specifically, you need to understand what you're actually dealing with before you sign anything. The short version is that Pitts has shifted their production model to focus on HUD-code construction with energy packages that actually compete with stick-built homes at roughly sixty percent of the cost. But the real story isn't the price tag. It's the delivery timeline. We're talking forty-five to sixty days from order to dry-in, not six to eight months like conventional framing. That alone changes the math on affordability when you factor in carry costs, temporary housing, and construction loan interest. Here's what nobody tells you about the process: the land question. You can buy a mobile home outright with cash and still not be able to place it. Zoning varies by county and most jurisdictions classify manufactured homes differently than site-built structures for setback requirements, foundation standards, and aesthetic covenants. I had a client last spring who signed a contract for a Pitts double-wide and then discovered the HOA in the community he'd selected prohibited any home built before 2010 on aesthetic grounds. The home was already being fabricated. He lost his deposit and spent three weeks scrambling to find a jurisdiction that would accept it.
The workaround is straightforward if you do it in the right order. Verify the placement site first, not after you've placed a deposit. Call the county building department and ask specifically about manufactured home placement requirements including foundation type approval, skirting regulations, and any local amendments to the HUD code. Then check the park or community rules in writing. Email the management office and ask for their current ownership policy. Keep that email. A verbal guarantee means nothing when the time comes to finance or resell. The financing piece is where most people get stung. Mobile homes built after June 1976 are considered personal property unless they're permanently affixed to a foundation and reclassified as real estate. That reclassification process - sometimes called annexation - varies by state and county. In Alabama, where Pitts is headquartered, the process is relatively clean. In other states it's a bureaucratic maze that can take six to nine months and requires a surveyor, a recorded declaration of affixation, and a separate title surrender at the DMV. Factor that into your timeline if you're counting on traditional mortgage rates rather than chattel loan rates, which run roughly two to three percentage points higher. On the construction side, Pitts has moved toward modular panelization rather than traditional stick framing in their plants. What that means practically is that exterior walls come partially assembled with windows and sheathing already installed. It speeds up the on-site assembly but it also means you can't easily modify floor plans once the order is placed. I've seen buyers try to negotiate mid-production changes - moving a load-bearing wall, adding a bathroom - and get shut down because the engineering package for that unit is already locked. If you want customization, do it during the selection phase, not after the order goes to the plant floor.
The energy efficiency angle is worth looking at closely. Newer Pitts models meet or exceed the 2015 Energy Code for manufactured housing, which includes requirements for thermal breaks in the floor system, higher R-values in walls and ceiling, and tighter ductwork standards. A properly sealed duct system in a manufactured home makes a huge difference because so much of the mechanical equipment lives in the conditioned space under the floor. I measured a before-and-after on a 2023 model where upgrading from single-pane to dual-pane windows and adding foam insulation to the perimeter skirt cut heating costs by about forty percent in a Florida climate. That's not a marginal improvement. That's the difference between affordable and unaffordable on a fixed income. There's a common misconception that mobile homes depreciate like vehicles. They don't, not when they're classified as real estate and maintained properly. A well-maintained manufactured home built after 2000 tends to appreciate at rates comparable to site-built homes in the same area, especially in markets where traditional housing supply is constrained. The depreciation narrative mostly applies to older homes placed in rental parks where the lot rent escalates faster than the home value. If you own the land, that dynamic flips completely. Inspection protocol deserves its own attention. Don't skip the pre-delivery inspection at the factory. I've seen multiple units ship with improperly seated window sweeps, missing vapor barriers at the skirting interface, and HVAC condensate lines installed without proper traps. These aren't catastrophic failures but they compound over time. A missing vapor barrier under the floor leads to moisture damage in the insulation, which leads to mold, which leads to a health issue and a replacement that costs more than the home itself. Getting the factory to remediate these issues before shipment costs them nothing in transport. Getting them to fix it after delivery means a service call, a wait, and a possible warranty dispute.
Get the Full Details

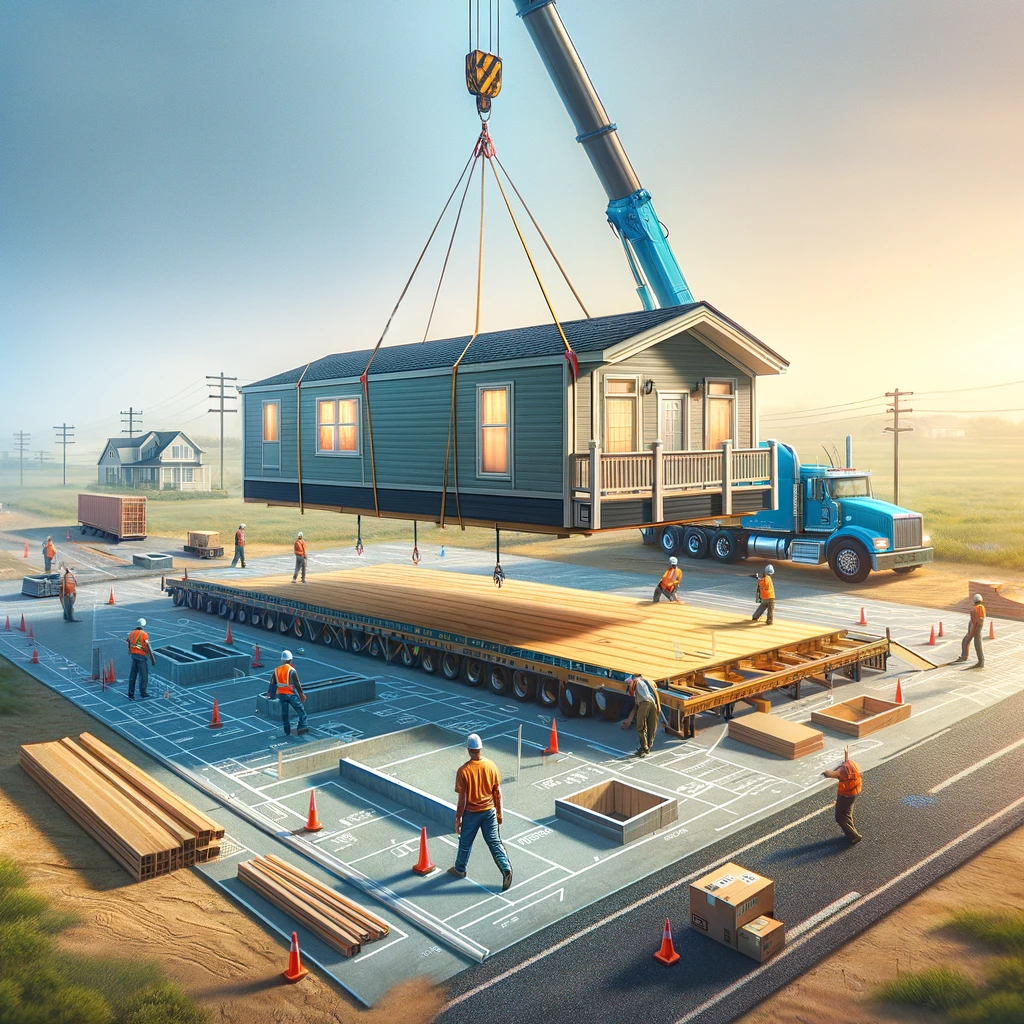
The permitting timeline is another variable people overlook. Even though the home is built to a federal standard, local jurisdictions still require permits for foundation, electrical tie-in, plumbing connections, and mechanical installations. In some counties this takes two weeks. In others it takes eight. The bottleneck is usually the plan review, not the inspection. Submit complete drawings with engineer-stamped foundation plans and you'll move faster than if you try to improvise the foundation details on site. I've seen contractors build foundations that don't match the engineering drawings and then fail inspection, requiring demolition and rebuild. That's a ten-thousand-dollar mistake on a home that's already behind schedule. Delivery logistics depend heavily on route accessibility. A double-wide requires two sections and each section is wider than a standard highway lane. Bridge heights, overhead wires, and narrow rural roads can add significant cost or make certain sites unreachable without temporary utility line relocation. Before you finalize a purchase, get the exact dimensions of your chosen model and run them against your site access route. A county road survey or even a satellite view measurement can save you from a fifty-mile detour and a crane lift that runs five thousand dollars extra. Warranty coverage on newer Pitts homes includes a structural warranty of up to seven years and a one-year comprehensive warranty on materials and workmanship. Read the fine print on what constitutes structural versus cosmetic. Cosmetic issues like drywall nail pops or trim gaps are typically handled under the one-year warranty and many buyers let those go unfixed because they assume it'll sort itself out. It won't. Settlement in the first eighteen months is normal and those nail pops will show up again in year three if you don't address the underlying fastening during the initial warranty period. Submit your warranty claims in writing with dates and photos. Verbal promises from the dealer carry no weight once the representative changes shifts.
The market context matters too. As of early 2024, the national average price for a new single-wide manufactured home sits around seventy-five to ninety thousand dollars delivered, while double-wides run roughly one hundred twenty to one hundred eighty thousand. Compare that to the median existing home price north of four hundred thousand and the affordability gap is stark. But the real constraint isn't the home price - it's the lot. In many markets there simply aren't enough available pads with approved utilities and zoning clearance. This is the bottleneck that determines whether mobile homes remain a viable strategy or stay confined to marginal locations. If you're evaluating this route, start with a site, not a showroom. Find the land or the lot with the paperwork in order, confirm the financing path for your specific situation, and then go talk to the dealer with that information in hand. The people selling these homes are used to buyers coming in with only the third piece of the puzzle. You'll move faster and make better decisions when you already know where the home is going to live and how it's going to be financed.