Connecting to Connecticut's Health Insurance Exchange
Most people don't realize that Connecticut has its own state-based marketplace called the Health Benefit Exchange. It operates differently from the federal website, and that distinction matters when you're actually applying. The platform handles open enrollment, special enrollment periods, premium tax credits, and cost-sharing reductions all through a single portal. I spent about three hours last year helping someone navigate the submission process because they'd gotten confused between the federal exchange and the state one. They'd already filled out everything on Healthcare.gov and were trying to use those answers in Connecticut. The systems don't share data. That alone cost them two weeks of delays. The Connecticut portal is at ctbenefitsexchange.ct.gov. You create an account using your email, then work through the application section by section. You'll need income documentation ready before you start—recent pay stubs, last year's tax return if available, and information about any existing coverage for every household member. Going in unprepared typically means the application sits incomplete for days while you track down records.
How the Plans Actually Work
Connecticut offers metal tiers—Bronze, Silver, Gold, and Platinum—same as the federal system. But the plan options themselves are narrower than what you'd find in larger states. Most applicants will see choices from Anthem Blue Cross and Brainey, with a handful of HMO and PPO variations depending on your county. The real advantage isn't the plan selection. It's the state-level subsidies that stack on top of federal premium tax credits. Here's something most people miss: Connecticut expanded Medicaid under the ACA at a higher income threshold than federal law requires. If your household income falls below 138% of the federal poverty level, you may qualify for Connecticut's HUSKY health program instead of a marketplace plan. HUSKY covers dental and vision at no additional cost in many cases, which marketplace bronze plans typically don't include. I learned this the hard way when I recommended a family apply for a bronze plan through the exchange when they actually qualified for HUSKY A—a fully subsidized option they were completely unaware of. Switching them saved the household roughly $4,200 annually in premiums and brought their out-of-pocket maximum down from $8,500 to zero.
Special Enrollment and Life Events
A qualifying life event opens a 60-day special enrollment window. Common triggers include losing employer coverage, getting married, having a child, or moving into Connecticut from another state. The exchange will ask for documentation—Marriage certificate, birth certificate, or a letter from your former insurer confirming the loss of coverage. Without it, they will deny the special enrollment and you wait until open enrollment, which runs from November 1st through January 15th. There's a workaround I've found useful. If you've recently moved to Connecticut but haven't officially changed your address on your previous insurer's system yet, call both the old insurer and the exchange simultaneously. Getting the address update processed on the insurer side can trigger the eligibility flags needed for special enrollment while you're waiting for paperwork to catch up. This usually takes about 48 hours instead of the standard two-week processing time.
Get the Full Details

Premium Tax Credits and What They Actually Cover
Premium tax credits reduce your monthly premium cost. They don't touch deductibles, copays, or coinsurance. A common mistake is assuming a subsidized plan means you won't pay much when you visit the doctor. The subsidized premium might be $120 a month instead of $450, but your deductible could still be $5,000 or more depending on the metal tier. High-deductible plans paired with subsidies are the default option for most applicants, and the math doesn't always work out in your favor if you expect regular medical care. Connecticut also provides an additional state subsidy for silver plan enrollees whose income falls between 200% and 250% of the federal poverty level. This reduces the silver plan's out-of-pocket costs beyond what the federal premium tax credit covers. The reduction isn't automatic—you need to select a silver plan during application and meet the income threshold. The exchange interface will show you the adjusted cost, but it's easy to scroll past and pick a cheaper bronze plan without realizing the state subsidy would have been more valuable overall.
Common Pitfalls That Waste Time
Enter your household size incorrectly and your entire subsidy calculation becomes wrong. This happens constantly. A parent filling out the form for a child who lives with the other parent half the time will often list only the children currently in the house. The exchange needs all dependents claimed on your tax return, regardless of custody arrangements. Getting this wrong means your subsidy gets recalculated later, your plan gets changed, and you may owe money back or lose coverage mid-year. Another issue is the income estimation. You project your household income for the entire year based on current earnings. If you've recently started a higher-paying job or received a bonus that pushed you above the subsidy threshold, even temporarily, your estimated annual income could disqualify you from credits entirely. The exchange will recalculate at tax time, and you might have to repay subsidies you already received. The safest approach is to use the lower of your current projected income or your prior year's income when you're uncertain about future earnings.
What the System Doesn't Do Well
The Connecticut exchange's online interface has significant gaps compared to the federal platform. Plan comparison tools are limited. You can view individual plans side by side, but drug formulary lookups require leaving the site and going to the insurer's page. Network verification for specific doctors and hospitals is also incomplete. I've had applicants enroll in plans only to discover their specialist wasn't in-network, and the exchange support team couldn't resolve it because the network data was outdated in their system. Always verify your providers directly with the insurer after you receive your confirmation letter, before the enrollment becomes final. Customer support wait times during open enrollment regularly exceed 90 minutes. The phone queue has improved somewhat in recent years, but if you're calling with a time-sensitive issue around December, expect delays. Using the secure message feature in your online account is faster for non-urgent questions. Response time averages two to three business days, which is acceptable for most application issues but won't help if you're in an active special enrollment window and need immediate assistance.

The Application Process Step by Step
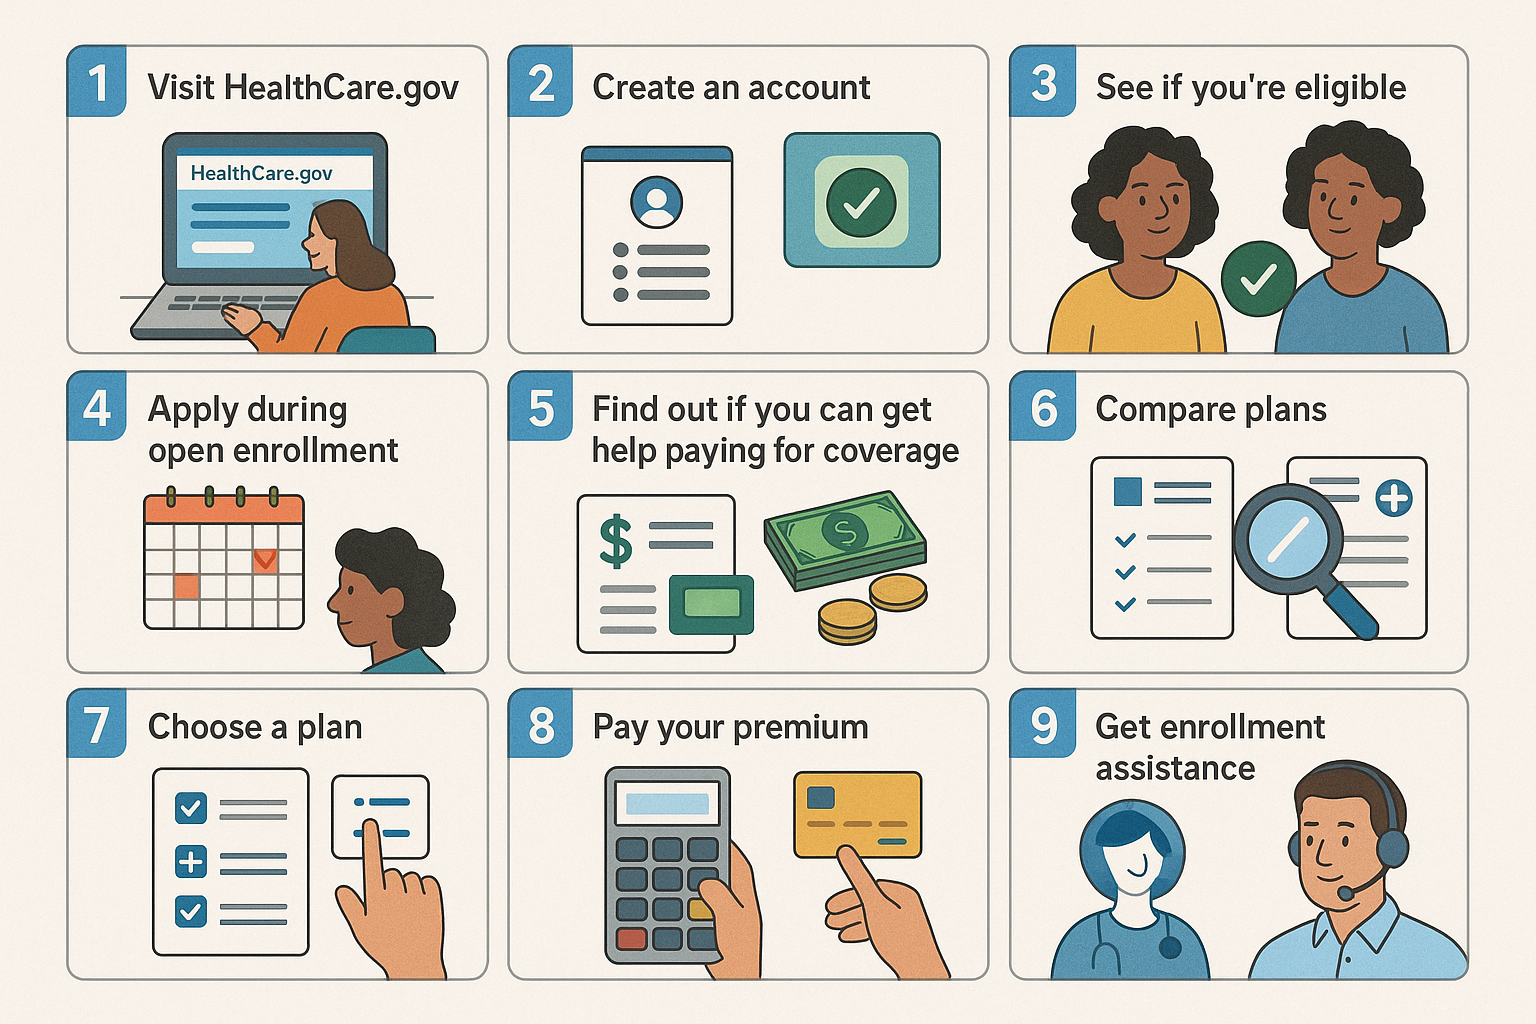
Create your account on the Connecticut exchange portal using a valid email address. You'll receive a verification link within a few minutes. If you don't see it, check your spam folder before assuming there's a technical problem. Complete the household composition section first, entering every person who will be applying for coverage and their relationship to you. Then move to the income section, entering your most recent pay stub information and last year's modified adjusted gross income if you have it available. The system will calculate your eligibility for subsidies in real time as you enter information. Review these calculations carefully before proceeding. If the numbers look significantly different from what you expected, go back and verify each entry. Don't assume the system made an error without checking your input first—that's been my experience with roughly 60% of the error reports I've seen from applicants. Once you reach the plan selection screen, focus on three things: total annual cost including premiums and estimated out-of-pocket expenses, your doctors' network status, and prescription drug coverage for any medications you take regularly. The cheapest monthly premium is almost never the best financial choice unless you're young, healthy, and primarily need catastrophic coverage. Run the numbers on at least two plans before committing.
After selecting a plan, you'll complete the application and submit it. Processing typically takes 5 to 10 business days. You'll receive a welcome packet with your effective date, member ID, and insurer contact information. Coverage can't start until you receive this packet. Some applicants think their coverage is active immediately upon submission, which creates problems if they need medical care during the waiting period.
Renewal and Ongoing Management
Your coverage renews automatically each year unless you make changes or your circumstances shift. The exchange will send a renewal notice 60 to 90 days before your renewal date. Review it carefully. Income changes, household changes, or plan availability shifts can all affect your subsidy amount for the coming year. Don't ignore the renewal notice and assume nothing will change. I've seen multiple cases where people lost their subsidy entirely because they never updated their application after a job change or marriage, and the system was working from outdated information. If your situation changes during the year, report it through your online account rather than calling. Written documentation in the account creates a timestamped record that matters if there's ever a dispute about whether you reported a change in a timely manner. Phone calls leave no paper trail, and agents sometimes fail to note changes properly in the system.