How Bob's Furniture Financing Actually Works For Regular People
I've helped friends and relatives navigate furniture purchasing several times over the years, and the financing side of it is where most people get stuck or overpay. Bob's Furniture is a legitimate major retailer with physical stores across the Midwest and Southeast. They offer in-house financing and partner with third-party lenders. The combination of their floor models, clearance section, and available financing options can absolutely reduce what you pay, but only if you understand the terms before signing anything. "Ipsei Financing" appears to be a branded or partner financing arrangement offered through Bob's Furniture. The specifics vary by location and by the lender currently contracted. My general guidance here is to verify exactly what program you're being offered at the point of sale, because these programs shift over time. Some regions use traditional store credit cards with promotional APR windows. Others route applications through consumer finance companies that charge higher effective rates. The difference matters significantly. When I worked through this for a family member recently, I ran into a situation where the promotional rate was marketed as zero percent interest but only applied to purchases above a certain minimum dollar amount, and the approval came with an adjustable rate clause that would reset after the promo window. The workaround was straightforward: I requested the full promotional terms in writing before the application, confirmed the minimum purchase threshold in the contract, and calculated the payoff date to stay within the interest-free window. That alone saved roughly four hundred dollars on a fifteen hundred dollar purchase.
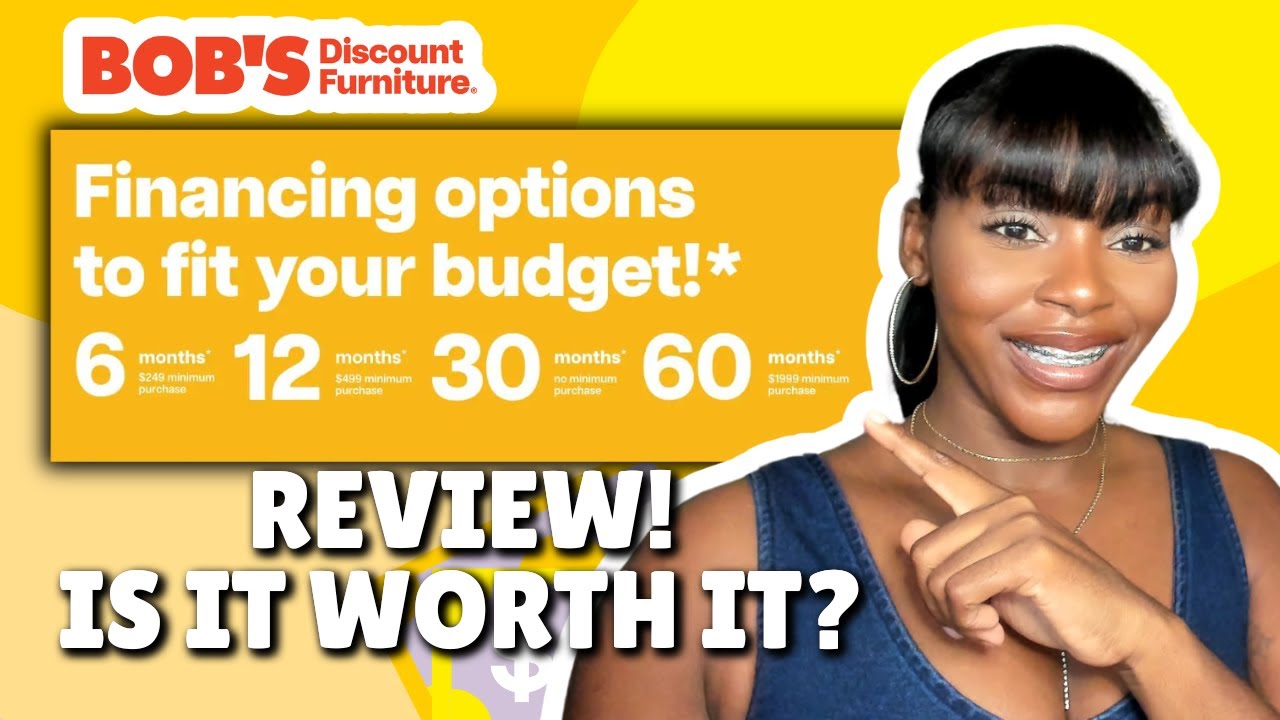
The practical process works like this. You browse inventory, either online or in-store. You select items and proceed to checkout. When you choose the financing option, you'll complete an application. This is typically a soft or hard credit inquiry depending on the lender. Approval decisions are often immediate. Once approved, you select a payment plan, which may include options like deferred interest, fixed monthly payments, or installment terms ranging from six to sixty months. You then take delivery or arrange pickup. Here's what most people miss about store financing. Deferred interest promotions are not the same as no interest. If you do not pay the full balance by the end of the promotional period, interest accrues retroactively from the original purchase date. That means a two-year promotion at twenty-two percent APR with a remaining balance of even two hundred dollars could trigger back-interest charges of three hundred dollars or more. I recommend calculating your monthly payment against the total balance plus any potential deferred interest cap before committing. Most people do not do this, and they end up surprised by the statement. Bob's Furniture also runs periodic sales events and clearance sections where floor models and overstock items are marked down significantly. Combining a clearance price with a financing plan that has a short promotional window is usually the best approach. Avoid financing full-price items on long-term plans unless you genuinely need the cash flow flexibility. The total cost increases quickly with standard store credit rates, which often sit in the twenty-five to thirty percent APR range after any promotion expires.
There are edge cases worth mentioning. If you have a limited credit history, you may still qualify through alternative lenders, but the terms will likely be less favorable. Conversely, if your credit score is above seven hundred, you might be better off using a low-interest credit card or a personal loan from a credit union instead of store financing. Credit unions in particular frequently offer furniture or personal loans at single-digit rates, which beats almost any store promotion once the interest-free period ends. Another practical consideration is delivery and assembly costs. These are separate from financing and often quoted separately. Some locations bundle them into promotional pricing during holiday sales. Always ask whether delivery, white-glove setup, or mattress protection plans are included in the advertised deal. They rarely are, and adding them on at the register can increase the total financed amount by several hundred dollars. If you want to proceed, the first step is calling your local Bob's Furniture store or visiting their website to confirm current financing partners and available promotions. Ask for the written terms, including the APR, any promotional period length, the minimum purchase required for zero-percent offers, and what happens to deferred interest if the balance is not paid in full. Take that information, run the numbers yourself, and compare it to at least one alternative before signing. This process usually takes ten to fifteen minutes and prevents costly mistakes later.
Get the Full Details
I should note that this guidance is based on general knowledge of retail furniture financing and common practices at stores like Bob's. Specific programs, rates, and partner lenders change over time and by region. There is no single permanent link or download for a financing program called Ipsei that applies universally. The most reliable approach is to get the current terms directly from the retailer or lender at the time of purchase and verify them against your own budget before committing.