Biweekly Paychecks in NYC Are Messier Than People Think
Most people get their first NYC paycheck and stare at it wondering where half their gross salary went. That's not unusual. New York City has its own local tax layer on top of state withholding, and the feds take their cut too. Throw in pre-tax deductions like 401k contributions, health insurance premiums, and optional items like dependent care FSAs, and you've got a calculator problem that's harder than it looks to solve by hand. I spent years working payroll at a mid-size firm in Manhattan. One of my recurring headaches involved a salaried employee whose biweekly estimate came out $40 short because we hadn't accounted for her NYC school tax credit being partially phased out based on her adjusted gross income threshold. A generic online calculator would've given her the standard number. A proper tool that factors in the actual NYC tax brackets and phase-outs gets you closer. I ended up building a spreadsheet that cross-referenced the NYS and NYC tax tables side by side, then reconciled it against our payroll software output every month until it matched. That process took me about three weeks to dial in, and it cut our monthly reconciliation time from two hours down to maybe twenty minutes.
Unlock Your Takehome Pay NYC Salary Calculator Biweekly Paycheck Estimator Revealed
The calculator works by taking your annual salary, dividing it into 26 biweekly periods, and then running that gross amount through the relevant tax brackets for federal income, New York State income, and New York City income. It also applies FICA — Social Security at 6.2% and Medicare at 1.45% — along with any pre-tax deductions you list. The result is your estimated net pay per paycheck. Here's what most people miss about how it actually works under the hood. The NYC personal income tax uses its own bracket structure that doesn't perfectly align with the state brackets. For 2025, the top NYC rate kicks in at a much lower income threshold than the top NYS rate. That means two people earning the same salary in different cities could owe dramatically different amounts in local tax, even though their state tax is identical. The calculator needs to apply the correct city bracket independently, not just estimate it as a flat percentage of state tax. Another thing that trips people up: the filing status matters more than you'd expect. If you're married and both spouses work in NYC, the joint withholding calculation can shift your effective tax bracket differently than if you file separately. A lot of estimators assume single filers and that throws the numbers off by a noticeable margin for married couples, sometimes by over $100 per paycheck depending on the combined income level.
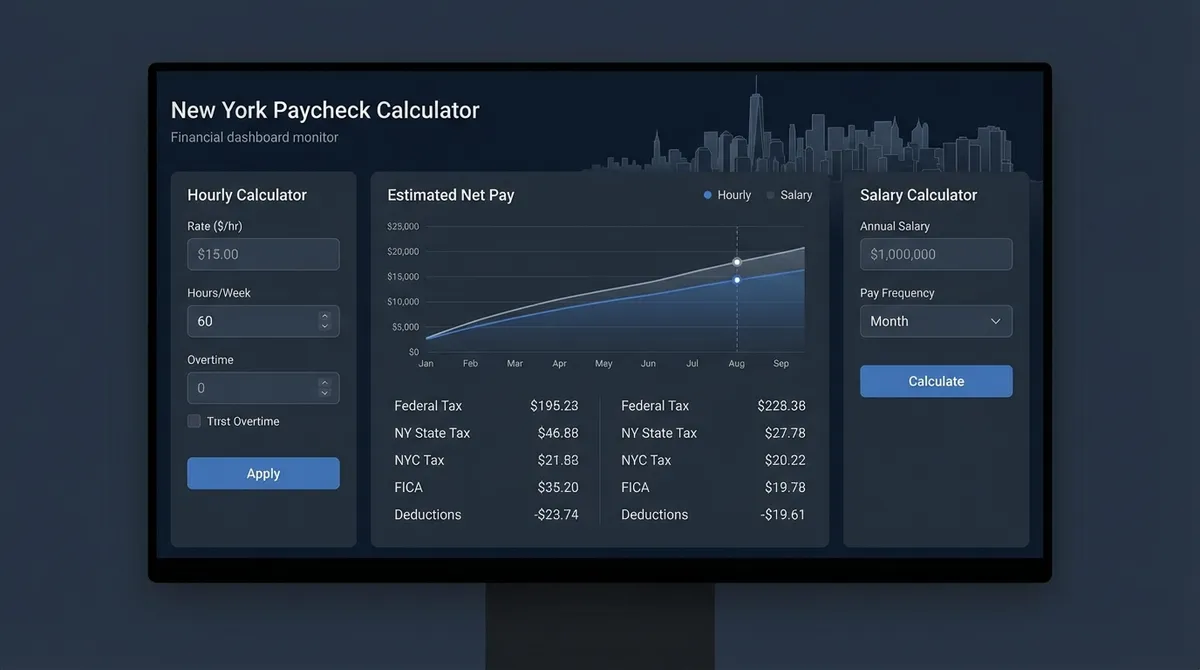
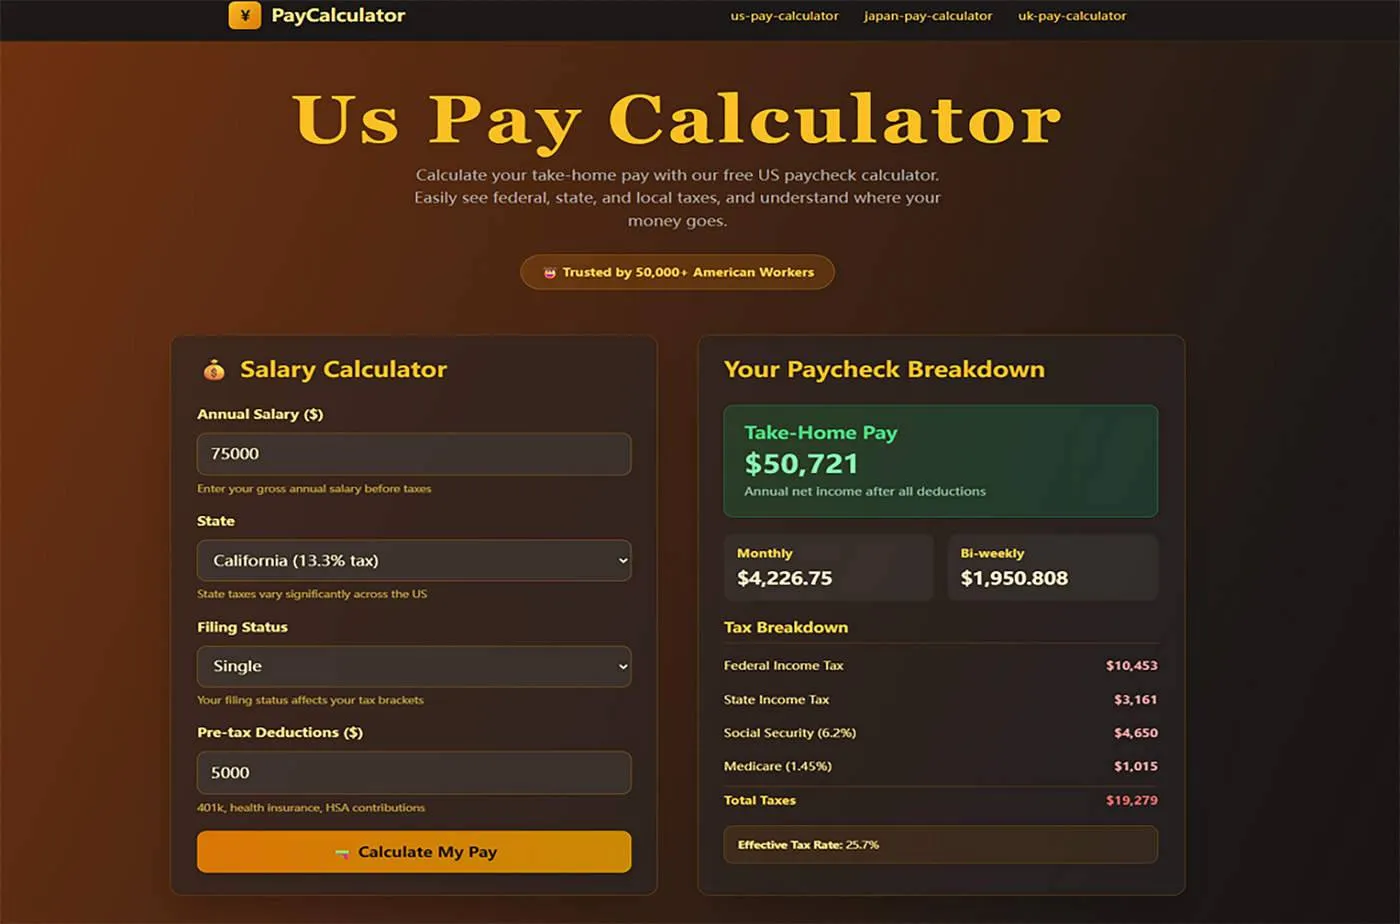
To use the tool, you enter your gross annual salary, select biweekly as the pay frequency, choose your filing status, and input any pre-tax deductions like retirement contributions or health insurance premiums. Some versions also let you add W-4 allowance adjustments or specify whether you have additional withholding requests. The output shows your estimated federal tax, state tax, city tax, FICA, total deductions, and net pay. I ran into a specific edge case last year that exposed a real limitation in most of these calculators. An employee had a significant amount of bonus income bundled into a single biweekly check using the aggregate withholding method. The standard estimator would calculate taxes on that lump sum as if it were regular pay, which over-withheld dramatically because the bonus pushes the total into a higher bracket for that period only. The workaround was to manually separate the bonus calculation and apply the percentage method specifically for supplemental wages, which uses a flat 22% federal rate instead of the progressive bracket approach. Without doing that, the estimate was off by roughly $300 for that particular paycheck. Most free calculators don't handle this distinction at all. There are also limitations you should be aware of. These calculators are estimates, not guarantees. They don't account for the additional 0.9% Medicare surtax that kicks in above certain income thresholds, nor do they typically factor in the New York City college tuition credit or the earned income credit which can reduce your city tax liability. If your income puts you near the Medicare surtax threshold, the estimate could be off by several hundred dollars annually. Similarly, if you're claiming the NYC tuition credit, your actual take-home will be higher than what the calculator shows.
Get the Full Details

For most people making a typical salary in NYC, the tool gives you a reasonably accurate picture within a 5 to 10 percent margin. If you need precision — say you're planning a mortgage application and the lender wants to see exact numbers — you should pull your actual pay stubs and reverse-engineer the withholding from there rather than relying solely on an online estimator. You can also use your most recent W-2 from last year as a baseline and adjust for any changes in your filing status or deduction amounts this year. The bottom line is that biweekly pay in NYC involves more moving parts than most workers realize. The calculator is useful for getting a general sense of where your money is going, but it won't replace looking at your actual pay advice document or consulting a payroll professional if your situation involves bonuses, multiple jobs, or complex deduction scenarios. Just feed it your numbers, read the output, and remember that the final answer lives on your pay stub, not in the estimate.