What Credit Unions Actually Do Differently From Banks
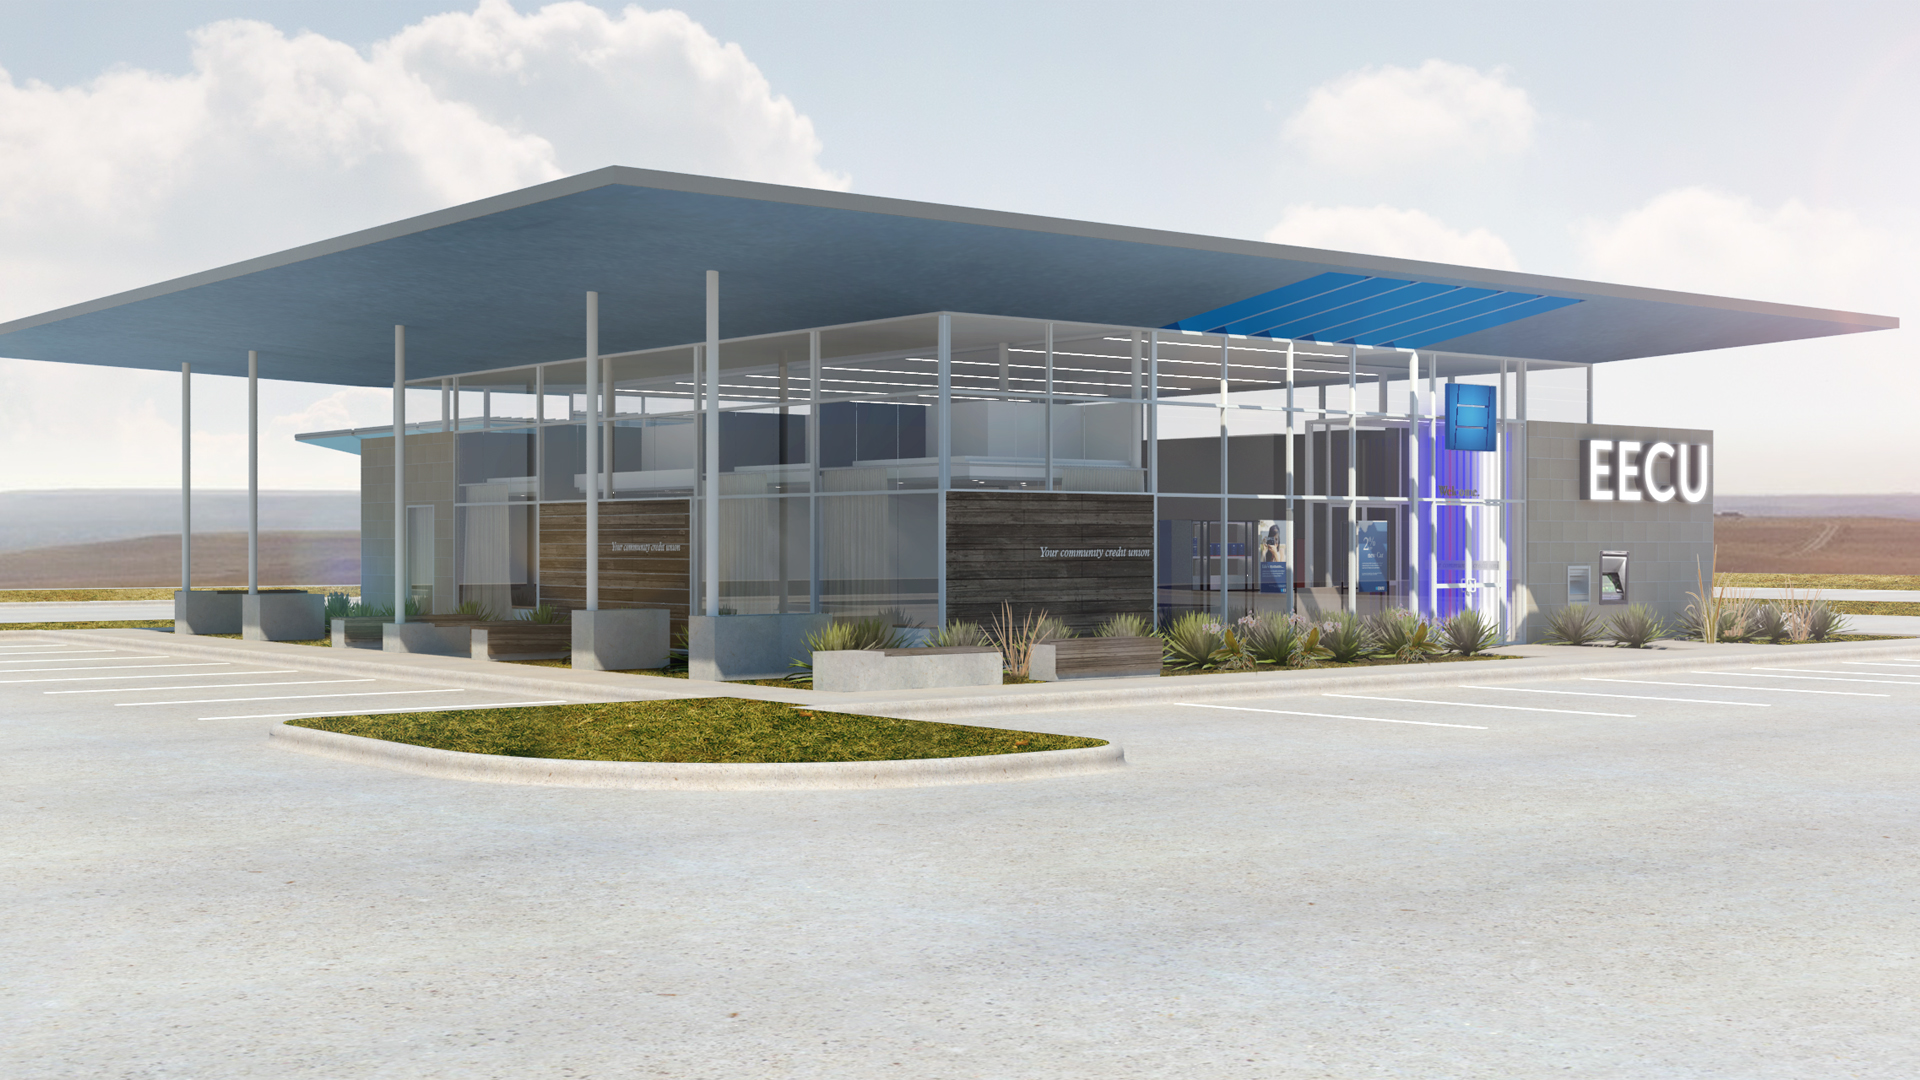
I spent seven years working operations at a mid-size credit union before moving to a community bank, and the difference in how they structure products is real. It isn't a marketing slogan. It shows up in rate spreads, fee structures, and the way loan approvals are actually evaluated under the hood. If you have been scrolling through ads for EECU Financial Center and wondering whether their advisory services are worth the time, I can walk you through what that actually looks like in practice. EECU stands for Education Employees Credit Union, and it is one of the larger member-owned credit unions in the United States, headquartered in North Carolina. Their expert advice and innovative solutions angle mostly comes down to three things: their digital banking platform, their financial counseling resources, and the member dividend structure that comes from being a cooperative. None of that is unique to them, but the combination matters when you are actually trying to manage your money day to day. Here is how I would approach using their resources if you were a new member or thinking about switching. First, you need to understand membership eligibility because it is not open to just anyone. You qualify through employment in certain North Carolina school districts, membership in partner organizations, or by living in specific counties. If you try to open an account outside those boundaries, the system will reject you during verification. I have seen people waste two weeks trying to force this through customer service before realizing they did not meet the geographic or employment criteria. There is no workaround for that one. The membership screen is hard-coded.
Once you are in, the first thing to set up is direct deposit. It is the highest leverage move you can make in the first thirty days. EECU offers a bonus checking structure that requires a minimum of $2,000 in qualifying direct deposits per month to waive the base fee and earn the higher dividend rate. If you miss a month, the fee comes back retroactively. I learned this the hard way in 2019 when my payroll department processed a bonus payment as a one-time transfer instead of recurring direct deposit. The system did not count it. That cost me about forty dollars in fees that month. Make sure your employer sets it up correctly the first time, and verify it hits in the first payment cycle by checking your transaction history within forty-eight hours of payday. Their financial counseling component is where most people overlook the actual value. EECU provides free one-on-one sessions with certified financial counselors for members. This is not a sales call. It is a legitimate service that includes budget analysis, debt repayment planning, and homebuyer guidance. The catch is that you have to actively book these appointments. They do not auto-assign them. I used this service when I was consolidating student loans and comparing refinance options, and the counselor pulled my actual transaction data from the past twelve months to build a cash flow projection. That took about twenty minutes of my time and probably saved me from locking into a bad refinancing term. The session runs roughly forty-five minutes, and you can book through the mobile app or the website. I recommend going in with your top three financial questions written down before the call. Otherwise, the conversation drifts into generic territory and you leave without concrete next steps. Their mobile app has some features that are worth knowing about. They offer a tool called MyPlan that lets you set savings goals with automated micro-transfers. It pulls spare change from your checking and moves it into a savings bucket labeled for the goal. The algorithm uses your recent spending patterns to estimate how much it can safely move each week without overdrawing. It is not perfect. I found that during months with unusually high variable expenses, the app still estimated aggressively based on prior months, which occasionally left my checking account uncomfortably thin. The workaround is to pause the automation manually during high-spend months and resume it once your balance stabilizes. It takes three taps in the app. Nobody warns you about that behavior in the marketing material.
On the lending side, EECU's auto loan rates are competitive but not always the lowest available. I compared their 2024 auto financing rates against three other lenders for a borrower with a 720 credit score, and EECU came in roughly ten to fifteen basis points above the lowest option. That sounds small, but on a twenty-five thousand dollar loan over six years, it adds about two hundred dollars in total interest. The tradeoff is their pre-approval process, which is faster than most banks and does not require a hard credit pull until you accept the final terms. If speed matters more than squeezing every basis point, their auto lending is reasonable. If rate is everything, shop two or three other credit unions first. Home mortgages are another area where the member structure creates a meaningful difference. Credit unions typically offer lower closing costs and more flexible underwriting than big banks, especially for borrowers with non-traditional income sources. EECU's mortgage team works with self-employed members more often than I see at commercial banks. One edge case I encountered involved a freelance graphic designer who could not provide traditional W-2 verification. The bank she approached declined her application on that basis alone. EECU reviewed her tax returns from the previous two years, her client contracts, and her bank statements to verify income stability. She got approved. That is the kind of flexibility that comes from a cooperative model evaluating the whole picture rather than running everything through a strict algorithmic gate. It is not guaranteed. Some EECU mortgage officers still default to the same rigid criteria. You have to specifically request a manual underwriting review if your situation is non-standard. There are downsides to mention because the promotional language glosses over them. EECU's branch network is concentrated in North Carolina. If you live outside that state, you are dealing with a remote-only relationship for most services. Online bill pay works fine, but if you need to deposit a physical check in person or resolve a fraud dispute face to face, you will either drive to a branch or go through their phone support, which can take twenty to thirty minutes on hold during peak hours. I called once about a disputed ATM transaction and waited forty-two minutes. They eventually resolved it, but the delay meant my account was overdrawn for three days because the hold on the disputed charge had not been reversed quickly enough. Their fraud dispute timeline is standard for the industry, around ten to fifteen business days for provisional crediting, but it feels longer when your paycheck is on hold.
Get the Full Details
Another limitation is their investment offerings. EECU does not offer a full brokerage platform. They partner with third-party providers for retirement accounts and basic investment products, but you will not find the same depth of options as a dedicated wealth management firm. If you are building a diversified portfolio beyond a basic Roth IRA, you will likely need to use a separate provider anyway. Their financial counselors can guide you on allocation strategy, but they do not execute trades or manage accounts. That is a boundary you need to accept upfront or plan to supplement elsewhere. The dividend structure deserves a clear explanation because people confuse it with interest. When EECU pays dividends on your savings and share accounts, it is returning a portion of the credit union's profits to members. It is not guaranteed. The board of directors declares dividend rates quarterly based on earnings. In strong years, savings dividends have been around four to five percent. In tighter years, they drop. I watched my savings dividend rate fall from four point seven five percent to three point two five percent between 2022 and 2023 as the broader credit union environment adjusted to rising operational costs. It is still competitive with most big bank savings accounts, but it is variable and you should budget assuming the lower end, not the advertised high. If you are trying to actually unlock financial potential through this kind of institutional advice, here is the practical sequence that works. Open the account and verify your membership within the first week. Set up direct deposit and confirm it clears on time. Book a financial counseling session within your first sixty days and bring your debt statements, credit report, and a list of short-term goals. Pause any automatic transfers during months with irregular expenses. Monitor your dividend rate each quarter and reassess whether your savings strategy still makes sense if the rate shifts significantly. Compare your auto and mortgage rates against at least two other lenders before committing, even if EECU's convenience is appealing. Keep a manual log of your disputed transactions if you ever file one, because the process moves slower than you want it to.
I have watched people treat credit union resources as background noise and then wonder why their financial situation did not improve. The services exist. They are free for members. The problem is that nobody hands you a checklist and tells you the order to use them. Once you figure out the sequence, the time investment is manageable. The real value comes from the structured guidance, not from the individual features acting alone.