Budgeting apps in the Philippines: what actually works after trying dozens
Most people download a finance app and then abandon it within three weeks. I've seen it happen on forums for years. The problem isn't usually the app itself—it's that the app doesn't match how money actually moves through Filipino households. You get a monthly salary, some of it goes to bills, some disappears into GCash, some to Maya, some to your sari-sari store tab, and then there's the jeepney fare and the online shopping you swore you'd stop doing last week. I spent about two years tracking my own spending across multiple platforms before settling on a setup that actually sticks. Here's what I learned.Unlock Your Financial Freedom Top Budgeting Apps In The Philippines
Let me start with the blunt truth: no single app perfectly handles the Philippine spending ecosystem. What works depends entirely on how you get paid, where you spend, and whether you're willing to do manual entry or need automation. YNAB (You Need A Budget) is the most disciplined option if you can stomach the learning curve. It uses zero-based budgeting—you assign every peso a job before the month starts. I used it for eight months in 2022. It forced me to stop treating my salary as one big pool of money I could dip into randomly. The downside: it's American-centric. Bank syncing for BDO, BPI, and Metrobank doesn't work out of the box. You enter transactions manually or import CSV files. That takes about 10–15 minutes a day if you're fast, 30 minutes if you're careful. The app costs $14.99/month or $99/year. For some people that's expensive. For others it's the only thing that stopped them from overspending. Mavin is a local option that actually understands Philippine income patterns. It connects to GCash, Maya, and several local banks through open banking APIs. I tried it in early 2023 when I was trying to track side income from freelance work alongside my main salary. The auto-categorization caught about 70% of my transactions correctly. The rest I fixed in bulk at the end of each week—usually takes me about 20 minutes. Mavin's strength is that it shows you cash flow across all your accounts in one view, which is genuinely useful when you're juggling three or four payment platforms like most Filipinos do.
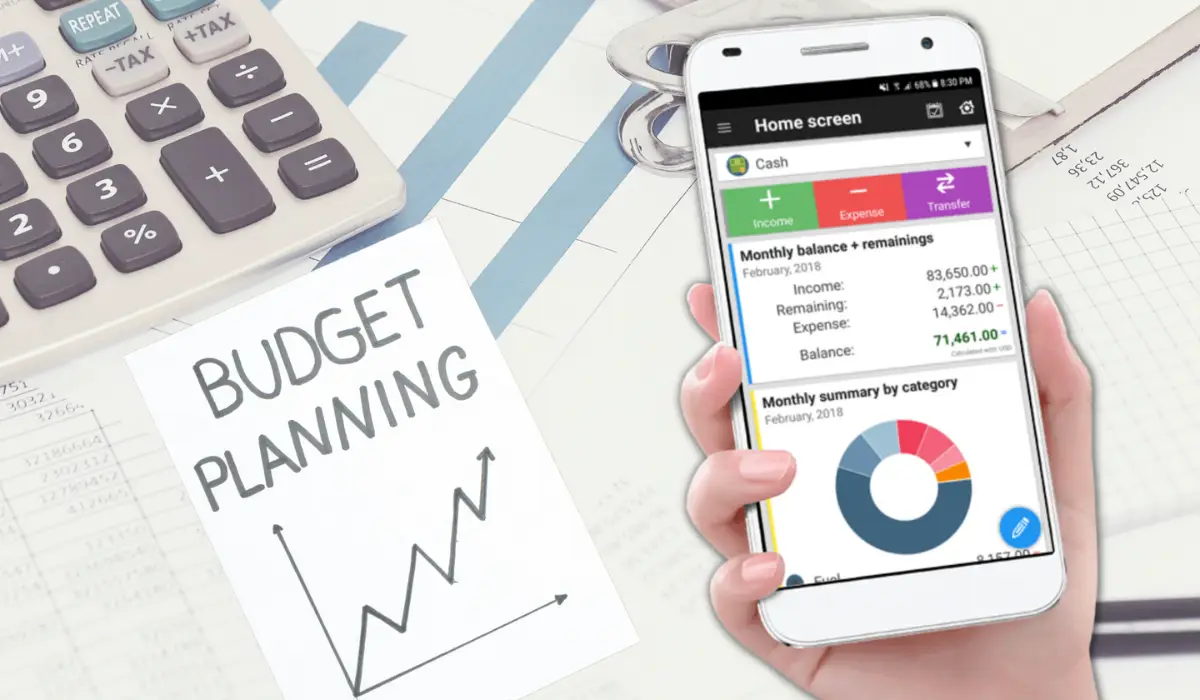
Money Manager Expense & Budget by Realbyte is the free option I keep coming back to for casual tracking. It doesn't sync with banks automatically in the Philippines, so it's manual entry only. But the interface is fast, the categories are flexible, and it runs well on older Android phones that cost under 5,000 pesos. I used this during a period when I was living on a tighter budget and needed to track every single peso without paying for a subscription. The one thing it does well that others don't: you can set up custom accounts for cash envelopes, which matters if you still carry actual money around. Spendee is worth mentioning if you share finances with a partner or family member. The shared wallet feature actually works. My sister and I used it to track our trip to Boracay together, splitting expenses that got complicated with multiple merchants and split payments. It's available on iOS and Android. The free version limits you to two wallets. The premium version at about $3/month removes that limit and adds joint budget goals. Here's something most reviewers miss: the app that works best for you depends heavily on whether you receive your salary via bank transfer or get paid in cash. If you're paid cash—common in construction, retail, and many BPO roles—the apps that promise automatic bank syncing are basically useless to you. Mavin and Money Manager let you log cash withdrawals separately. YNAB forces you to be explicit about it, which is actually healthier for your relationship with money even if it's more work.
I ran into a specific problem with Mavin in mid-2023 that took me about three hours to resolve. The app's connection to BDO kept dropping whenever I had transactions above 50,000 pesos in a single day. Turns out BDO's API has rate limits that Mabin hasn't fully worked around. The workaround: I split my large transfers into smaller batches throughout the day and manually confirmed the categorization afterward. It's not elegant, but it's the only way to keep the data accurate without switching banks entirely. Another counter-intuitive thing I discovered: the more automatic an app is, the less you actually learn about your spending. When I switched from Mavin's auto-sync to YNAB's manual entry, I caught spending patterns I'd been blind to. Transactions that Mavin categorized as "food" were actually split between groceries, fast food, and coffee shops—and I was spending twice as much on coffee as I thought. Manual entry forces you to look at every transaction. It's slower, but it builds awareness that automatic categorization skips over. If you're starting from zero and have no budgeting experience at all, I'd suggest this sequence. First, use Money Manager or Spendee's free version for one month with manual entry. Just record everything. Don't try to optimize. Second, switch to Mavin if you want automation and have enough bank-linked transactions to make it worthwhile. Third, if you find yourself consistently overspending or can't stick to a plan, try YNAB for a trial month. The $99/year commitment forces you to take it seriously, and that accountability is part of why it works for people who need it.
Get the Full Details
The apps I listed above are available on the Apple App Store and Google Play Store. Search by name—none of them have unique URLs worth linking directly since they change frequently and the stores are the reliable source. One final note: none of these apps will fix a structural income problem. If you're making less than you need to cover basic expenses, budgeting is just a more precise way of tracking how fast you're running out of money. That's uncomfortable but honest. Apps help you optimize what you have. They don't create income. If your situation is that dire, the priority should be income generation or expense reduction through non-app methods—negotiating bills, finding cheaper housing, picking up extra work. The app comes after you've stabilized the basics.