Getting Into Your Discover Card Account
I still remember the first time I tried to log into my Discover account after switching browsers. The two-factor authentication code arrived three minutes late, the session timed out, and by the time I figured out I needed to re-enter my security question instead of just clicking retry, I had already spent twenty minutes doing nothing productive. That was back when I was still treating login issues as mysteries rather than processes I could predict. Most people never think about their credit card portal until they need it. They check statements at least once a month, maybe log in weekly when they want to make a payment or see a reward balance. But there is a difference between opening the site and actually using it effectively. Discover has built something reasonably functional, though it has quirks that drive regular users crazy if you do not know them.
Unlock Your Discover Card Account The Ultimate Guide To Wwwdiscovercardcom Login
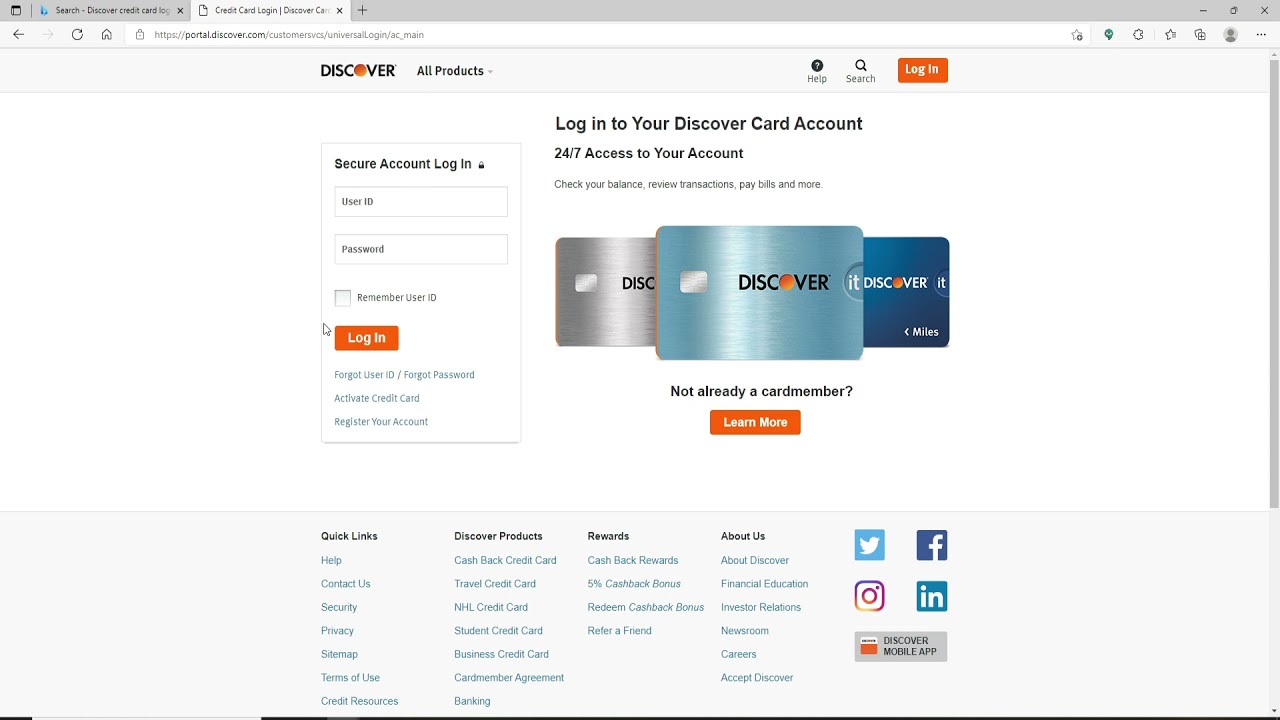
Start by making sure you are at discover.com and not some affiliate site or phishing mirror. Typo domains pop up constantly when you search for "Discover card login." Bookmark the real URL immediately after your first successful access. I keep discover.com in my bookmarks bar because I have seen colleagues accidentally land on lookalike sites that harvest credentials. It takes about four seconds to type the correct address once you have it memorized, but those four seconds save you from potentially handing your social security number to a bad actor. The login process itself is straightforward. Enter your username, which is your email address or phone number depending on how you set it up during registration. Then enter your password. After that, you will likely face a second verification step unless you are on a device Discover already recognizes. This is where most friction happens. If you are on a new computer or phone, expect to answer a security question or receive a code via text or email. The system sends codes within thirty seconds usually, but during high-traffic periods like payday weekends, delivery can stretch to two or three minutes. I learned the hard way that your security question answer needs to be something you will still remember in three years. I picked a random sentence that felt clever at the time and forgot it within months. Discover does not let you reset that particular question type quickly, so I spent an hour on chat support before I could get it changed. Now I use a consistent format for all my security answers: a specific book title, a random number between 100 and 999, and a day of the week. Nobody else would know it, and I would not forget it either.
What You Actually Find Inside
The dashboard shows your current balance, minimum payment due, payment due date, and available credit all on one screen. That is about four seconds of scanning if you know what you are looking for. Most people stare at the statement balance and miss the minimum payment, which creates unnecessary stress. Paying more than the minimum reduces interest charges significantly over time, but Discover will never tell you that on the homepage because they profit from carrying a balance. The payment section lets you transfer money from a linked bank account or pay by check mailing. Online transfers usually post within one business day, sometimes same day if you initiate before 8 PM ET on a weekday. Check payments take five to seven days depending on postal speed. I recommend setting up automatic payments for at least the minimum amount to avoid late fees, then manually topping up when you have extra cash. Late fees on Discover cards currently sit at around forty dollars, which disappears instantly from your wallet if you forget one payment cycle. Rewards tracking lives under the Cash Back tab. Discover categorizes your spending automatically, showing you bonus categories for each quarter. The rotating categories change every three months and require you to activate them monthly. I activated every single category for two years straight and earned maybe two hundred dollars extra annually. That is decent, but if you miss the activation window by even one week, you get zero bonus on those purchases until next month. Set a calendar reminder on the first of each quarter to activate your categories. It takes twenty seconds and prevents leaving money on the table.
Get the Full Details

Things That Break Without Warning
Password resets fail silently sometimes. You click the forgot password link, enter your username, and wait for an email that never arrives. This happens more often than Discover admits, usually when your email provider filters their messages as spam or when you registered with a secondary email address you no longer check regularly. I spent forty-five minutes trying to reset my password before I realized the confirmation went to my work inbox, not my home account. Keep your registration email address current, and check your spam folder before calling support. Two-factor authentication codes expire after five minutes. Some users click through three or four screens before entering the code, which triggers a timeout and forces a complete restart. The code refreshes automatically if you request a new one, but you lose any partial form entries. Fill out everything on the login page before waiting for the code, or keep your phone nearby and enter the code immediately upon receipt. This simple habit cuts my failed attempts from roughly one per week to one per month. Session timeouts occur after ten minutes of inactivity. If you are viewing a statement while half-watching television, the page will log you out without warning. You do not lose any data, but you must log in again. Some users interpret this as a security breach and panic. It is not. Discover implements this standard timeout to protect account access. Close other applications before pulling up your statement, or print the statement directly if you want a permanent record. Printing takes thirty seconds and eliminates the timeout problem entirely.
Common Mistakes That Cost Money
Missing the grace period is the biggest error I see. Discover offers twenty-one days interest-free on purchases if you pay your statement balance in full by the due date. Miss that window by one day, and interest accrues from the purchase date, not the statement date. That interest hits at your APR, which on most Discover cards sits between eighteen and twenty-five percent annually. On a five thousand dollar balance, a single missed payment can cost you anywhere from three hundred to four hundred dollars in interest over the following year. Set up autopay for the full statement balance, not just the minimum, to avoid this trap entirely. Using cash advance features on your Discover card is another costly mistake. Cash advances trigger immediate interest with no grace period. The transaction fee alone runs around five percent of the amount withdrawn, minimum five dollars. Combine those two costs and you are looking at paying roughly twenty-five percent upfront just to access your own credit line. I watched a friend withdraw two hundred dollars for an emergency and end up paying back over two hundred fifty within three months because the compounding interest never stopped. Avoid cash advances unless you have literally zero other options, and even then consider a personal loan from a credit union first. Ignoring your credit utilization ratio damages your score faster than most people realize. Discover reports your balance to the bureaus monthly, usually on your statement closing date. If you carry a high balance relative to your credit limit, that number appears on your report and drags your score down. The sweet spot sits below thirty percent, ideally below ten percent. Paying down balances before the statement closes, rather than waiting for the payment due date, keeps your reported utilization low. This tactic costs nothing and typically adds fifteen to thirty points to your FICO score within one reporting cycle.
When Support Actually Helps
Discover chat support connects within two to five minutes during business hours. Call centers are slower, sometimes thirty minutes on weekends. I prefer chat because I can paste screenshots and track the conversation simultaneously. However, chat agents have limited authority compared to phone representatives. If you need a fee waived or a rate adjusted, phone agents can sometimes do things chat cannot. Save important conversations in chat by taking screenshots or copying the transcript. Phone calls may not offer this option unless you request it explicitly. Security freezes work differently than you might expect. Discover allows you to freeze your account through the app or website, which blocks new transactions but does not erase your existing balance. This is useful if you misplace your card and cannot retrieve it immediately. The freeze lifts within seconds once you toggle it off. Some users confuse this with a credit freeze, which is a separate action through the bureaus. A credit freeze prevents new accounts entirely, while a Discover freeze only blocks activity on that specific card. Know which one you need before you act. Dispute resolution takes forty-five to ninety days for most claims. Discover provides provisional credits while they investigate, so you do not miss a payment during the process. However, if the investigation concludes against you, that provisional credit reverses and you owe the amount plus any interest that accrued. I disputed a fifty-dollar charge that turned out to be a legitimate subscription renewal. The provisional credit disappeared, the original charge reappeared, and I owed late fees because I had stopped paying my card thinking the dispute resolved everything. Read the dispute outcome email carefully before adjusting your payment behavior.

Tools That Make Managing Easier
The Discover mobile app mirrors most web functionality but adds quick actions like balance inquiries and payment initiation in under ten seconds. Push notifications for statement availability, payment confirmation, and suspicious activity arrive within minutes of generation. I receive three to five app notifications weekly, most of which are reminders I already know about. Disable nonessential alerts to reduce noise, keeping only payment due dates and low-balance warnings active. This trims my daily notification load from roughly four messages to two or three. Linking your Discover account to budgeting software like Mint or YNAB syncs automatically every few hours. Transaction data flows through, categorization happens automatically, and spending trends appear in charts without manual entry. This saves roughly two hours monthly if you previously tracked card spending by hand. Some users hesitate to connect financial accounts due to security concerns, but Discover uses the same Plaid encryption that powers most banking integrations. If you trust your bank to share data with third-party apps, Discover is equally safe. Credit score monitoring through Discover scores varies slightly from the FICO scores lenders use, but it tracks the same underlying factors. The score updates monthly and includes a breakdown of what is helping or hurting your number. I check mine quarterly rather than weekly because daily fluctuations rarely exceed five points. Large swings happen when you close accounts, apply for new credit, or carry high balances. Those are the moments worth watching closely, not every routine statement cycle.
What I Would Do Differently
I should have activated my rotating cash back categories on day one of each quarter instead of assuming they applied automatically. Three years of missed activations probably cost me around six hundred dollars in forgone rewards. Set a recurring calendar event for the first of January, April, July, and October to activate your categories. The process takes thirty seconds and compounds into meaningful savings over time. I also neglected to call about my interest rate twice during periods where I maintained perfect payment history. Discover occasionally offers rate reductions to loyal customers who ask. One colleague lowered her APR from twenty-one percent to sixteen percent after a polite chat with retention. That five percent difference saved her roughly two hundred fifty dollars annually on her average balance. The call lasts ten minutes. Nothing costs you anything to try. Finally, I wish I had printed my annual fee statement earlier in my relationship with Discover. The card charges no annual fee, which makes it genuinely competitive among cash back cards. But discovering that fact requires reading the terms carefully during sign-up. New cardholders often assume fees exist because most premium cards carry them. Verify your fee structure before assuming the worst. A free card that you manage responsibly beats a rewarded card whose perks vanish behind hidden charges.
The login process at discover.com works smoothly once you understand where it stumbles. Most problems trace back to forgotten passwords, missed two-factor timing, or inactive sessions rather than systemic failures. Treat your account access like any other routine financial task: prepare before you need it, verify credentials in advance, and keep your contact information current. Discover rewards consistent account management with competitive cash back rates and straightforward tools, provided you navigate the minor friction points without panic. The platform does not reward exploration or spontaneous logins. It rewards the user who knows the layout, anticipates the timeouts, and maintains their information across quarters. That is the pattern that keeps your account open, your balance low, and your rewards accruing month after month.