Getting a QR PH Code in GCash Is Trivial. Managing It Isn't.
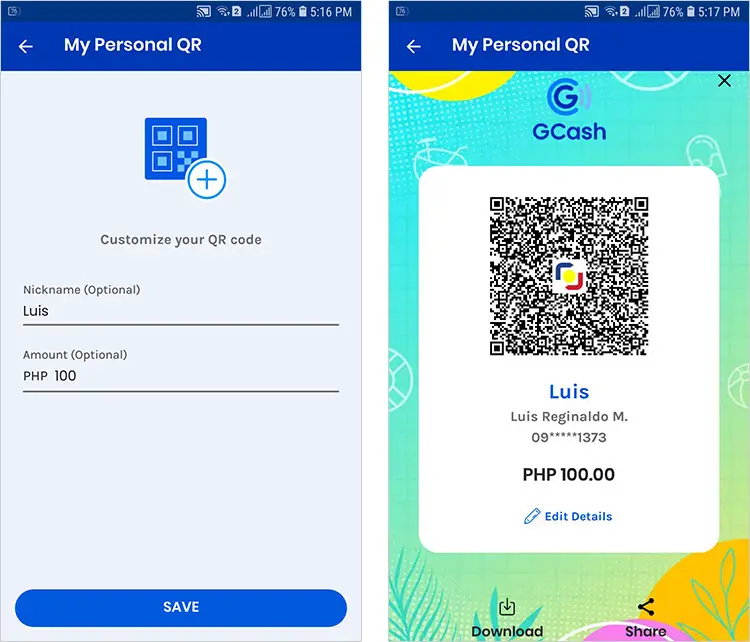
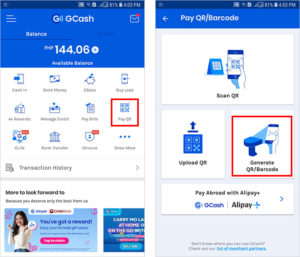
I have been running a small electronics repair stall for about four years now, and I stopped using a physical cash box somewhere in 2023. Not because I love technology, but because the line for paying with cash was slower than the line for paying with GCash. The QR PH system changed that. It is the national QR standard in the Philippines, and when you pair it with GCash, you get a payment system that works across dozens of banking apps and e-wallets, not just GCash. That interoperability is the whole point. The mechanism itself is simple enough that I will get to the steps first. You open the GCash app, go to the Pay menu, and select the QR Code section. There you can generate either a static code for your business or a dynamic code for a specific transaction. The static code is what you display on a table or counter. The dynamic code has a preset amount and expires quickly, which is useful for in-person exchanges where the customer scans after you type in the price. Most small merchants use the static code, but the dynamic option exists for people who need to lock in an amount before the customer scans.
Unlock Your Cash Flow With Gcash Qr Ph Codes Easy Steps To Create
Here is exactly how you set it up. First, download the GCash app from the Play Store or App Store and complete the full registration process. This means providing your mobile number, verifying via OTP, and completing KYC by uploading a valid ID. A fully verified account is required to access the business QR features. Once that is done, launch the app and tap Pay. On the next screen, look for the QR Code icon and select Create or Generate QR Code. Choose Static if you want a permanent code to display, or Dynamic if you need a one-time code with a specific amount. Fill in the business name and any other required details, then confirm. GCash will generate the QR code, and you can save it to your gallery or share it directly. That is it. The actual generation takes about 90 seconds if your account is already verified. What most people miss is the distinction between a regular GCash payment QR and a proper QR PH code. A standard GCash payment request code only works when both parties use GCash. A QR PH code works because it follows the ISO/IEC 18004 standard and carries metadata that tells any compliant app what to do. This means a customer using BDO, UnionBank, Mayapay, or any other QR PH-enabled wallet can scan your code and pay you. It matters more than you would think in a country where not everyone uses the same e-wallet. The real value comes in the settlement side. When someone scans your QR PH code, the money does not appear in your GCash balance instantly if you are routing through a bank partner. With GCash directly, it is usually immediate, but when you have linked a bank account or chosen a specific payout schedule, there can be a 1 to 2 business day delay. I learned this the hard way during a slow quarter. I had set up my QR code through a promotional campaign that defaulted my settlements to a weekly payout cycle tied to a partner bank. I thought my daily revenue was stuck somewhere. It was not stuck. It was just being batched every Friday. Switching to immediate settlement cleared that up, but it took me three days of calling support to figure out where the money went.
There are edge cases that the app does not warn you about. For instance, if your business QR code is associated with a merchant account that has reached its transaction limit, customers will still be able to scan the code, but the payment will fail on their end with a generic error message. This is frustrating for both sides. I had a customer pay me 3,000 pesos in a single day across multiple transactions, and the next day all scans failed silently. The fix was to update my account tier through the GCash app under Profile and Verification. Moving from a basic account to a fully verified business account raised the daily transaction cap significantly. Do this before you start accepting payments at scale. Another detail nobody mentions is that QR PH codes can be customized visually, but customization has limits. You can add your business logo and change colors, but if you compress the design too much or add too much visual clutter around the code itself, the scanning rate drops noticeably. I spent two hours designing a fancy QR sticker for my shop window with thick borders and a large logo in the center. Customers could not scan it from more than half a meter away. I switched to a clean, high-contrast version with minimal decoration and the scan success rate went from maybe 60 percent to nearly 100 percent. Print it large, keep it simple, and place it at eye level on a flat surface. The downsides are real and worth stating plainly. QR PH depends entirely on the customer having an active e-wallet or banking app with sufficient balance. Cash transactions still work for people who do not use digital payments, and you should not stop accepting cash just because QR codes exist. There is also a fee structure to consider. GCash charges a merchant transaction fee, typically around 1 to 2 percent depending on your account tier and whether you are processing through a direct integration or the standard QR PH gateway. For a small stall making 50,000 pesos a month, that is a few hundred pesos in fees. Manageable, but not free. If you are moving larger volumes, the fees add up, and you might want to look into a dedicated merchant gateway like Xendit or PayMongo, which offer lower rates and better reporting tools.
Get the Full Details
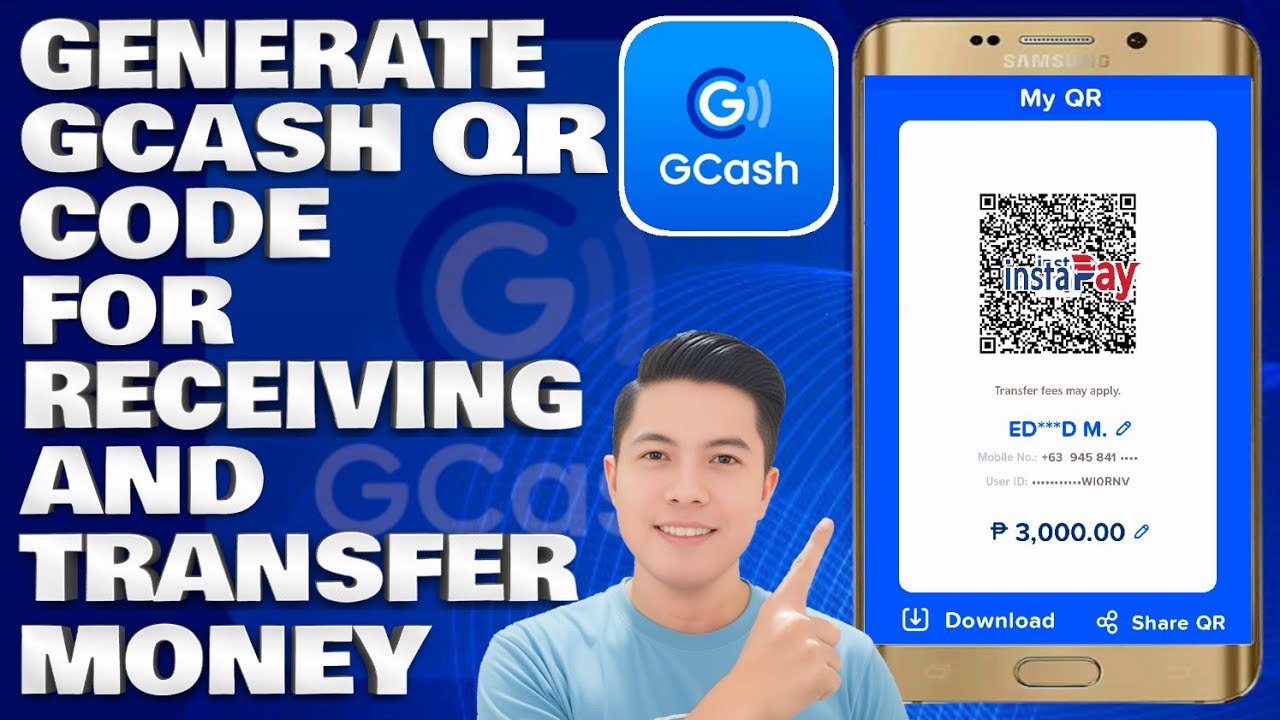
Security is another concern that gets glossed over. A static QR code is permanent, which means anyone who photographs it can potentially reuse it if you are not monitoring your transactions. I recommend enabling transaction notifications in the GCash app and checking your statement at least once a day. Set up a password for every withdrawal or transfer, and do not share your MPIN with anyone. There are documented cases of scammers replacing a legitimate QR code with their own sticker printed on top of the original. It happens more often than you would expect in crowded markets and food stalls. Patrol your code at least twice a day. If you want to move beyond a simple static code, GCash also offers a business dashboard where you can view sales analytics, export transaction reports, and manage multiple QR codes for different locations or staff members. This requires signing up for GCash for Business, which involves additional documentation like a Mayor's Permit or DTI registration depending on your business structure. The onboarding takes longer, maybe a week or two, but the control you get is substantial. You can track which QR code generated each sale, monitor peak hours, and reconcile your daily income against your bank deposits without guessing. The system works well when you understand its boundaries. It is fast for small to medium transactions, it is widely compatible, and it reduces the hassle of carrying change. It is not a miracle for high-volume commerce, and it will not help you if your target market primarily pays in cash. But for most small businesses in the Philippines, generating a QR PH code through GCash is the single most effective step you can take toward modernizing your payment collection. Start with the basic static code, verify your account fully, monitor your transactions daily, and upgrade to the business tools when your volume justifies it.