Inventory Financing Basics
Inventory financing is a type of asset-based lending where your stock becomes collateral for a loan or line of credit. You get cash against the value of goods sitting in your warehouse, and you repay it as those goods sell. That is the simple version. The practical version involves a lot more nuance, and most businesses that try it without understanding the mechanics end up paying way more than they need to or triggering covenant breaches they did not see coming. The two main structures you will run into are floorplan financing and inventory-backed lines of credit. Floorplan financing is used heavily by auto dealers, retailers, and distributors who receive goods in regular cycles and need to pay suppliers before their customers pay them. An inventory-backed line of credit works more like a revolving credit facility where the borrowing base fluctuates as your inventory levels change.
Unlock Your Business Potential With Inventory Financing What It Is How It Works
Here is how the process actually works in practice. You apply, the lender sends out an appraiser or auditor to physically inspect your inventory, and they assign a advance rate. For general merchandise, you might see 50 to 75 percent of the cost value. For specialized equipment or seasonal goods, that number drops significantly because the liquidation risk is higher. The lender then sets up a control system. This usually means either you sign over control of the inventory through a field exam arrangement where the lender monitors stock levels, or you move to a warehouse arrangement where the lender's agent holds the goods and releases them as you make payments. I dealt with a manufacturing client a few years back who had about $800,000 in raw materials and work-in-progress that sat unused while they struggled to get a line of credit approved. The lender initially valued their WIP at 30 cents on the dollar, which was nowhere near enough. What they did not understand was that their finished goods were moving fast, and their raw materials were specifically graded and traceable. I had them restructure the application to emphasize the finished goods side of the balance sheet and provide supplier contracts showing consistent procurement pricing. The lender came back with a 65 percent advance rate on finished goods and 45 percent on raw materials, which was a completely different conversation. The key was making sure the lender understood the liquidation path for each category. One thing people get wrong about inventory financing is assuming the advance rate is fixed. It is not. The borrowing base certificate you submit monthly can change the actual amount available to you. If your inventory dips below a certain threshold, the lender can reduce your line. If you overstate inventory on that certificate, which happens more often than you would think, you are looking at covenant violations and potential acceleration clauses.
The cost side is where most businesses get surprised. Inventory financing is not cheap. You are typically looking at a base rate tied to the prime rate or SOFR plus a markup of 2 to 4 percentage points, depending on your industry and the quality of your inventory. On top of that, there are arrangement fees, ongoing monitoring fees for field exams, and appraisal costs that can run from two to five thousand dollars per inspection cycle. Some lenders also charge draw fees on each advance you take out, usually around 0.25 to 0.50 percent. A $500,000 line can easily cost you $30,000 to $50,000 annually in total carrying costs if you are using a significant portion of it. Another counter-intuitive point is that having excess inventory does not always help you. Lenders discount slow-moving stock heavily. If you have a product that has been sitting for more than 90 days, the advance rate on that category can drop to 20 or 30 percent, or the lender may refuse to count it toward your borrowing base altogether. This is why inventory turnover matters more to lenders than total inventory value. Fast-moving goods at lower margins often qualify for better terms than slow-moving goods with higher margins because the lender can actually recover their money if things go south. There are scenarios where inventory financing is the wrong tool. If your inventory is highly customized or has no secondary market, traditional inventory-backed lending will not work well. In those cases, you are better off looking at purchase order financing or factoring your receivables instead. I saw a custom furniture maker try to use inventory financing for bespoke pieces that were already paid for by customers. The lender refused to count any of it because there was no clear liquidation path, and the whole process wasted three weeks and several thousand dollars in appraisal fees before we pivoted to a simple invoice factoring setup that fit their business model.
Get the Full Details
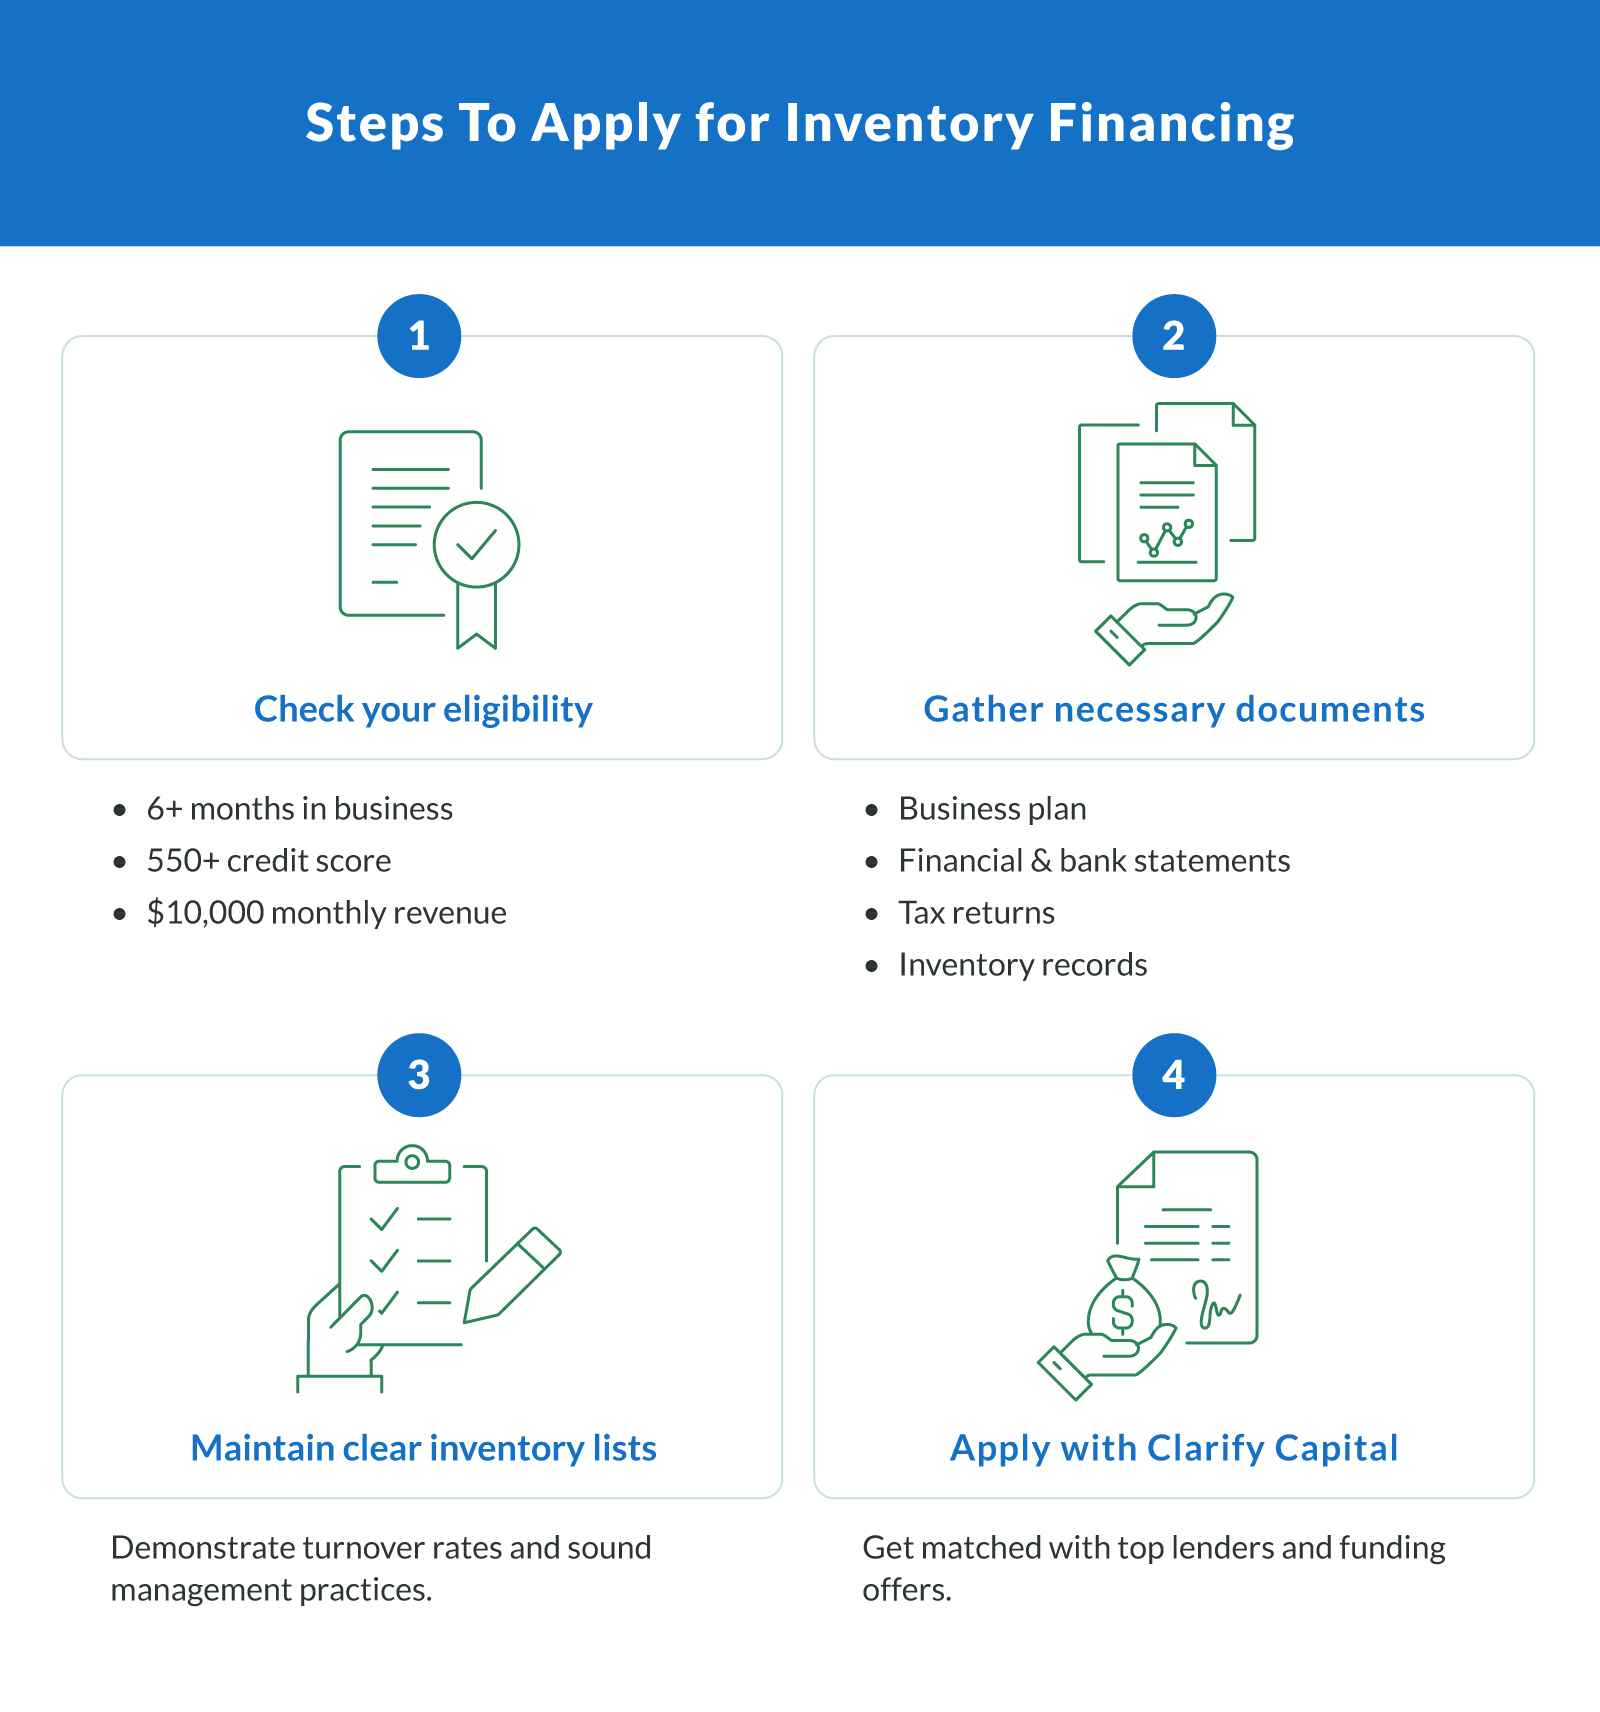
The application process itself varies by lender but generally requires financial statements, inventory aging reports, supplier relationships documentation, and sometimes customer concentration data. Larger lenders will want to see two years of audited or reviewed financials. Smaller community banks and specialized inventory lenders may work with tax returns and internal reports, but the advance rates will reflect that higher perceived risk. Turnaround time ranges from two weeks for straightforward cases to six to eight weeks if your inventory is complex or your financials need significant cleanup. If you are considering this route, start by mapping out your inventory categories and understanding how different lenders would value each one. Know your turnover rates before you walk into a meeting. Prepare an inventory aging schedule and be ready to explain any items over 60 days old. The lenders who give you the best terms are the ones who come in with their own numbers already researched, not the ones who need to be convinced their collateral is real.