The Practical Side of Getting a Walmart Business Card
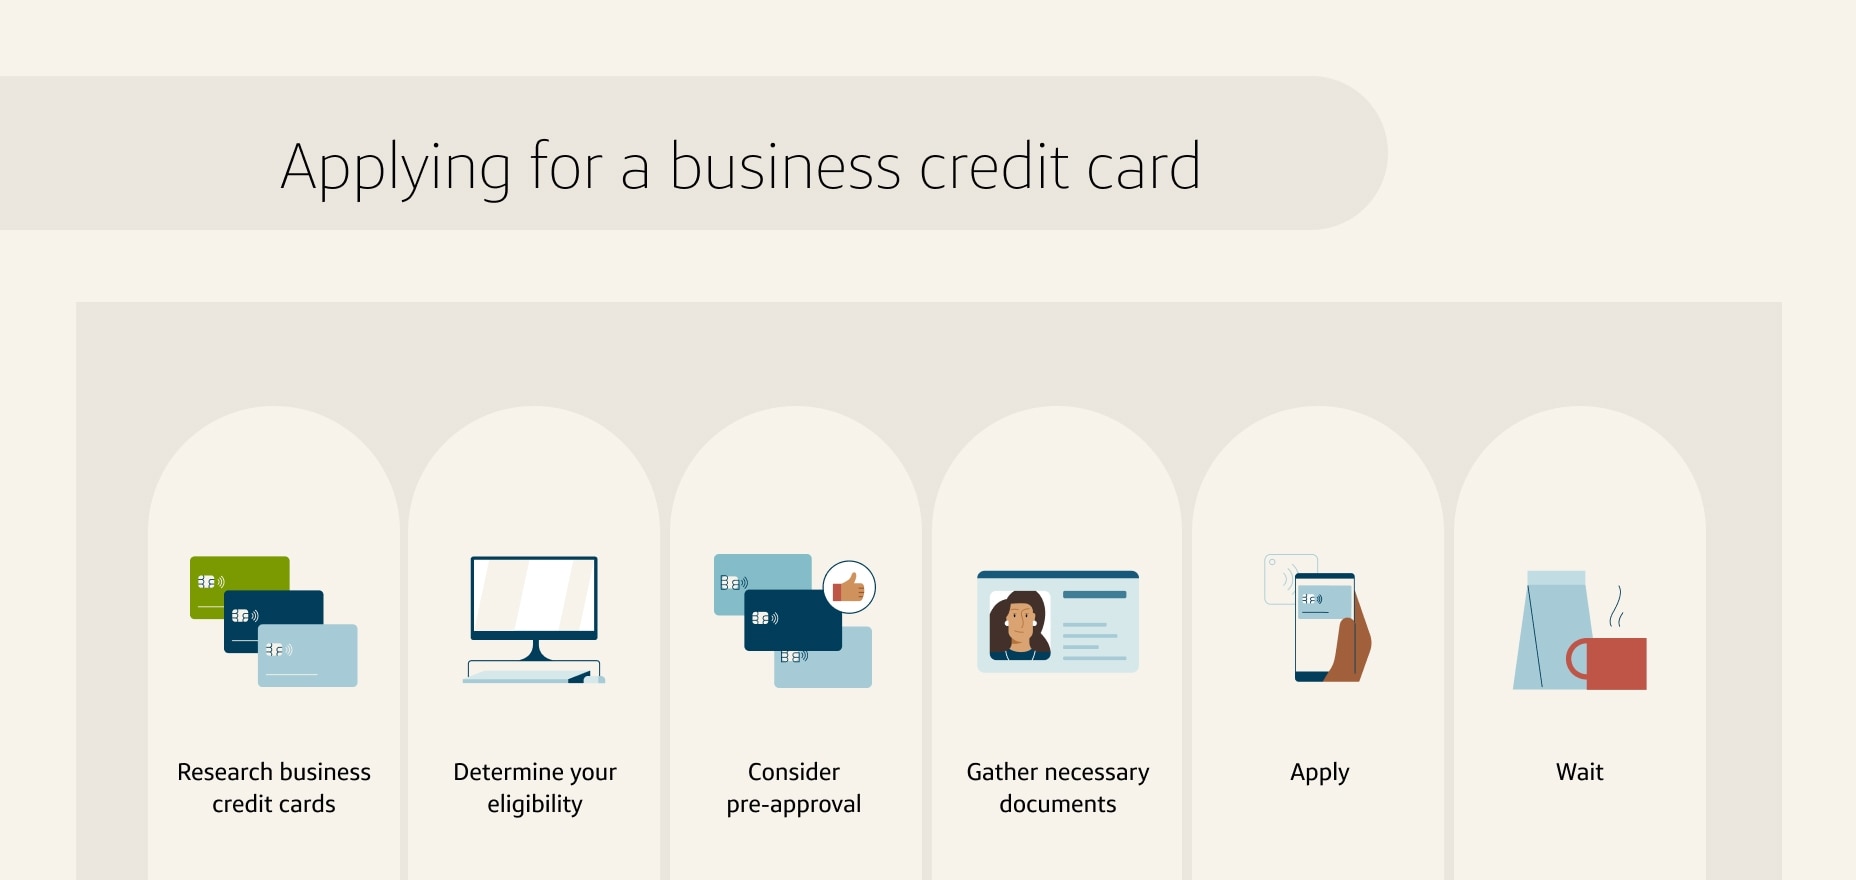
Most small business owners I know who apply for a Walmart Business Credit Card do it because they spend a lot on office supplies, packaging materials, and general merchandise. The card itself is straightforward. It offers a 10% discount on eligible Walmart.com purchases and up to 5% at Walmart stores for employees with approved accounts. The approval process happens online, but the data you need to gather beforehand usually takes people by surprise.Here is what actually happens when you go through the application, based on experience running a small e-commerce operation that relied heavily on this card for about three years. You start at walmart.com/business. The application asks for your legal business name, EIN or SSN, business address, and annual revenue. That last field is where people hesitate. You do not need to provide audited financials or tax returns at the time of application. A rough estimate is fine, but keep it honest. The review happens instantly in most cases, though some applications get routed to manual underwriting, which can take five to ten business days. I learned this the hard way on my second application attempt. My first try got declined without explanation. The second time, I adjusted my revenue figure from $85,000 to the correct $112,000 and included a slightly different business classification code. It went through on the first pass. The difference was almost certainly the revenue mismatch, not the industry category. Once approved, you get an account number within minutes. The physical card arrives in about seven to ten business days. There is no annual fee. Rewards are not points based. The main benefit is the discount structure on Walmart purchases and the ability to track business spending in a dedicated portal.
What Most People Miss About This Card
The discount percentage is not uniform across all categories. Electronics and grocery items often fall outside the eligible range. The 10% online discount applies mainly to hardlines, home goods, and general merchandise. If you are buying inventory to resell, check the specific product category before assuming the discount applies. I once ordered $2,400 worth of products expecting the full 10% off. About forty percent of the order was excluded from the discount, which cost me roughly $80 I had not budgeted for. Another thing that catches people off guard is the credit limit. Starting limits tend to be conservative, usually between $1,000 and $5,000 for new accounts. The system reviews usage after about six months and may increase the limit automatically. Regular use with on-time payments is the only way to push that higher. There is no appeal process for a low initial limit.
Alternatives Worth Considering
If your business primarily buys from Amazon, the Amazon Business Prime card from Capital One might serve you better. The rewards structure is more flexible and the acceptance rate is broader. Walmart Business Credit works best if your supply chain already runs through Walmart. It is not a universal business card. Trying to force it into a procurement strategy where Walmart is not a primary vendor will likely leave money on the table compared to other options. The most frequent reason applications get delayed or rejected is a mismatch between the business name on your EIN paperwork and the name you enter on the application. Even a minor variation like "Smith Consulting LLC" versus "Smith Consulting, LLC" can trigger a manual review. Make sure the name matches exactly what the IRS has on file. Another issue is using a personal address when the business operates from a commercial location. The system flags this sometimes. Use the actual business address and a business phone number if possible. It speeds things up significantly. The application does not check your personal credit score heavily, but it does pull a soft inquiry. A hard pull only happens if you proceed past the initial screen. You can see your likely terms before committing, which is useful for gauging approval odds without affecting your credit report.
Get the Full Details

Managing the Account After Approval
The online portal lets you add employee cards with custom spending limits. This is useful if you have staff who handle purchasing. Each employee gets their own card tied to the main account, and the owner sees all transactions in one place. Payment is due in full each month. There is no revolving balance option and no grace period for purchases. You cannot carry debt on this card. That is not a bug, it is a feature if you want to avoid interest charges, but it means you need to be disciplined about paying the statement balance by the due date. Cash back or rewards do not compound. The discount applies at point of sale. There is no sign-up bonus, no category multipliers, and no transferable points. If you are looking for a rewards card that builds value over time through redemption flexibility, this is not it. The value is purely in the discount on eligible purchases.
When It Makes Sense and When It Does Not
The card makes sense if you regularly purchase from Walmart or Walmart.com and want a straightforward discount on everyday business supplies. It does not make sense if you are trying to build a rewards portfolio, need a sign-up bonus, or do most of your purchasing elsewhere. The discount is real but narrow in scope. For a small business spending $3,000 a month at Walmart on eligible items, you are looking at roughly $300 in annual savings. That is not trivial, but it is also not transformative. Treat it as a supplementary tool, not a primary financial strategy.