Paying for your beauty hauls without bleeding out at checkout
You pick up a bunch of fenty, a couple of drugstore hair treatments you actually need, and some overpriced moisturizer you saw on TikTok, and then you remember you're at Ulta. The checkout line is long, the clerk is asking if you want to open an account, and suddenly you're trying to figure out whether the Comenity card is worth the paperwork. I've been through this exact scene probably four times in three years. Here's what actually happens when you go through with it. The Ulta Credit Card is issued by Comenity Capital Bank. It sits in a slightly weird middle ground between a standard store credit card and a premium rewards card. You're not going to get unlimited free flights or hotel upgrades, but you will get decent returns on things you were already buying. That distinction matters more than most guides admit. When I first applied, I expected the approval process to be instant. It is not. Comenity uses a soft pull for the prequalification check, which shows your estimated card options without denting your credit score. The real application triggers a hard inquiry. I got declined on my first try because my credit utilization on existing cards was sitting at 78 percent. I paid down two cards, dropped my utilization below 30 percent, and applied again three weeks later. Approved on the second attempt with a 680 FICO score. The timing of when you apply matters more than the card itself.
What the card actually gives you
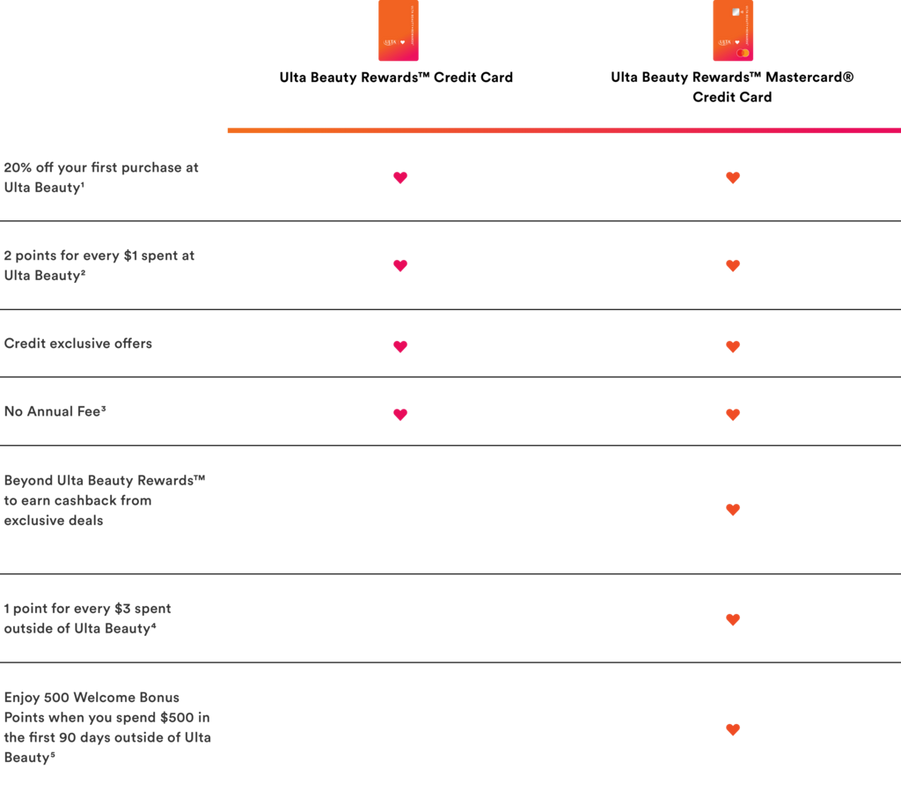
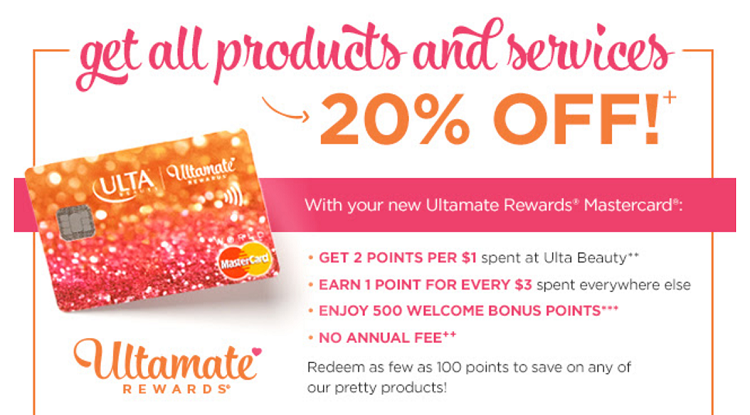
There are two versions of the Ulta card now, and mixing them up is the most common mistake people make. The store card only works at Ulta. The Mastercard version works everywhere. Both earn points, but the earning rates and redemption options differ in ways that matter if you shop frequently. Store Card: Earns 2 points per dollar on Ulta purchases, 1 point on everything else. Points are worth 1 cent each when redeemed toward future purchases. That means a $50 makeup order nets you roughly $1 back in rewards. Not exciting, but it compounds if you shop the biannual 21-day sale events where you can stack extra promotions. Ulta Mastercard: Earns 2 points per dollar at Ulta, 1 point elsewhere. The key difference is you can redeem points for merchandise rewards certificates, not just statement credits. These certificates come in increments and sometimes include bonus value events.
The real benefit isn't the raw point value. It's the access to Ulta's birthday gift, exclusive member-only sales, and the occasional promo where you earn 10 points per dollar for a limited window. I caught one of those promos last fall and earned back about $18 in rewards from a single $55 purchase. The card pays for itself if you're already a regular shopper and you use it strategically during bonus periods.
Get the Full Details
Applying: what to expect and how to avoid a miss
Go to ulta.com/credit or tap the credit card banner on the mobile app. You'll fill out a standard application with your SSN, income, and housing information. You can prequalify first using the soft pull tool, which takes about 90 seconds and doesn't affect your credit. I always prequalify before applying. It saves the hard inquiry if you're likely to be declined. If you apply and get approved, you can choose to activate immediately and start using it. Or you can wait. There's no penalty for waiting. I recommend waiting until you have a planned purchase rather than activating on impulse. The card has an annual fee of zero dollars, which is why people fall into spending they wouldn't otherwise do just to use it. For new accountholders, the sign-up bonus changes frequently. Last quarter it was 20,000 points after spending $100 within 90 days. That translates to roughly $20 back, which covers a decent foundation or a set of skincare products. Check the current offer on the application page before you commit. Older guides online cite expired bonuses that no longer exist.
What nobody tells you about the fine print
The stated APR is shockingly high. I'm talking 29.99 percent variable. If you carry a balance past the billing cycle, you will feel it. One $200 purchase that you don't pay off in full will cost you roughly $5 in interest before the next statement arrives. This card is not designed for people who carry balances. It's designed for people who pay it off every month and collect rewards on purchases they were making anyway. There's no grace period mentioned prominently on the application page. By law, if you carried a balance from the previous statement, your new purchases may not earn a grace period until you've paid the balance in full for two consecutive billing cycles. I learned this the hard way after carrying a $43 balance for three months and being surprised that my new purchases were accruing interest immediately. Pay the statement balance in full, every time, or the rewards don't come close to offsetting the interest charges. Another thing that trips people up: points expire. They don't expire at some arbitrary date, but they do expire if your account goes inactive for 24 months. Opening the card and never using it, then wondering why your points vanished, happens more often than you'd think. Set a calendar reminder to make at least one small purchase every year if you're not a regular Ulta shopper.
The workaround I use for maximum value
I track the Ulta calendar. The 21-day sale happens twice a year, usually in late winter and mid-fall. During those windows, cardholders earn double points on top of the sale pricing, and you can stack manufacturer coupons. I time my bigger purchases around these events. It turns a normal shopping trip into something closer to a 30 percent return instead of the baseline 2 percent. I also use the card for the Ulta Rewards program layering. Every dollar spent earns the standard 1 point per dollar toward your VIP status, plus the credit card points on top. If you're already a U Altruist member, combining both programs means you hit status faster and rack up rewards simultaneously. I reached U Altruist status in about eight months of regular monthly purchases, which would have taken roughly a year without the card. One practical trick that isn't obvious: the birthday gift. If your card is open before your birthday month, you typically get a free gift. It's not guaranteed, and it varies by year, but it usually includes a decent-sized sample or a travel-size product you'd otherwise pay $12 to $15 for. Worth noting the month you apply relative to your birthday if you're on the fence.

When to skip it entirely
If you shop at Ulta maybe twice a year and spend under $100 per visit, the card isn't worth the hard inquiry. The rewards accumulation is too slow to justify the credit check. Same if you already have a cash-back card that gives you 2 percent at retail stores. A Chase Freedom or Citi Double Cash card will outperform the Ulta card for a casual shopper. If you've ever carried a balance on a high-APR card, do not open this one. The 29.99 percent rate will punish you harder than any rewards program can compensate. I've seen people earn $30 in Ulta rewards and lose $60 in interest because they missed a payment. It's a math problem, not a loyalty problem. Also, if you're actively trying to build or repair credit, this card can work, but it's not the best tool. Comenity reports to all three bureaus, which is good, but the high APR and narrow reward structure make it a less efficient credit builder than a secured card from a issuer like Discover or Capital One. Use the secured card for six months, see your score move, then consider the Ulta card if you're a regular shopper.
Bottom line
The Ulta Credit Card from Comenity is a reasonable rewards card for people who already shop at Ulta regularly and pay their balances in full. It's not a great financial product for everyone, and it's actively harmful if you carry debt. Check the current sign-up offer, review your credit utilization before applying, and time your activations around the biannual sales. Otherwise, you're just another person opening a card you didn't need and wondering why your points aren't adding up to much.