Western Union Doesn't Have To Be A Pain
Most people treat Western Union like a last resort. They walk into a grocery store with a $200 transfer, pay a flat fee that feels arbitrary, and then wait while the clerk searches for a form that shouldn't exist in 2024. It doesn't have to be that way. Doing it from your phone is faster and cheaper, but there are a few things they won't tell you about the process unless you've actually done it enough times to learn by mistake. I learned the hard way about the agent location markup. Back in 2019 I sent money through a Walmart in my town because the timing worked. The app had shown me one fee. The counter person applied a completely different rate structure and I paid nearly double. Since then I've stuck to direct app transfers almost exclusively and avoided walk-in agents whenever possible.
Unlock The Speed And Convenience Of Western Union Transfers A Quick Guide
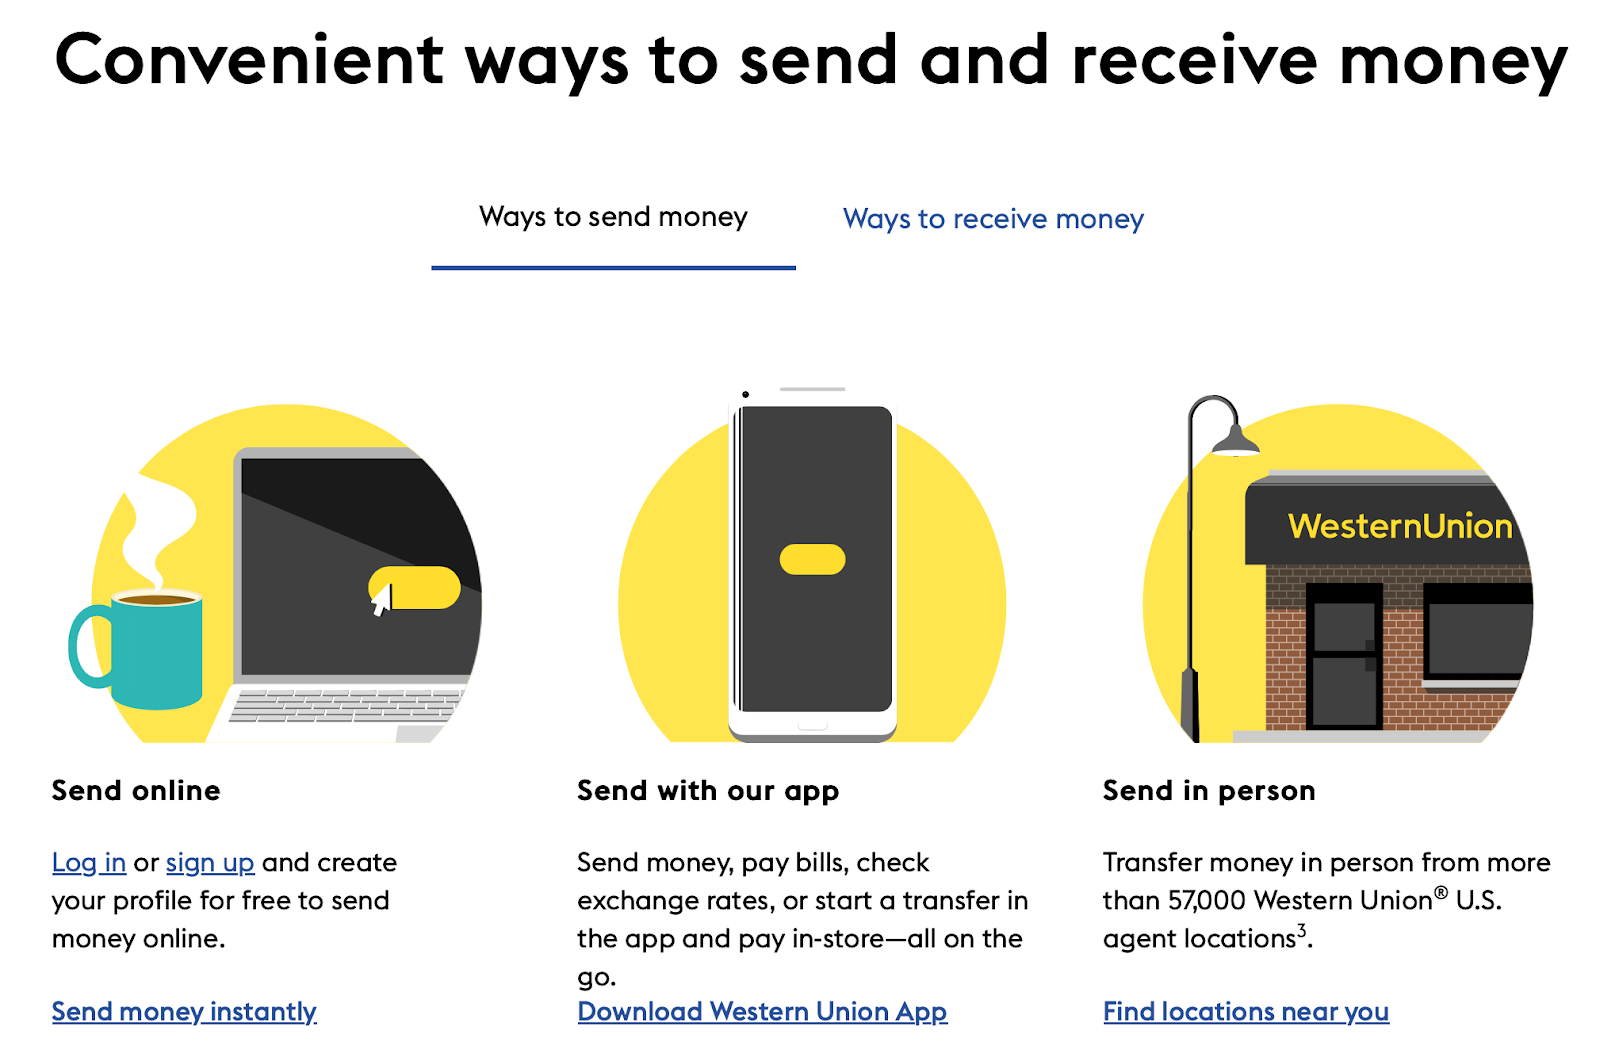
Start with the mobile app rather than the website. The app interface is less cluttered and pushes you toward the faster flow. Open it, tap "Send Money," and enter the recipient's full legal name exactly as it appears on their government ID. Even one misspelled character can delay payout by two to four business days while customer service traces the mismatch. I once wasted an afternoon on this with a recipient named "Mohammed" getting flagged as "Muhammed" — small differences matter more than you'd expect. Choose your delivery method before you enter the amount. Bank deposit is usually the cheapest option if the recipient has an active account, taking anywhere from a few minutes to two hours depending on the country. Cash pickup at an agent location is faster but slightly more expensive. Mobile wallet delivery exists in certain countries and can hit the recipient's account in under ten minutes. Avoid the "check by mail" option unless you genuinely need physical documentation — it takes five to ten business days and introduces a whole different layer of risk. The fee structure is where people get tripped up. Western Union uses a variable pricing model that changes based on three things: the amount you're sending, the destination country, and the payment method you use to fund the transfer. Paying with a debit card costs more than paying with your existing Western Union balance or a bank debit pull. I learned this when I switched to funding transfers directly from my linked checking account and watched my average fee drop from about $8 to $3.50 on a typical $200 send.
Exchange rate is the hidden cost. Western Union adds a margin to the mid-market rate, typically between 2 and 5 percent depending on the currency pair. For large transfers this margin dwarfs the upfront fee. If you're moving more than $500, it's worth comparing the total cost including the rate against alternatives like Wise or Remitly. Western Union is competitive for small, urgent transfers under $200 but becomes expensive quickly as the amount grows. Here's something most guides don't mention: the tracking number you get after sending isn't just for your peace of mind. If the recipient reports a problem, that MTCN — Money Transfer Control Number — is the single most useful piece of information you can give customer support. Write it down. Save a screenshot. Store it in a password manager. Without it, resolving issues becomes a much slower conversation where you're trying to reconstruct a transaction that happened days ago. Receipts matter too. The digital receipt contains the exact exchange rate applied, the total amount the recipient will receive, and the fee breakdown. Screenshot it immediately after confirmation. I once had a recipient claim they never received the full amount, and that receipt proved the discrepancy was on their end, not Western Union's. It saved a two-week dispute process down to a ten-minute resolution.
Get the Full Details

Processing times vary wildly by region. US to Canada bank deposits often land within 30 minutes. US to Nigeria cash pickup can be immediate but bank deposits might take three business days. US to Philippines mobile wallet transfers are frequently under 15 minutes. Check the estimated delivery time shown in the app before you confirm — it's usually accurate, but it's also the most ignored field in the entire flow. There are limits you should know about. New accounts typically start with lower send limits, sometimes as low as $500 per transaction. Verified accounts with completed identity checks can push much higher, but the exact thresholds depend on your country and the payment method used. If you're planning regular transfers, go through the verification process early rather than hitting a wall halfway through your first big send. Customer service is not great. Call wait times during peak hours can exceed forty-five minutes. The chat bot is marginally better but will loop you in circles on anything that requires actual judgment. My workaround is to use chat first for simple issues, then escalate to a callback request if the bot can't resolve it. The callback system is surprisingly reliable — they usually call back within an hour during business hours, and the agent has more authority than the chat staff.
Don't send from an IP address in a different country than your verified identity. Western Union's fraud systems flag cross-border logins aggressively. I once tried to send money while traveling and got my account temporarily restricted because my phone's GPS showed a different country than my registered address. It took three business days and a photo of my passport to lift. Travel with your verification documents handy if you plan to send while away from home. Recipient validation is worth doing on the first transfer to any new person. Enter their details and go through the confirmation screen without actually submitting. This checks that the name, country, and payout method all align before you commit real money. I've seen people lose hours because they assumed a recipient had a bank account when they only had a cash pickup location, or vice versa. Western Union is fast for what it is, but it's not the cheapest option for routine transfers. If speed is the only priority and the amount is under $300, it works well. If you're sending larger sums regularly or care about minimizing total cost, compare it against alternatives before committing. The convenience is real, but so is the markup.