What Gross Margin Actually Tells You
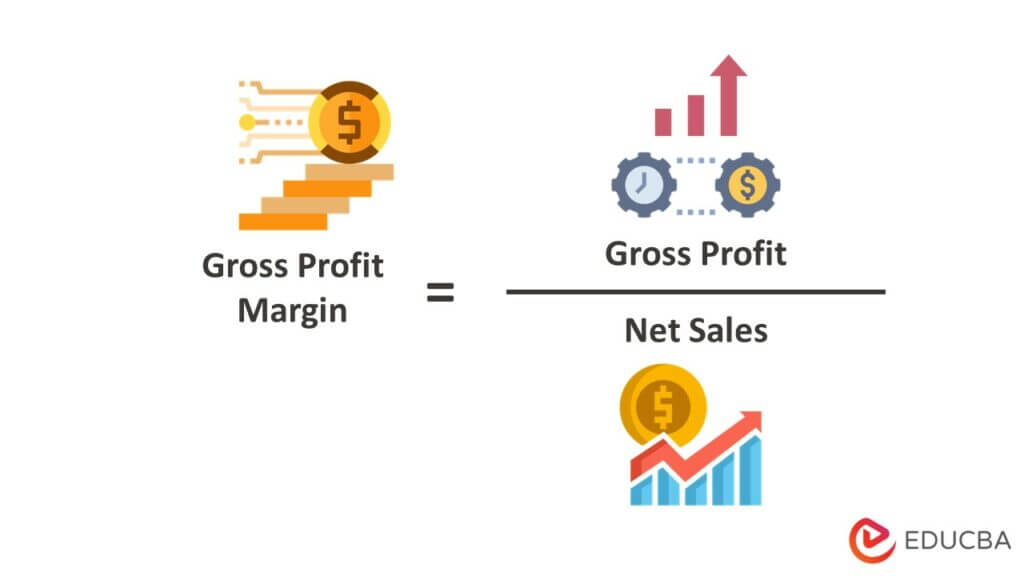
Gross margin is the percentage of revenue that remains after you subtract the cost of goods sold. It's one of those numbers that looks straightforward on paper but tells you everything you need to know about whether your pricing strategy is working or quietly bleeding money. Here's how you calculate it without overcomplicating things. Revenue minus COGS, divided by revenue, times 100. If you sold $500,000 worth of product and it cost you $300,000 to produce or acquire those goods, your gross margin is 40%. That's it. Simple arithmetic that most business owners skip because they're too busy looking at net profit.
Unlock The Secrets Of Your Businesss Financial Health The Power Of Gross Margin
The problem is that most people treat gross margin as a static metric. It's not. It shifts with supplier costs, pricing changes, product mix, and seasonality. I learned this the hard way running a small e-commerce operation back in 2019. We had a 52% gross margin on paper, which sounded healthy. Then our primary supplier in Vietnam raised prices by 18% overnight due to raw material shortages. Overnight, our margin dropped to 37%. We didn't notice for three months because we were focused on top-line revenue growth, which had actually increased. By the time we caught it, we'd already committed to a batch order that would have been unprofitable at the new cost structure. The workaround was brutal but effective. I rebuilt our pricing model around gross margin thresholds instead of competitive pricing. Every product had a minimum margin floor. If a supplier quote came in below that floor, we either renegotiated, found an alternative supplier, or dropped the product entirely. It cut our SKUs by about 30%, but our weighted average gross margin went from 37% back up to 49% within two quarters. Here's something most guides won't tell you: gross margin can be manipulated through inventory accounting methods. If you're using FIFO versus LIFO during inflationary periods, your COGS changes significantly even though nothing about your actual operations has shifted. During a period of rising input costs, LIFO will show higher COGS and lower gross margin compared to FIFO. This isn't fraud, but it absolutely affects how you interpret your numbers month to month. Stick to one method consistently and document why you chose it.
Another counter-intuitive thing I've seen repeatedly: high gross margin doesn't mean a product is profitable. I worked with a client whose flagship product had a 68% gross margin. Impressive on the surface. But that product required extensive customization, lengthy fulfillment times, and disproportionately high return rates. When we allocated fulfillment and return costs into a contribution margin analysis, the real picture was closer to 22%. Meanwhile, their second-tier product with a 38% gross margin was generating three times the net contribution because it was simple to fulfill and rarely returned. So how do you use gross margin practically? Start by tracking it per product line or per SKU, not just at the aggregate level. Aggregate gross margin hides problems. Break it down quarterly. Compare it against your weighted average across all products. Any product dragging the average below industry norms deserves investigation. Industry benchmarks vary, but generally speaking, software businesses run 70-80% gross margin because marginal cost of delivery is near zero. SaaS specifically can push even higher. Physical retail typically sits between 25-50%. Manufacturing and wholesale tend to be 20-40%. If your numbers are outside these ranges, that's not necessarily wrong, but it probably warrants explanation. Low margin with high volume can work. Low margin with low volume won't.
Get the Full Details
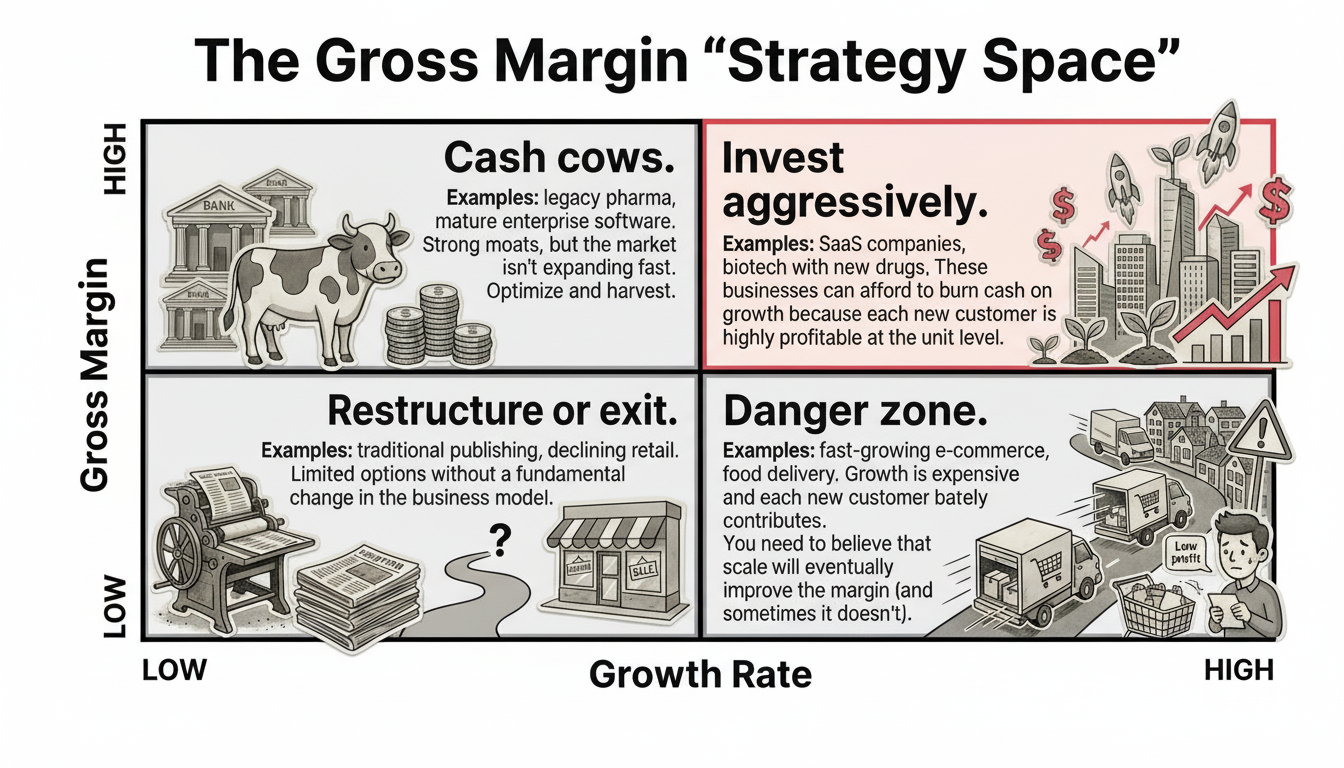
One more thing that matters: gross margin before vs. after discounts and returns. If you're calculating based on list price, your number is fictional. Calculate based on actual realized revenue after returns, chargebacks, and promotional discounts. The difference can be 5-10 percentage points depending on your business model. I've also found that combining gross margin analysis with cash conversion cycle insights gives you a much sharper picture than either metric alone. A business can maintain healthy gross margins while going cash-flow negative if inventory sits too long or receivables drag. I use a combined dashboard that tracks gross margin alongside days inventory outstanding and days sales outstanding. It takes about twenty minutes a month to update, and it's saved me from making several expensive hiring and inventory decisions that would have looked fine on a standalone gross margin report. The main limitation of gross margin as a diagnostic tool is that it says nothing about operating expenses. A company can have 60% gross margins and still be unprofitable if overhead consumes everything above the line. Don't mistake gross margin for the whole story. It's a necessary signal, not a sufficient one. Pair it with operating margin and free cash flow for actual financial health assessment.
If you want a practical starting point, pull your last twelve months of P&L data, calculate gross margin by month, then by product category, and plot the trend. Any deviation larger than five percentage points from your trailing average deserves a footnote explaining what caused it. Keep that footnote system for a year. The pattern you'll find in those footnotes is usually more valuable than the raw percentages themselves.