
Capital Intensity Ratio — How to Read It Without Getting Fooled
The capital intensity ratio measures how much fixed capital a company needs to generate each unit of revenue. You calculate it by dividing total fixed assets by total revenue, usually expressed as a decimal or a percentage. The number itself is simple. Reading it correctly is where most people get it wrong. Unlock The Secrets Of Your Business Demystifying The Capital Intensity Ratio I have spent more years than I want to admit watching people misinterpret this ratio. A high number does not automatically mean bad efficiency. A low number does not automatically mean a strong business. The ratio is a starting point, not an answer. The real work comes after you compute it.
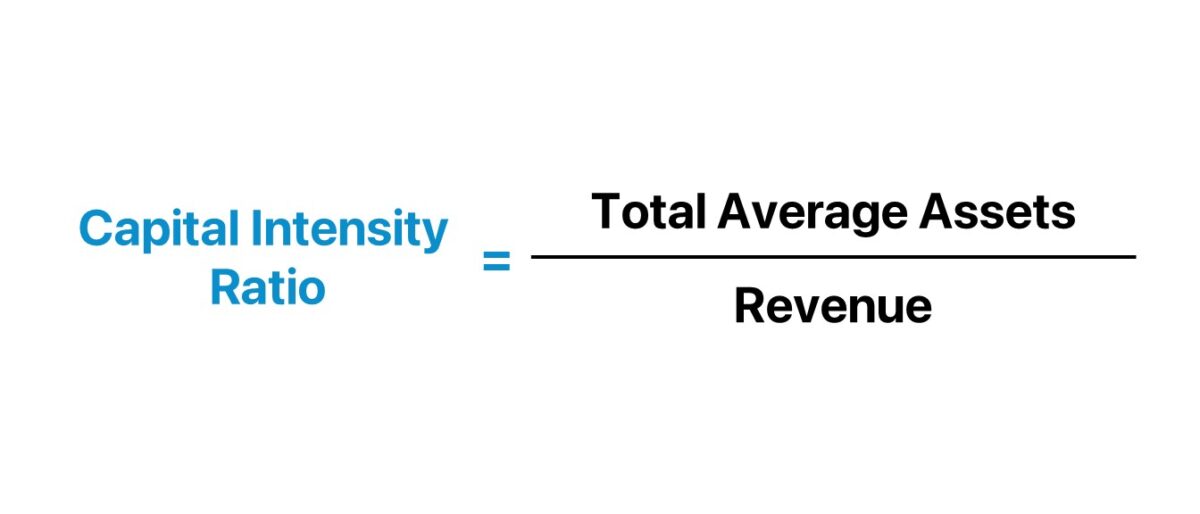
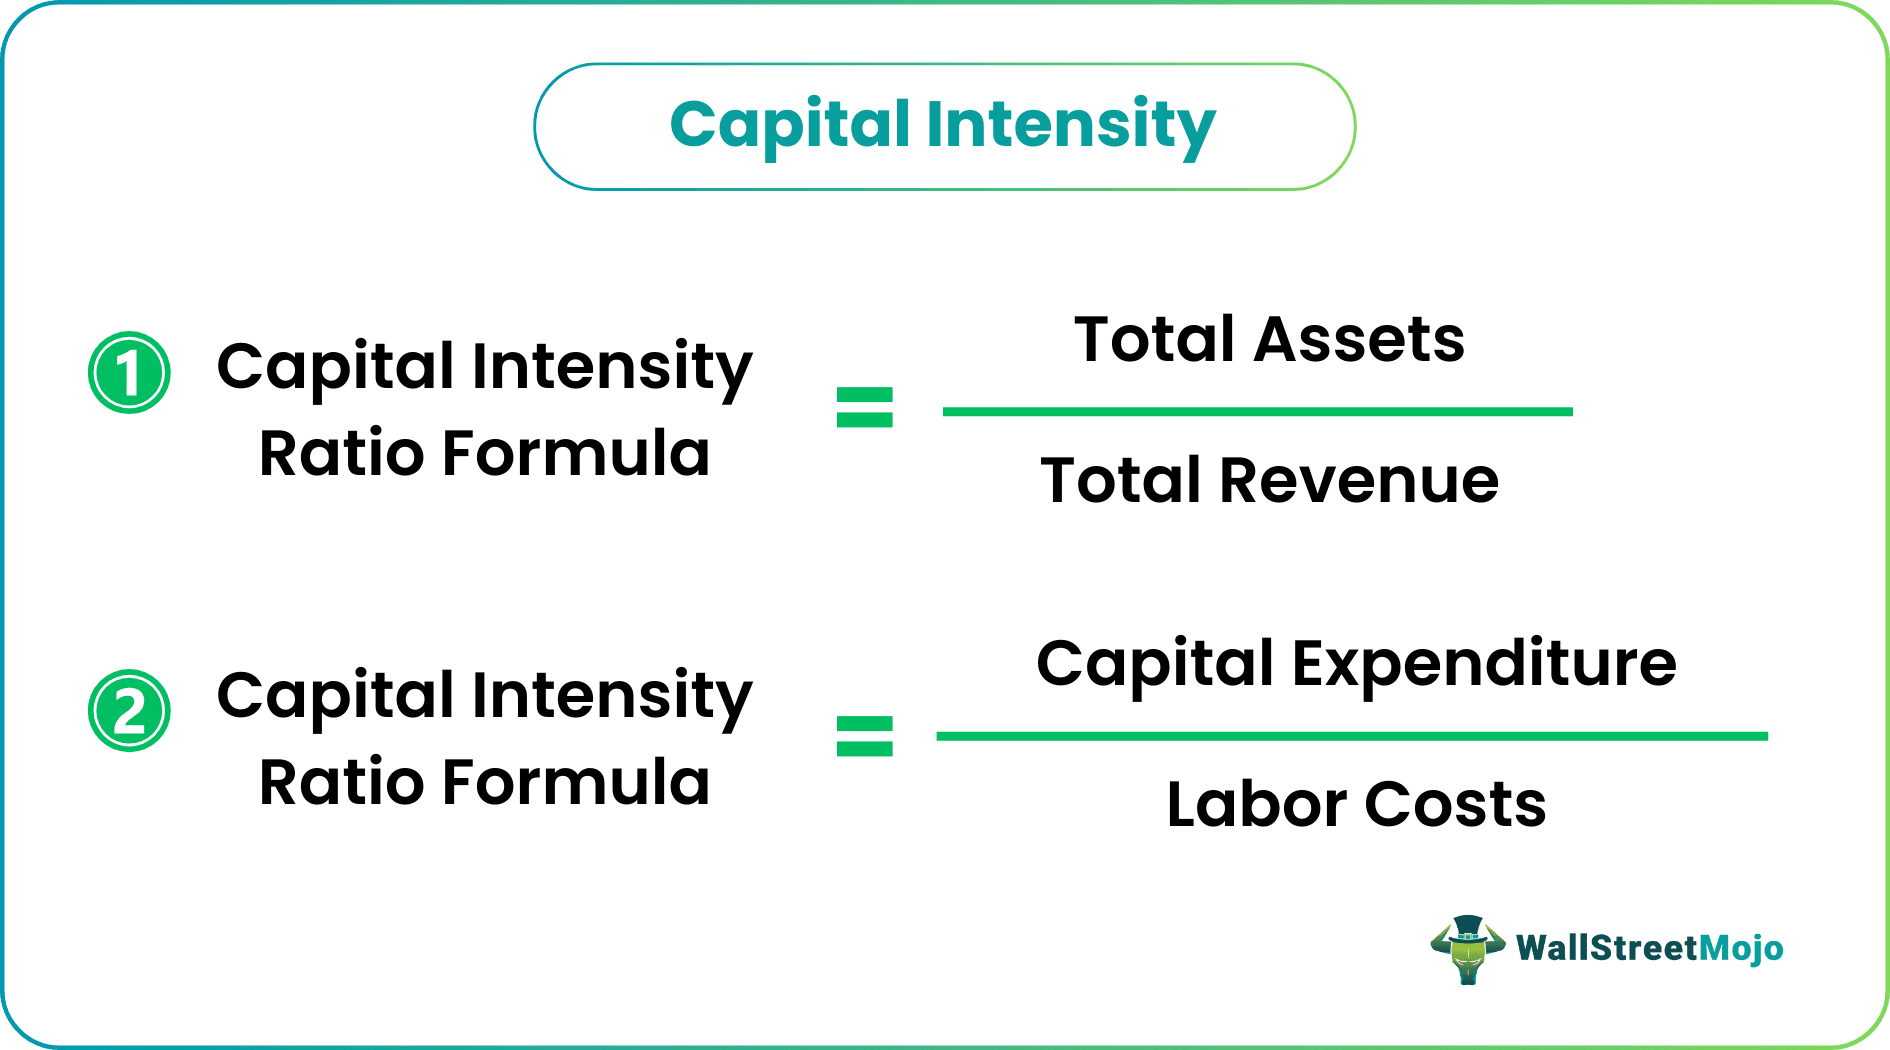
The basic formula is: Capital Intensity Ratio = Total Fixed Assets / Revenue. Some analysts use net fixed assets instead of gross, which creates a meaningful difference in interpretation. Using net values makes the ratio look lower because accumulated depreciation reduces the numerator. Both approaches are technically valid, but mixing them without noticing will produce inconsistent comparisons across companies. Here is what most guides do not tell you. The capital intensity ratio is highly dependent on accounting methods. If Company A uses straight-line depreciation and Company B uses accelerated depreciation, their capital intensity ratios will look completely different even if both own identical assets. Book value, not replacement cost, drives the ratio. That alone makes cross-company comparisons unreliable unless you adjust for depreciation policy differences. I dealt with a situation where a regional manufacturing client had a capital intensity ratio that spiked from 1.8 to 2.4 between two fiscal years. Everyone in the room assumed efficiency was collapsing. I checked the cash flow statement and found the spike came entirely from a single asset acquisition in the third quarter, with depreciation still in its early low-deduction phase. The ratio normalized back to 2.0 by year-end once the asset base was fully reflected in depreciation expense. A single-period reading would have triggered a completely wrong strategic conversation.
The workaround I use is straightforward. Always compute the ratio using average fixed assets over the period rather than a single year-end snapshot. Average the beginning and ending net fixed asset balances. This smooths out seasonal capital deployments and gives you a number that actually reflects operational efficiency over the full period. For quarterly tracking, use the average of the current quarter-end and the prior quarter-end fixed asset balances. This simple adjustment usually reveals trends that point-in-time calculations obscure entirely. Another practical nuance involves what belongs in the fixed asset category. Operating leases, right-of-use assets under ASC 842, and capital leases all change the numerator depending on how they are classified. Companies that recently adopted lease accounting standards show higher capital intensity purely from a classification change, not from any real increase in capital commitment. If you are comparing pre- and post-adoption periods, note the lease treatment or normalize both periods to the same standard before drawing conclusions. Let me walk through a specific example. A mid-sized construction equipment rental firm reports net fixed assets of 42 million and annual revenue of 28 million. The raw capital intensity ratio is 1.5. Another firm in the same sector shows 0.8. The second firm looks more efficient on paper. But the first firm owns its fleet outright while the second firm leases 60 percent of its equipment off-balance-sheet. When you account for the operating lease obligations and add them back to the asset base, the first firm's adjusted ratio drops to 1.1. The second firm's adjusted ratio rises to 1.3. The initial conclusion flips completely. This is exactly why you need to look past the headline number.
Get the Full Details
One of the least discussed problems is that the capital intensity ratio breaks down in service-oriented businesses where fixed assets are minimal by design. Software companies, consulting firms, and digital marketplaces routinely report ratios below 0.2. That does not mean they are capital-efficient in any meaningful strategic sense. It means their value drivers are intangible. Running capital intensity analysis on these businesses gives you a number that sounds precise but carries almost no diagnostic information. Pair it with gross margin trends and headcount metrics if you insist on using it, but do not treat it as a standalone indicator. A counter-intuitive insight worth remembering: capital-intensive businesses often trade at lower multiples precisely because high capital intensity signals lower free cash flow conversion. Investors penalize companies that require heavy ongoing reinvestment just to maintain revenue levels. The market rewards capital-light models for the same reason. This dynamic creates a persistent valuation gap between sectors that has nothing to do with operational quality and everything to do with capital structure expectations. Tracking this ratio requires consistency in your data sources. Pull fixed asset figures from the balance sheet line items labeled property, plant, and equipment. Verify whether goodwill and intangible assets are included in the total you are using. They should not be. Including them inflates the numerator and distorts the ratio for any asset-heavy company. Net PP&E is the correct numerator for standard analysis.
Revenue on the denominator side should be operating revenue, not total revenue including interest income or gains from asset sales. Using total revenue introduces noise from non-operating items that have no relationship to capital efficiency. Stick to the top line from operations. This keeps the ratio focused on what it is supposed to measure. For practical application, I recommend computing this ratio monthly for the first quarter after a major capital investment, then switching to quarterly tracking once the asset base stabilizes. The first quarter after a significant purchase will always show an elevated ratio. Do not treat it as a structural problem. The ratio typically improves within four to eight quarters as revenue from the new capacity ramps up and depreciation begins to absorb the asset cost. Monitoring the trajectory matters far more than any single reading. If you want to automate this, you can build a simple spreadsheet model. Download my template here for a starting framework. The model pulls net PP&E and operating revenue from standard financial statement lines, calculates the ratio using averaged balances, and flags periods where the ratio changes by more than 15 percent quarter over quarter. That threshold catches significant shifts without generating false alarms from routine depreciation cycles.
The limitations of this metric deserve equal attention. Capital intensity ratios become nearly useless during periods of hyperinflation or rapid currency devaluation, because historical cost fixed assets fail to reflect current replacement values. A company operating in an emerging market with a depreciating local currency may show a declining ratio that looks like improving efficiency when it is actually just a translation artifact. Adjust for currency effects if you work across geographies, or compare using constant-currency revenue figures. Another scenario where the ratio fails completely is during active divestitures. Selling off a major asset class reduces the numerator without an immediate drop in revenue, causing the ratio to fall artificially. The company may appear more efficient on paper while actually reducing its productive capacity. Always cross-reference any ratio decline with notes on asset sales or business segment exits. For industries where capital intensity truly defines competitive advantage, like telecommunications, energy, and heavy manufacturing, the ratio should be tracked alongside return on invested capital. A company with a high capital intensity ratio that also delivers strong ROIC is deploying its capital efficiently. A company with a high ratio and declining ROIC is consuming capital without generating proportional returns. These two metrics together tell you whether heavy capital investment is a strength or a slow drain on shareholder value.
The final thing to remember is that this ratio is backward-looking by nature. It reflects the asset base that already exists, not the capital that needs to be deployed going forward. Planning committees that rely solely on historical capital intensity ratios for budgeting will consistently underestimate future capital requirements during growth periods. Pair this metric with projected capex schedules and capacity utilization rates to get a complete picture of where the business is heading. I stopped trying to force this ratio into decision-making frameworks where it does not belong around ten years ago. It works well for operational benchmarking within the same industry and for tracking capital deployment efficiency over time. It fails when used as a universal comparative tool across sectors or as a standalone investment signal. Treat it as one input among many, not as a verdict.


