How The Military Pay System Actually Works (Before You Trust Any Guide)
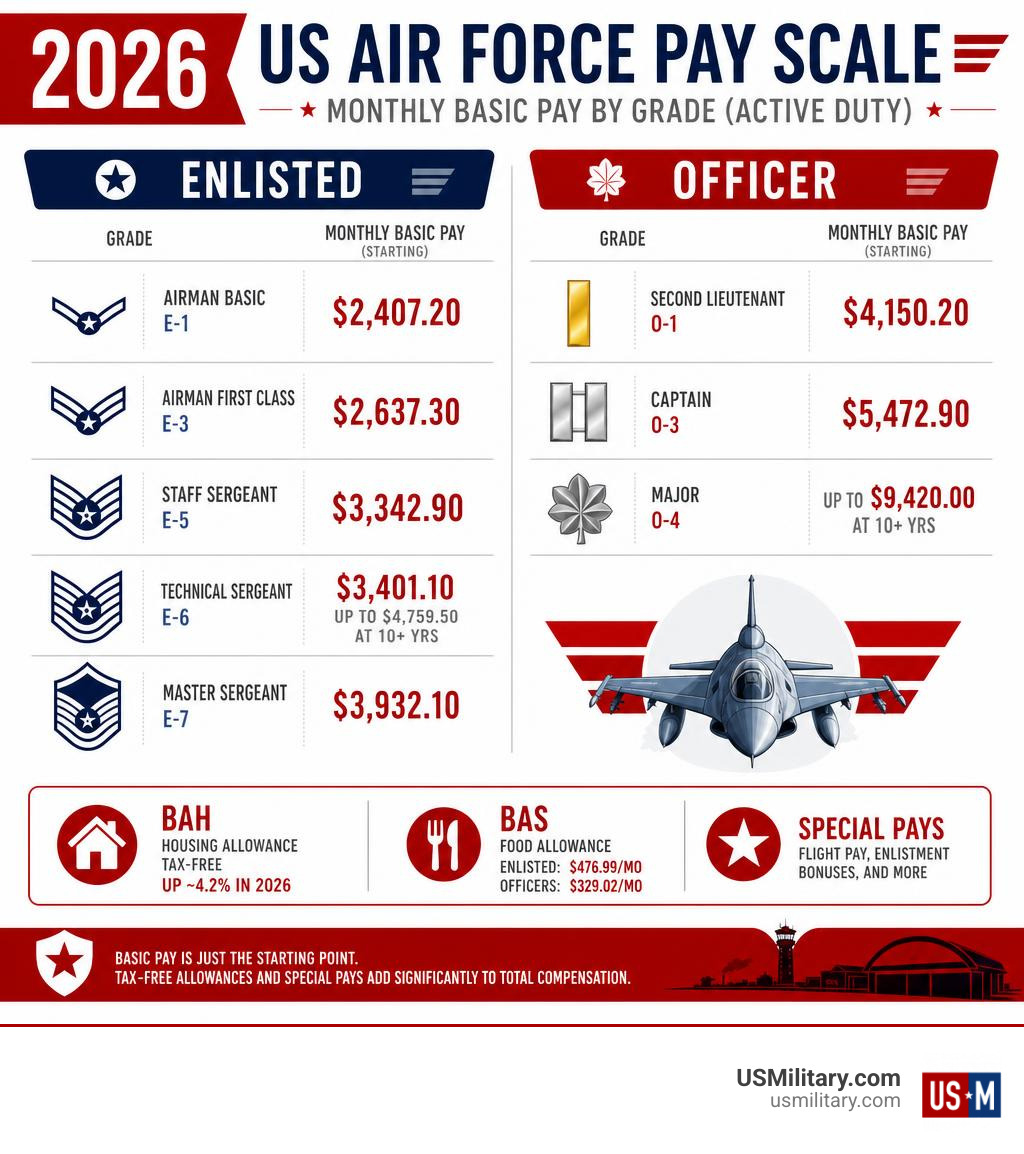
The pay system for enlisted Airmen runs on two tracks that don't overlap the way people assume. Base pay is purely a function of rank and time in service, calculated monthly by the Defense Finance and Accounting Service. Everything else is either a flat allowance or a reimbursement tied to actual costs. That distinction matters more than most guides admit. Base pay follows the military pay tables published annually. As of 2024, an E-1 with less than four months of service makes $1,786.50 per month. An E-7 with twenty years pulls in roughly $5,559.60. Those numbers are straightforward but they represent only about sixty to seventy percent of actual take-home for most airmen. The rest comes from allowances and special pays that most people don't account for when they budget. Here's what actually trips people up. The Basic Allowance for Housing, or BAH, is not a uniform payment. It changes based on your home of record zip code, your rank, and whether you have dependents. A senior E-6 stationed in San Diego gets a dramatically different BAH rate than the same rank in Lubbock, Texas. The difference can be over a thousand dollars a month. Most online calculators get this wrong because they default to the "with dependents" rate even when the airman is single and lives in government housing.
The Basic Allowance for Subsistence covers food at a flat rate. Right now that's about $462 per month for all enlisted ranks. It doesn't scale with weight, activity level, or actual food consumption. It just scales with nothing. You eat on your own dime within that amount unless you qualify for additional feeding allowances through deployment or operational conditions.
Special Pays That Change Everything
This is where the real compensation happens and also where most people leave money on the table because they don't know what applies to them. Aviation Risk Pay kicks in at $150 a month once you log twenty hours of flight time in a single month. It's not automatic. You have to be certified as a qualified aircrew member or assigned to an aviation duty position. I watched three people in my squadron miss out on this for eighteen months because their supervisor never submitted the paperwork. The pay was there. Nobody filed the form. Hazardous Duty Pay varies by qualifier. Jump pay is $225 per month for twelve qualified jumps. Flight deck hazard pay for aviation ordnance folks runs higher. Dental armorers, explosive ordnance disposal technicians, and parachute rescue swimmers all have different rates. The cumulative effect of stacking two or three of these can add five hundred to eight hundred dollars monthly to your check. It's not sexy. It's also not guaranteed. Each one requires a formal qualification and annual recertification. Language Proficiency Pay is another one nobody talks about. If you're certified at the intermediate level or above in a designated language through the Defense Language Proficiency Test, you get between $100 and $400 per month depending on fluency level and whether the language is on the critical list. I had a comms tech who picked up conversational-level Arabic and started pulling an extra $300 monthly. He studied for three weekends every month for about six months. The return on investment was absurdly high for something most people treat as a side hobby.
Get the Full Details

The Education and Benefit Side
Montgomery GI Bill benefits have been cut significantly from the old version. The Current Choice plan pays roughly $450 per month for up to thirty-six months while you're using it for school. That's after taxes. The old 36-month rule still exists but many people don't realize they can combine remaining Montgomery GI Bill months with the Post-9/11 GI Bill in certain configurations. It depends on your entry date and which program you elected when you joined. Tuition assistance covers up to 100 percent of in-state public college tuition at the standard rate caps. That's usually $250 per credit hour with a yearly cap around $4,500. Private schools and out-of-state programs exceed those caps and the air force covers a percentage of the overage up to a federal limit. During the peak deployment cycles I've seen, TA approval times stretched to three weeks because the education counselors were overwhelmed. File your TA requests early in the semester, not during add/drop week. Healthcare through Tricare Prime is effectively zero-cost when you use it. There's no premium, minimal copays, and referrals are handled within the system. The downside is that you're locked into a specific geographic catchment area and finding providers who actually accept Tricare Prime in rural bases has gotten harder. My workaround was switching to Tricare Select when wePCS'd to a remote station and paying the monthly premium out of the BAH difference. The annual deductibles on Select are reasonable compared to the quality-of-life tradeoff of driving two hours for a primary care visit.
Retirement And The Blended System
The Blended Retirement System changed everything for anyone who joined after 2018. You get automatic contributions to the Thrift Savings Plan equal to five percent of your basic pay, and you can contribute up to an additional five percent to get the full match. That's essentially free money that compounds over your career. Someone who stays twenty years and maxes out their TSP contributions with the matching funds could have well over half a million dollars at retirement age from that bucket alone, assuming average market returns. Most Airmen don't maximize it because they don't understand how the match works or they're living paycheck to paycheck on base pay alone. The pension side of BRS is reduced compared to the old system. You vest at twenty years and the multiplier is 2 percent per year of service instead of 2.5 percent. For a twenty-year E-7, that's a monthly pension of roughly $3,500 to $4,000 depending on exact time in service. Combined with TSP, VA disability if applicable, and social security later, it forms a floor that most civilian entries at equivalent pay grades don't reach until much later in their careers.
Real Problems People Hit
One thing I learned the hard way involves the Survivor Benefit Plan. It costs about 6.5 percent of your chosen annuity base, and the annuity base is typically 55 percent of your final base pay. For someone making E-7 pay at retirement, that's roughly $225 to $275 per month deducted from your retired pay for the rest of your life, with your spouse or designated beneficiary getting 55 percent of that annuity after you die. The decision to enroll or decline SBP is made at retirement and it's nearly irreversible. I've seen people decline it to boost their monthly check by a couple hundred dollars, then regret it when a spouse outlived them by twenty years. The math is brutal if you live past sixty-five. Another issue is BAH miscalculation during dependent changes. If you get married or have a child while stationed overseas and your sponsor's location has a different BAH rate structure, you need to update your DEERS information immediately. The system doesn't auto-adjust. I knew someone who was underpaid by nearly four hundred dollars a month for eight months because his wife's address update in DEERS lagged behind their actual marriage date. The back pay came through eventually but the paperwork took six months of follow-up with the finance office.

Where To Actually Find The Data
The official pay tables are at dfas.mil. They publish the annual military pay chart in January each year with rates effective the following month. The BAH rates are separate and broken down by zip code with dependency status, also updated annually in July. Don't trust third-party calculators that haven't been updated since the last pay raise. The gap between a current and outdated calculator can be several hundred dollars a month if the last raise was significant. For allowances and special pays, your unit's headquarters personnel flight or the installation's finance office will have the current qualifier lists. Those lists change. A qualifier that paid hazard pay last year might get removed or have its rate adjusted. Always verify against the current DoD directive rather than assuming continuity from year to year. The TSP and retirement information lives at tsp.gov and milconnect.dfas.mil. Those are the sources. Everything else is interpretation, and most interpretation online is either oversimplified or aimed at recruiters rather than people trying to actually plan their finances. The system is not optimized for clarity. It's optimized for administrative processing. You'll figure it out faster if you go straight to the primary sources and treat every guide you find as a starting point rather than a reference.