The Ulta Mastercard: What It Actually Is and Whether You Should Get It
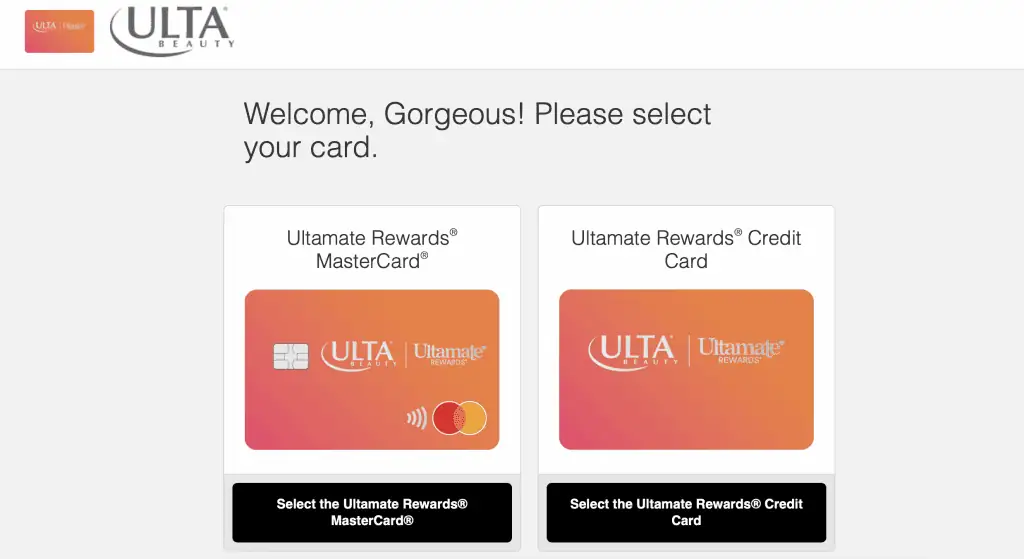
The Ulta Mastercard is a store credit card issued by Comenity Bank. It gives you perks at Ulta Beauty, the largest beauty retailer in the United States. I have used this card for years. I also see people get confused about it constantly, so here is what I know about how it works in practice. There are three versions of this card now. The original Ult Rewards Mastercard. The Gold version. The Platinum version. They are not equal in benefits. People assume they are the same product with different branding. They are not. Here is the breakdown of what each tier actually gives you. The rewards structure matters more than people realize. Most cardholders only use the basic tier and miss out on meaningful savings because they do not know how the reward stacking works.
Ult Rewards Mastercard (standard tier): You earn 1 point per dollar on everything except Ulta purchases. On Ulta purchases, you earn 2 points per dollar. Points are worth 1 cent each when redeemed for merchandise credit. So 100 points equals $1 off your next purchase. That is the baseline. Ulta Mastercard Gold: You get 2 points per dollar on all purchases, not just at Ulta. Plus you earn 6 points per dollar when shopping at Ulta. You also get a $10 birthday gift every year. This one is closer to a general rewards card with a strong Ulta bonus. Ulta Mastercard Platinum: This is the top tier. You earn 3 points per dollar everywhere. At Ulta, you earn 8 points per dollar. The birthday gift is bigger too. You get early access to sales and exclusive events. If you shop at Ulta regularly, this is the only version that makes financial sense beyond the basic card.
How The Rewards Actually Work In Practice
I learned this the hard way during my first year with the card. I thought earning points at Ulta was automatic and linear. It is not. There is a critical detail most people miss. When you make a purchase at Ulta, the points post based on the amount you actually spend after coupons and discounts. Not the original price. Not the tagged price. The final charged amount. I once bought a set marked $45, used a 20% off coupon, and paid $36. I expected points on $45. I got points on $36. The difference felt small but it adds up over a year of beauty purchases. Another edge case that trips people up. Ulta sometimes runs events where you earn bonus points on top of your normal earn rate. Like 10 points per dollar during a special weekend. These events are not advertised on the card website. They come through email or in-store signage. If you are not paying attention, you leave free money on the table.
Get the Full Details
Here is a workaround I use now. I check Ulta's "Rewards Events" page before every big shopping trip. It is hidden under the rewards section of their website. You can see upcoming bonus point days and plan your purchases around them. I moved a $200 skincare haul from a regular day to a 3x points event weekend. That turned 600 points into 1800 points. Almost an extra $12 in merchandise credit for something I was already going to buy.
How To Apply and Get Approved
You apply on ulta.com or in-store. The application is instant. You get a decision within seconds. I have seen people denied on the spot and others approved with a $1500 limit on their first try. Credit score usually needs to be in the fair to good range, which means roughly 670 and up. One thing nobody tells you. Getting approved does not guarantee you will get the Platinum tier immediately. The tier you receive depends on your credit profile. I have seen friends apply expecting Platinum and get the basic card instead. There is no way to choose your tier at application. You either qualify or you do not. If you get denied, do not reapply immediately. Each application creates a hard inquiry on your credit report. Multiple inquiries in a short window lower your score and make future approvals harder. Wait six months before trying again.
What The Card Is Good For
If you shop at Ulta more than four times a year, the card pays for itself. The free shipping on all Ulta orders is a solid perk. The extended returns window gives you more time to decide if a product works. And the points add up faster than most people expect. I calculated this once. Over twelve months, I spent roughly $1200 at Ulta across various purchases. On the Gold card, that earned me about 7200 points plus the Ulta-specific bonus points pushing it higher. At redemption, that translated to around $70 to $85 in merchandise credit. That is not nothing. It covers a few full-size products or gets you close to a wanted set.

Where The Card Falls Short
The interest rate is steep. The APR sits around 29.99%. If you carry a balance from month to month, the interest charges wipe out any rewards you earn within three months. I watched someone earn $40 in rewards and lose $65 in interest because they thought the card worked like a regular credit card with a grace period. It does not. The grace period is very limited on this card. Another limitation. The card only offers significant value at Ulta. Outside of Ulta, the returns are mediocre. The Platinum tier improves this slightly, but it is still a beauty store card disguised as a general rewards card. If you do not shop at Ulta, this card is a bad choice. Comenity Bank customer service is not great. I have called twice about point discrepancies. Both times I waited thirty minutes on hold. The agents were knowledgeable but the system has known bugs where points do not post correctly after returns. If you return an item, check your point balance within 48 hours. If points disappeared and did not reappear after the return processed, call immediately. Do not assume it will fix itself.
Should You Get It?
Get the Ulta Mastercard if you already shop at Ulta regularly. Pick the highest tier you qualify for. Pay it off in full every month. Track rewards events before buying. If you can do all of that, the card is genuinely useful. Avoid it if you shop at Ulta less than twice a year. The mediocre rewards outside Ulta do not justify opening another credit account. Your existing general rewards card probably serves you better. A card like the Chase Freedom Flex or Citi Double Cash gives you better returns on everyday spending and does not trap you into shopping at one store. Also avoid it if you struggle with carrying balances. The high APR is designed to catch people who do not pay in full. The rewards are real. The interest costs are worse.
The Bottom Line
The Ulta Mastercard is not a secret weapon. It is a straightforward store card with tiered benefits. The Platinum version is worth having if you qualify and shop at Ulta. The basic card is acceptable if you are already a customer. Just read the fine print on interest rates and rewards posting. The card works as advertised if you understand how it works.