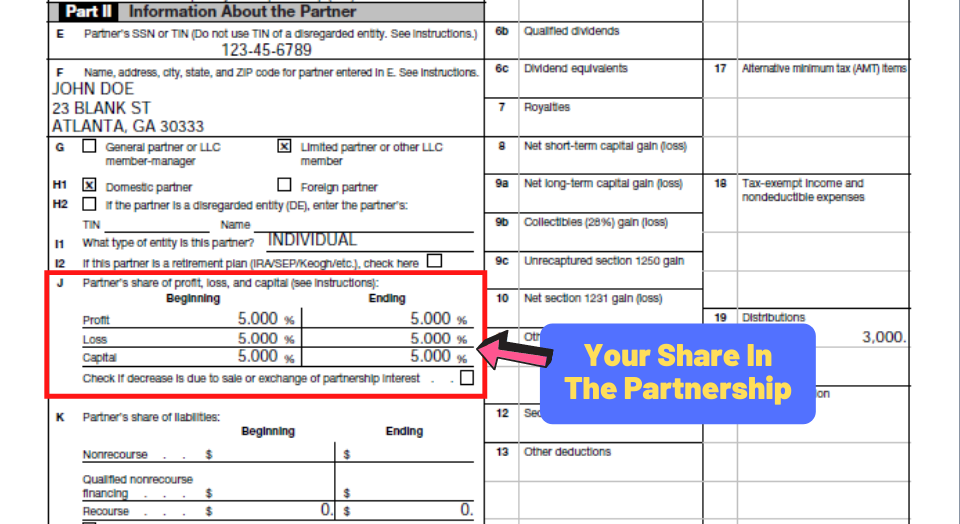
Working with Partnership Allocations and the K-1 You Actually Receive
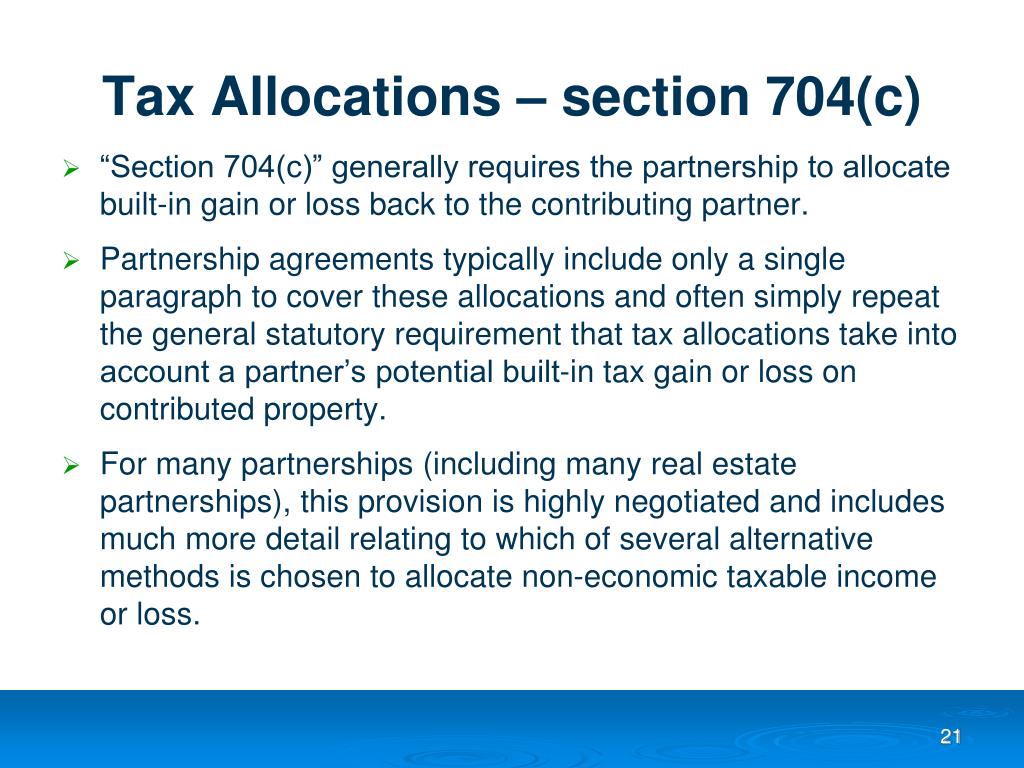
Section 704(c) exists because partnerships let partners contribute property with built-in gain or loss, and the tax code needed a way to prevent the subsequent allocation of that pre-contribution item from going to someone who didn't originally own it. That is the entire reason the rule exists. It is not complicated in theory, but the mechanics on a real K-1 can eat your evening if you are not paying attention to which bucket each line item belongs to. When I first started reviewing K-1s from venture funds and real estate partnerships, I treated every box like it carried equal weight. That approach failed me on a 2018 filing where I missed that half of the distributable cash was actually a return of capital masked inside a distribution line that looked identical to ordinary income. The partner who contributed the property with the built-in gain had their allocation separated under 704(c), but the K-1 did not label it in a way that jumped off the page. I spent three hours untangling it by pulling the schedule K-1 supplementary pages and cross-referencing the contribution records from the original subscription documents. The section requires that when a partner contributes appreciated or depreciated property to a partnership, the partnership must allocate the pre-contribution gain or loss specifically to that contributing partner when it is eventually realized. This separation persists regardless of what the partnership agreement says about profit and loss sharing. The partnership agreement can allocate everything 50-50 on paper, but for tax purposes the built-in gain from the contributed property still tracks back to the person who brought it in.
There are three methods allowed under the regulations. The traditional method is the default and simplest to apply. It allocates the 704(c) adjustment only when the specific property is disposed of. The remedial method was designed to fix distortions that arise when the book basis and tax basis diverge significantly. It creates synthetic income allocations to keep the partners' tax positions aligned with their economic interests. The curative method sits between those two approaches and allows the partnership to use available items to offset discrepancies without creating new ones. I found that most mid-market partnerships use the traditional method because it is administratively cheaper, even though it can produce timing mismatches that hurt non-contributing partners in certain liquidation scenarios. The remedial method sounds better in theory but requires the partnership to maintain additional tracking documentation that many smaller funds do not want to deal with on an ongoing basis.
How the K-1 Reflects 704(c) Allocations in Practice
Your K-1 will show you the standard boxes: ordinary business income in box 1, guaranteed payments in box 2, interest income in box 3, and so on. But buried within those numbers, or sometimes on the attached schedules, are the 704(c) adjustments that determine your actual tax liability. The key is that 704(c) items typically appear as separate lines on the supplemental schedules rather than in the main body of the form. If you only look at box 1 and walk away, you are missing material tax items. Specifically, you need to watch for these line items. Section 704(c) gain or loss on disposition of contributed property. Book-tax basis differences that get amortized or depreciated differently. Contributions of property with built-in gain that later gets refinanced or revalued. These items do not always flow through to your individual return automatically. You may need to attach additional forms or make elections to report them correctly. I once worked with a partner who received a K-1 showing a small ordinary loss in box 1 but had significant 704(c) gain buried in the supplementary pages that was not captured in any of the standard boxes. The partnership had sold a building that was originally contributed with substantial appreciation, and the gain allocation under 704(c) was separate from the current year operating results. Had I only looked at box 1, the partner would have understated taxable income by roughly forty thousand dollars for that year.
Get the Full Details

Common Mistakes That Cost People Money
The first mistake is assuming that the percentage allocation in the partnership agreement controls the tax allocation. It does not for 704(c) items. The tax allocation follows the property contribution history, not the profit-sharing ratio. I have seen this trip up investors in both real estate syndications and private equity funds where the economics say one thing and the tax treatment says another. The second mistake involves ignoring the timing difference between book and tax. A partnership might report a loss for book purposes while simultaneously reporting gain for tax purposes on the same transaction because of 704(c) adjustments. This creates a situation where your cash distribution does not match your tax liability, and you need to have liquidity set aside even when the partnership appears to be losing money on paper. The third mistake is failing to track the outside basis through all of these adjustments. Each 704(c) allocation increases or decreases your basis in the partnership interest, and if you do not maintain that tracking yourself, you will miscalculate gain or loss when you eventually sell or redeem your interest. I recommend maintaining a simple spreadsheet that records your initial capital contribution, each year's 704(c) allocations, distributions, and basis adjustments. It takes about twenty minutes per year and prevents painful reconciliation headaches later.
When the K-1 Approach Fails and What to Do Instead
Section 704(c) works cleanly when the partnership holds contributed property until disposition and does not revalue assets frequently. It becomes much messier when the partnership uses temporary allocations, liquidates quickly after contributions, or has multiple contributors bringing in properties with different basis characteristics at different times. In those scenarios, the calculations can become so complex that the administrative cost of getting them right outweighs the benefit of perfect accuracy. If you are dealing with a partnership that has made significant 704(c) adjustments and the K-1 is not providing sufficient detail, your first step should be requesting the partnership's tax basis capital account schedule and the underlying contribution records. The K-1 summarizes everything, but it does not show the mechanics. Without the detailed schedules, you cannot verify that the allocations were computed correctly, and you are taking the partnership's number at face value. In some cases, the partnership may have used an incorrect 704(c) method or failed to apply it to property that should have been covered. I encountered a situation where a partnership had contributed a building with a ten million dollar built-in gain but treated it as a current expense under the operating agreement without recognizing the 704(c) implications. The result was that the gain was being allocated proportionally among all partners instead of being tracked to the contributing partner. Correcting that required an amended return and roughly six months of correspondence with the partnership's tax advisor.
Practical Steps for Processing Your Own K-1 With 704(c) Items
Start by gathering the K-1 and all supplementary schedules. Do not rely on the summary page alone. Look for any line that references section 704(c), book-tax difference, or contributed property adjustment. These are your flags. Next, compare the allocation percentages on the supplementary schedules to the percentages shown in the partnership agreement. They should not match if 704(c) adjustments are present. If they do match exactly, either there are no significant 704(c) items, or the partnership failed to apply the rule correctly. Then calculate your updated outside basis by taking your beginning basis, adding your share of income and 704(c) gain allocations, subtracting distributions and 704(c) loss allocations, and adjusting for any basis differences from prior years. This number determines whether a future distribution or sale triggers gain or loss.
Finally, retain all documentation related to your contribution, including the closing statements, appraisal records, and the partnership's initial capital contribution receipts. If the IRS ever questions the 704(c) allocations, you will need to demonstrate the original basis and the built-in gain or loss at the time of contribution. Without those records, you are relying entirely on the partnership's memory and paperwork, which is a fragile position to be in. The whole process is mechanical once you know where to look. The difficulty is not in the calculation itself but in finding the right information on the forms and understanding which allocations are governed by 704(c) versus the general partnership rules. Most errors come from skipping steps rather than from computational mistakes, so being thorough at the intake stage saves significant time downstream.