Understanding RV Loans and Where They Actually Break Down
RV financing is one of those areas that looks straightforward on the surface until you start digging into the details. I spent about six years working with credit unions and private lenders on dealer floor plans, so I have seen exactly where the standard paperwork falls apart. Most people go into this process thinking they are just buying a vehicle, but an RV is really a hybrid between a car loan, a mortgage, and occasionally a commercial transaction if you are running a rental business. The core difference between RV loans and auto loans comes down to how the collateral is valued and insured. A lender will appraise a used Class A motorhome very differently than a sedan. Depreciation curves for recreational vehicles are not linear. They typically drop steeply in year one, then stabilize, then drop again when major systems need replacement. I once worked with a borrower who had a 2012 Winnebago with 87,000 miles. The lender valued it at $62,000 based on NADA guides, but the actual market value was closer to $48,000. The gap came from the new clutch and resurfaced flywheel that needed immediate work. That mismatch is why loan-to-value ratios matter more than your credit score in many cases. One counter-intuitive thing about RV financing is that having excellent credit does not guarantee the best rate. Lenders care more about the debt-to-income ratio and the loan-to-value percentage. I had a situation last year where a borrower with a 780 FICO score got turned down because the RV was a 2015 model with over 100,000 miles. The same borrower, with the exact same credit, would have been approved at 6.5 percent if they had put 30 percent down instead of 15 percent. The lender viewed the older unit as high risk regardless of the credit profile.
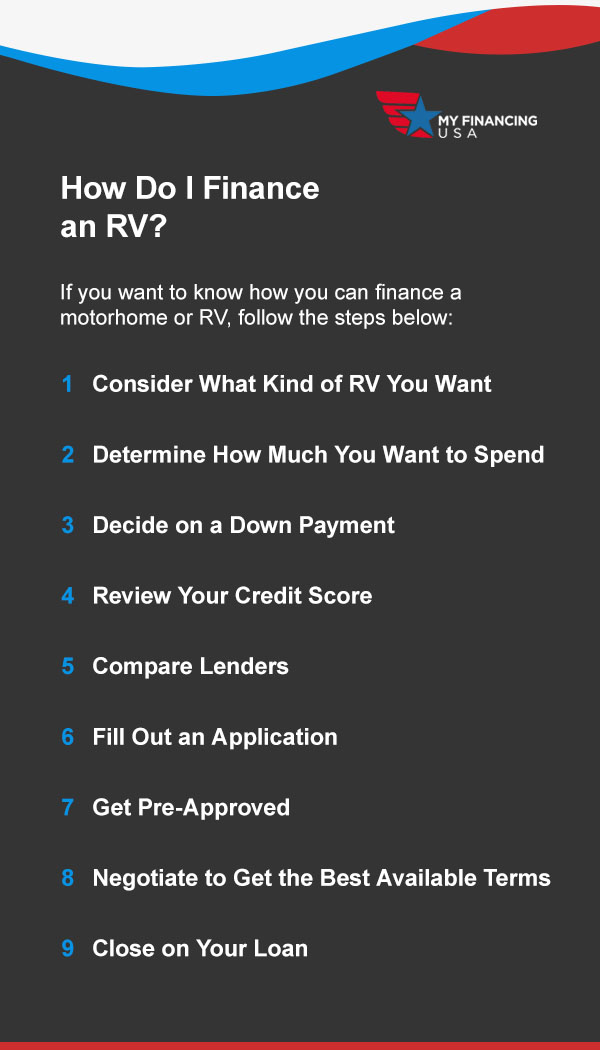
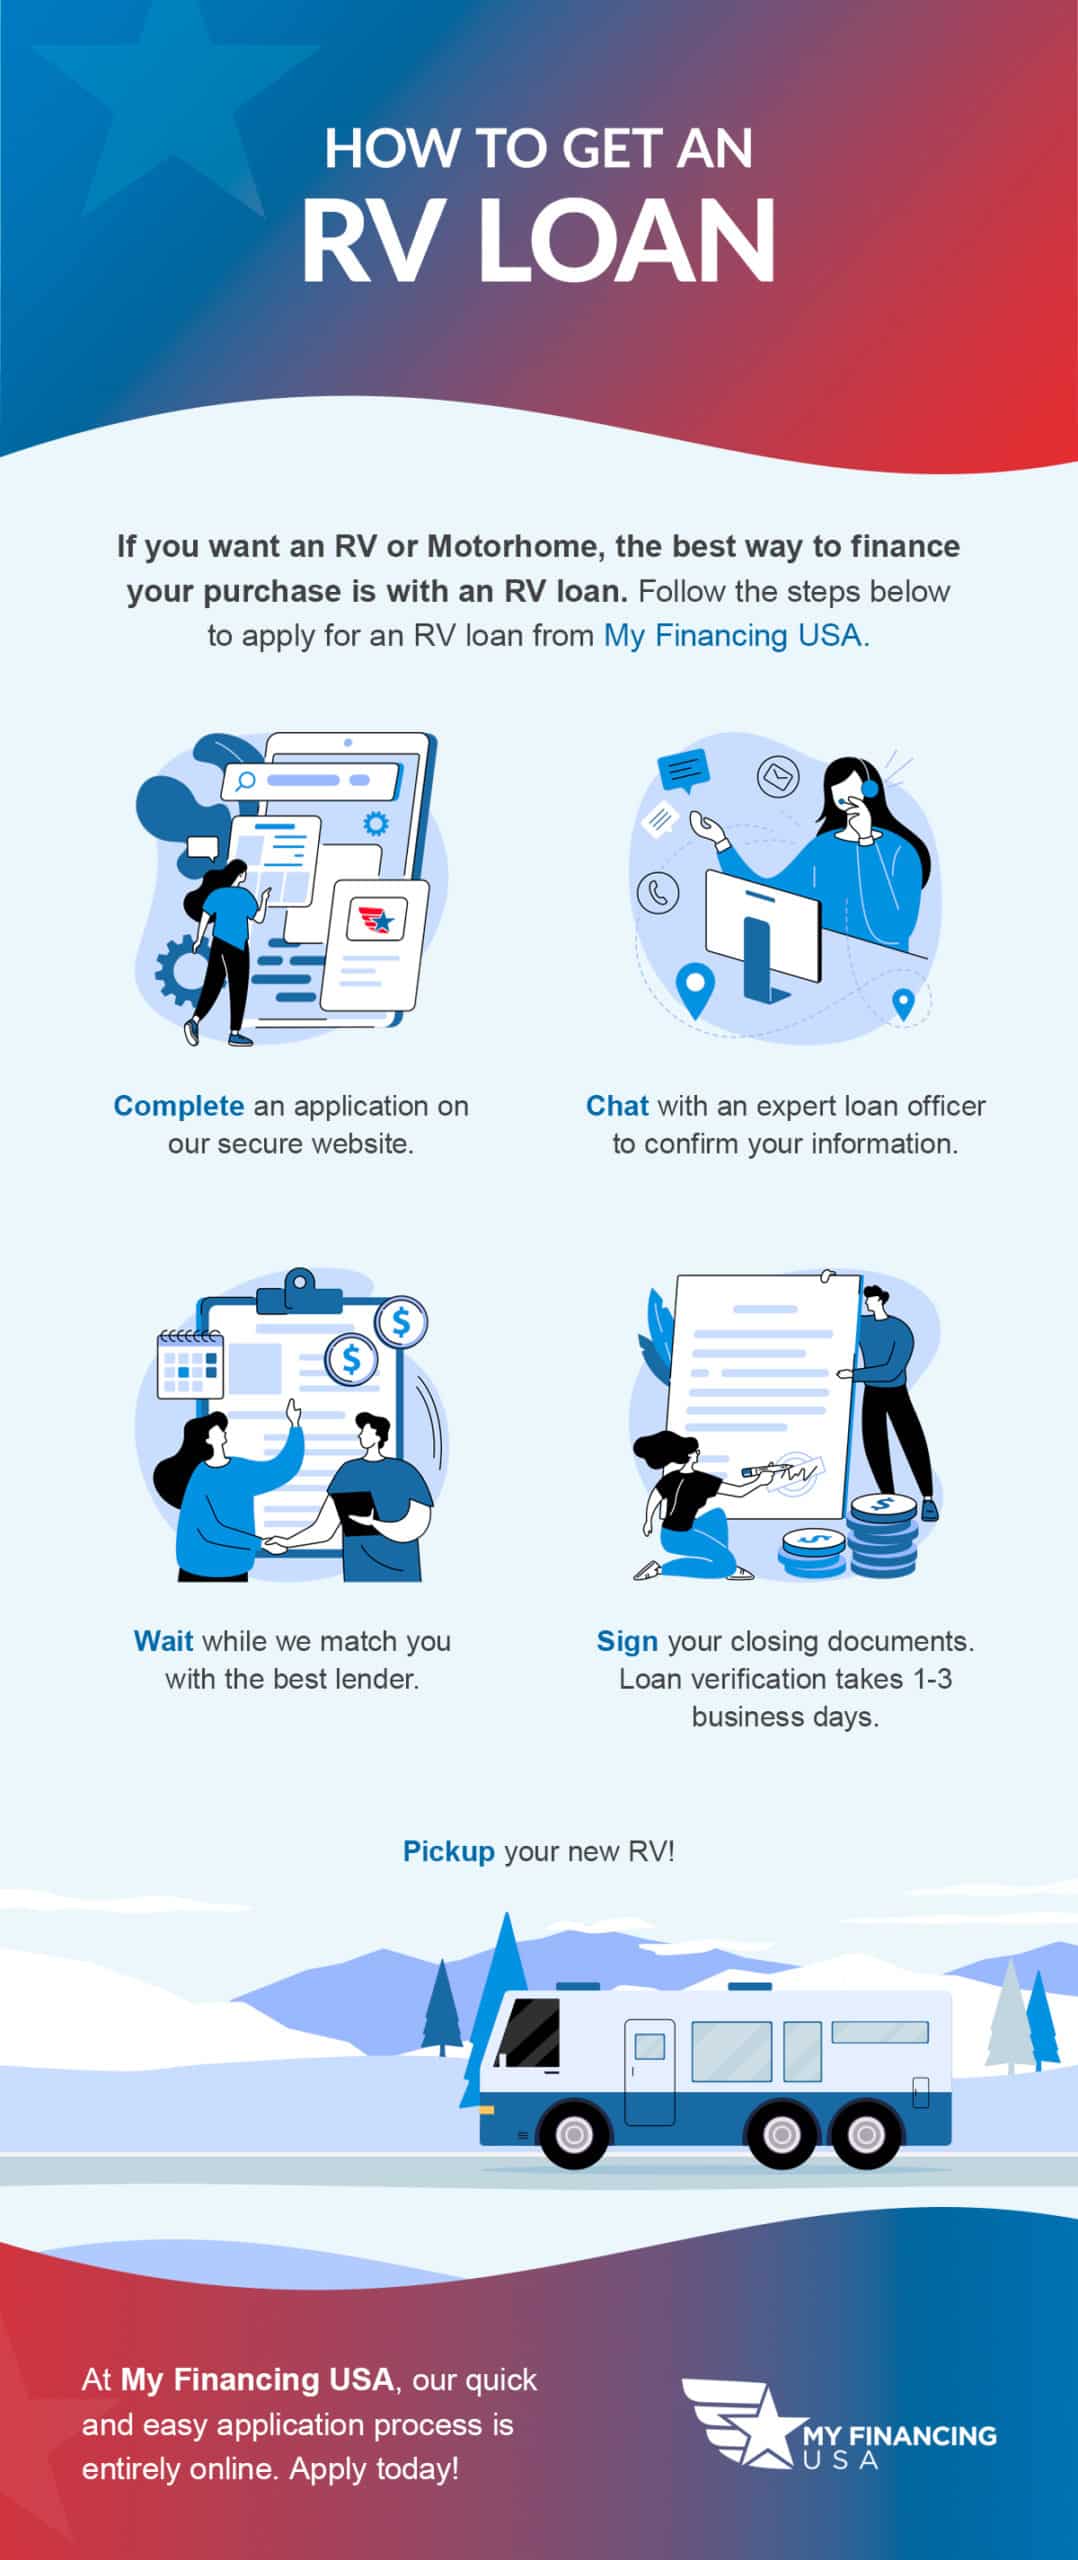
Here is how the process actually works step by step. You start with pre-approval before you even look at listings. This gives you a hard number instead of a vague budget range. Next, you get a third-party appraisal if the RV is used and over five years old. Most lenders require this for units past the warranty period. Then comes the insurance quote, which must meet the lender minimums for comprehensive and collision coverage. Finally, the closing documents get reviewed, usually taking two to three business days for approval and funding. The biggest pitfall I see repeatedly is people skipping the pre-inspection. You think you are getting a deal on a used Grand Design or Airstream, but hidden issues with the roof sealants, slide-out mechanisms, or propane systems can cost thousands. I once saw a buyer sign closing documents on a 2018 Forest River with cracked sealant around all three roof vents. The repair estimate came to $4,200, which erased any savings from the purchase price. Always budget for an independent inspection before finalizing financing. Another thing beginners miss is the difference between secured and unsecured personal loans for RV purchases. Some lenders offer unsecured options for newer models under 2018 with less than 50,000 miles. The rates are usually 1 to 2 percent higher than secured loans, but the application process is faster. If you need to close within a week during a competitive market, an unsecured loan might be worth the extra cost. Secured loans take longer because the lender needs to verify the title and lien status, which can add five to ten business days to the timeline.
For those of you looking for detailed documentation on the underwriting process, there are some resources available. You can find comprehensive guides that break down the entire workflow, including forms and checklists. One solid reference point is Unlock The Secrets Of RV Financing Your Comprehensive Guide To Ioscpseg Usesc, which covers lender requirements, appraisal standards, and common approval pitfalls. It is not an official publication, but it compiles practical information from people who have actually closed these deals. There are scenarios where RV financing simply does not work well. If you are trying to finance a vintage trailer from the 1960s, most institutional lenders will decline. The collateral is too illiquid, and resale values are unpredictable. In those cases, you need to look at specialty lenders or consider private financing through RV dealer networks. Another limitation is the age cutoff. Many lenders will not finance units older than 15 to 20 years unless you have substantial equity or a co-signer with strong income verification. The bottom line is that RV loans require more upfront preparation than auto loans. Factor in an extra two to three weeks for the full approval process, including inspections and insurance. If you rush into closing without verifying the unit condition or shopping multiple lenders, you will likely end up with a rate that is 0.5 to 1.5 percent higher than what you could have secured. Get your numbers in order first, then let the lending process do its work.
Get the Full Details