Asset Turnover Ratio: What It Actually Tells You About Your Business
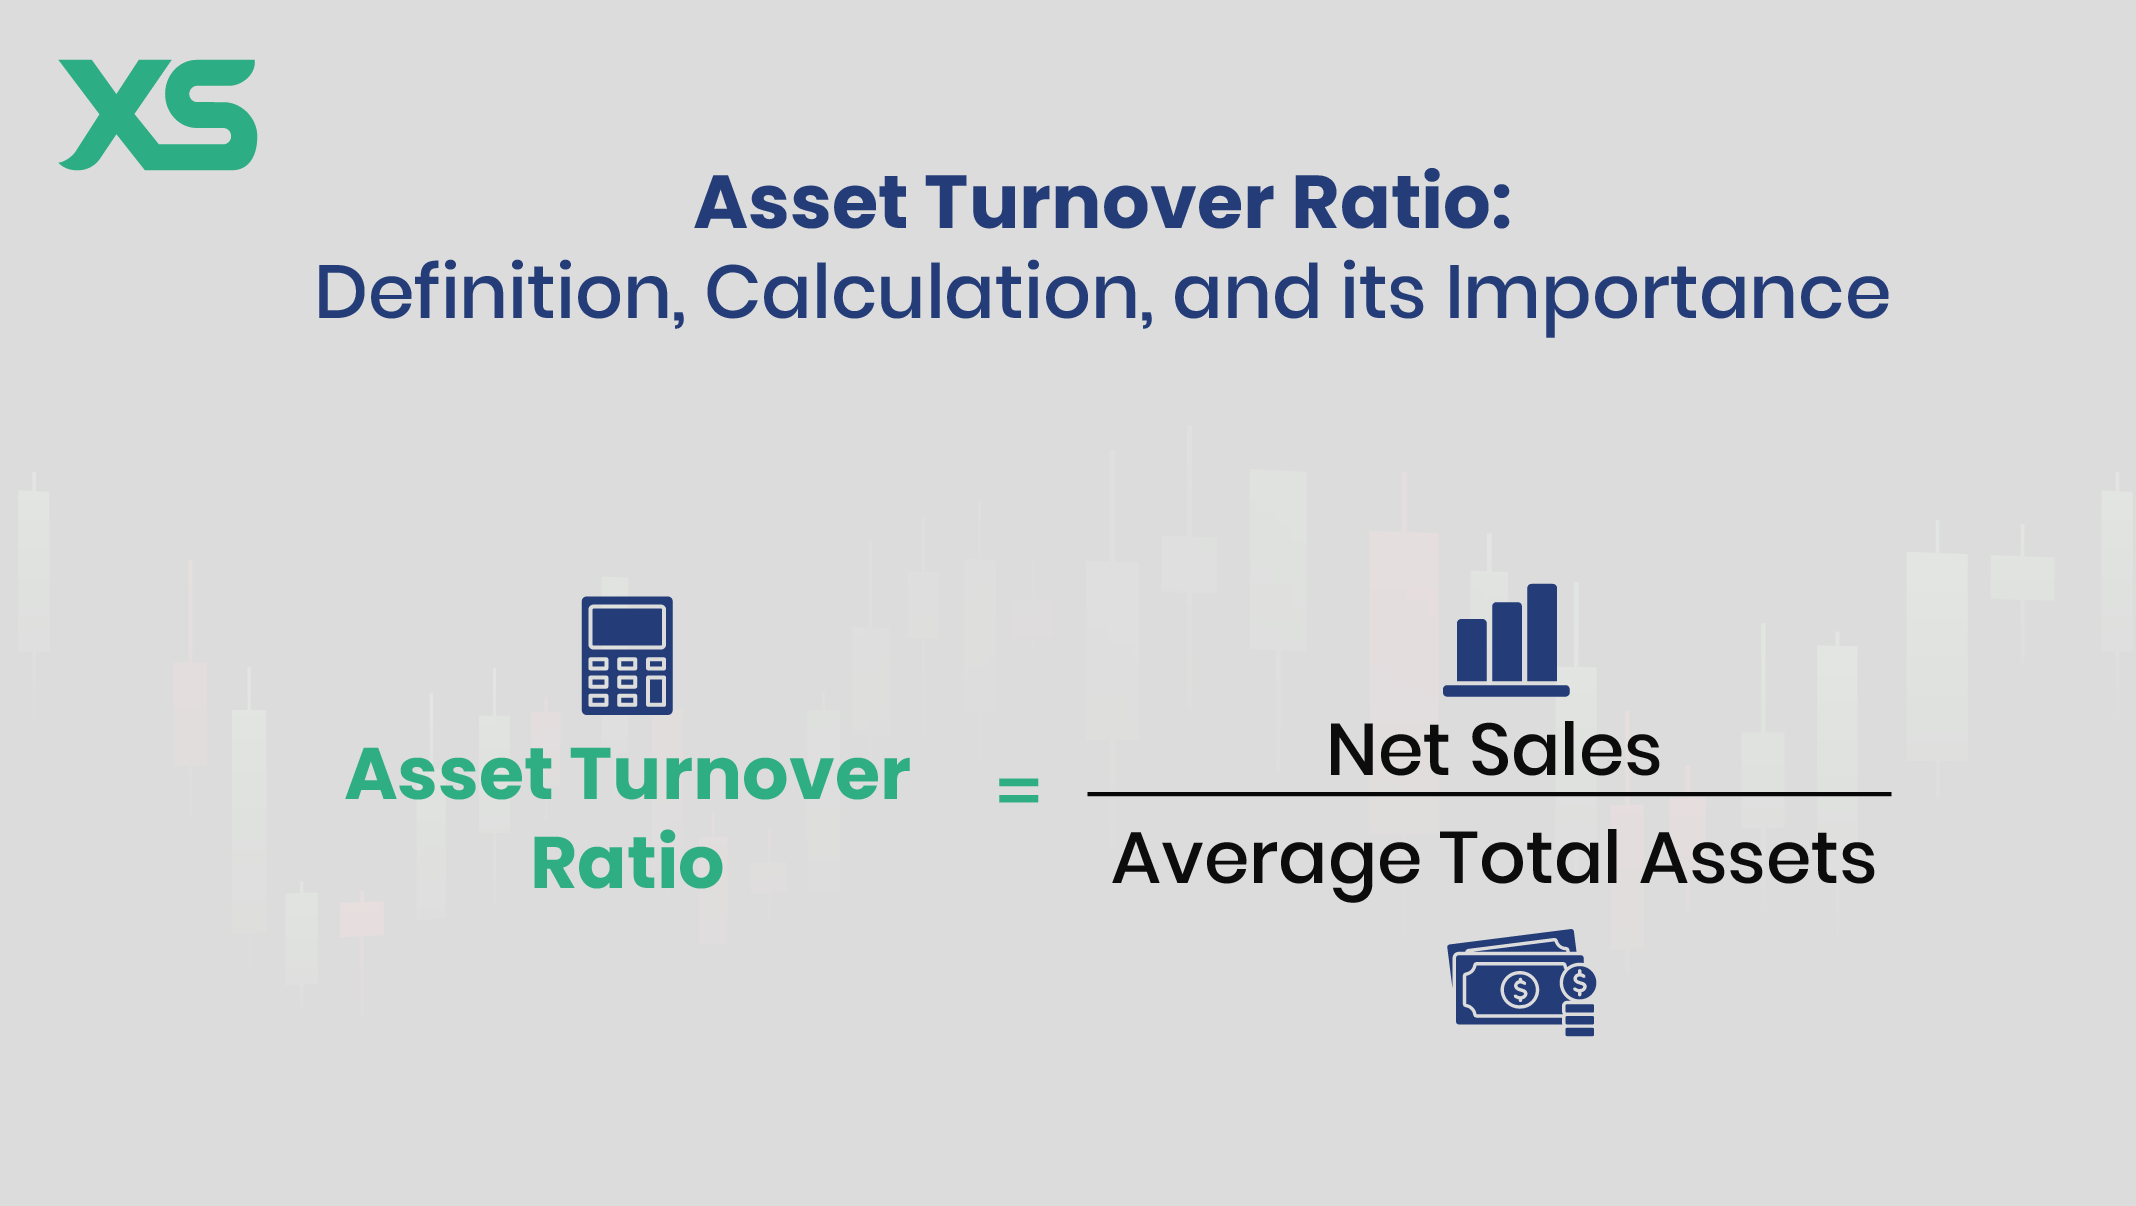
The asset turnover ratio measures how efficiently a company generates revenue from its asset base. It is calculated by dividing total net sales by average total assets over a period. A ratio of 1.2 means the company generated 12 cents of revenue for every dollar of assets. This is a plain operational metric, nothing mystical about it. Most analysts look at this number in isolation, which is a mistake. The ratio means completely different things in manufacturing versus software. A heavy-asset manufacturer running at 0.6 turnover might be perfectly healthy. A light-asset distributor at the same 0.6 is likely sitting on excess inventory or slow-moving receivables. Context is everything here.
Unlock The Secrets Of Ratio Asset Turnover A Key To Unlocking Business Success
There is no single secret to unlock, but there are practical patterns that separate companies which use this ratio well from those that ignore it. I spent three years working through inventory and fixed-asset management for a mid-market industrial supplier. Our gross margin looked fine on paper, but our asset turnover had been drifting below 0.8 for two consecutive years. Revenue was growing at 15 percent annually, yet cash flow kept shrinking. The disconnect should have been obvious. The problem turned out to be a combination of three things. We were carrying six months of slow-moving spare parts in warehouse stock that never turned. Our accounts receivable days had crept from 42 to 67 because we were extending credit to customers who were themselves cash-strapped. And we had bought a second distribution center that sat at 60 percent utilization for the first 18 months. Each of these buried capital without generating proportional revenue. When I restructured the inventory by liquidating dead stock and tightening credit terms to a 45-day maximum for new customers, turnover jumped from 0.72 to 1.14 within eight months. Revenue stayed flat. The improvement came purely from releasing trapped capital. This is the part most tutorials skip. Asset turnover is not a leading indicator. It tells you what already happened. If you are trying to predict future performance from a single quarter's ratio, you are using the wrong tool. The ratio works best as a trailing diagnostic when combined with days sales outstanding, inventory turns, and fixed-asset utilization tracked over at least four quarters.
How to Calculate It Without Making Common Errors
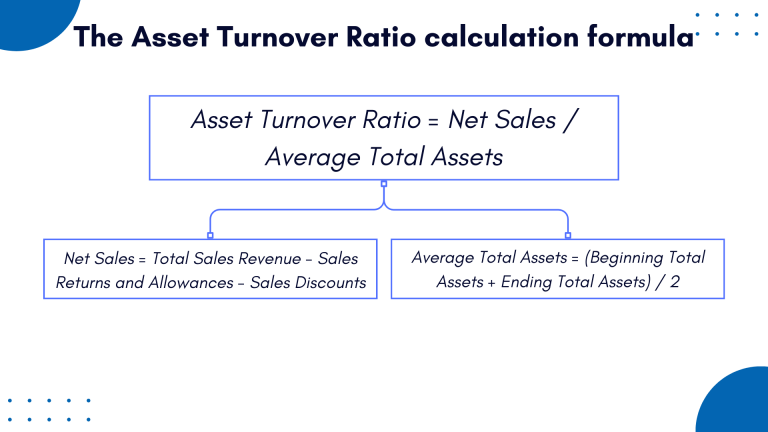
The formula is straightforward, but the inputs matter more than the math. Use average total assets, not ending total assets. Year-end asset balances can be artificially low if a company paid down debt or sold equipment right before the reporting period. Average total assets smooths that distortion. Take the opening and closing balances, divide by two, and use that figure as the denominator. Net sales go in the numerator, not gross revenue. Deduct returns, allowances, and discounts. If your accounting system reports gross revenue by default, subtract the contra-revenue accounts before calculating. A 5 percent difference in the numerator changes the ratio enough to flip a borderline classification in tight credit covenants. Use trailing twelve-month sales with trailing twelve-month average assets. Mixing a full-year revenue figure with quarterly average assets introduces a period mismatch that skews the result. The standard approach uses consistent time windows. If your fiscal year ends in March, use April through March for both the revenue and the asset averages.
Get the Full Details
Industry Benchmarks That Actually Matter
Retail typically runs between 1.5 and 3.0. Grocery chains like Walmart sit around 2.5. Luxury retailers can drop below 1.0 because they carry high-value inventory that turns slowly. A luxury handbag retailer at 0.8 might be more profitable per unit than a volume grocer at 2.5. Margin and turnover trade off against each other. This is the fundamental tension in asset management. Manufacturing usually falls between 0.5 and 1.5. Heavy equipment makers like Caterpillar run near 0.6. Software companies without physical inventory can exceed 5.0, but comparing a SaaS firm to a steel producer using the same benchmark is meaningless. The ratio measures operational efficiency within an asset class, not across asset classes. Services and consulting firms often report ratios above 3.0 because their primary assets are human capital, which does not appear on the balance sheet. This makes the ratio look fantastic, but it also makes it useless for cross-company comparison. If a company has minimal fixed assets and minimal working capital, the denominator is small and the ratio inflates. Do not treat a ratio of 8.0 as a competitive advantage. It probably means the company is asset-light by design, not by superior management.
When the Ratio Lies to You
Lease accounting changes under ASC 842 and IFRS 16 added operating lease right-of-use assets to the balance sheet. Companies that previously kept leases off-balance-sheet now show larger asset bases, which mechanically lowers the turnover ratio. A company at 1.8 before the standard took effect might drop to 1.2 after adoption, even though nothing changed operationally. Compare pre-2019 and post-2019 ratios for the same company with caution. The apparent decline is mostly accounting, not deterioration. Seasonal businesses distort the average asset calculation if you only pull two quarter-end balances. A landscaping company might hold minimal equipment in January and maximal inventory in April. Using just January and April balances gives a different average than using all twelve month-ends. For seasonal operations, use monthly or at least quarterly averages. The improvement in accuracy is usually 0.1 to 0.3 in the final ratio, which is material when you are benchmarking against peers. Acquisitions and divestitures create the biggest distortion. If a company acquired a competitor in July and the target's assets were recorded at fair value, the denominator jumps mid-year without proportional revenue contribution. The ratio drops artificially for that year. Track the ratio on a normalized basis that strips out acquisition-related asset additions for at least the first two quarters post-close. This is standard practice in equity research, but most public filings do not disclose the normalized figure. You have to calculate it yourself from the notes to the financial statements.
What to Do When the Ratio Declines
A declining asset turnover ratio usually signals one of three problems. Revenue is falling faster than assets are being retired. Assets are being added faster than revenue grows. Or both are happening simultaneously, which is the worst case. The first step is to decompose the change into its revenue and asset components. Pull the year-over-year percentage change in net sales and the year-over-year percentage change in total assets. If revenue grew 5 percent and assets grew 20 percent, the ratio must decline. The problem is asset bloat, not revenue collapse. Inventory is the most common culprit in working capital-heavy businesses. If your current asset composition shows inventory growing at twice the rate of sales, you are overstocking. Track gross profit by product line and inventory turnover by SKU category. A 5 percent cut in slow-moving inventory typically releases 2 to 8 percent of working capital in the first quarter, depending on how far gone the overstock is. The exact release varies by industry, but the direction is always the same. Fixed assets are harder to dispose of quickly. Heavy machinery, warehouse buildings, and specialized equipment do not sell at book value in a distressed market. If your fixed-asset turnover is below 0.4 and trending down, evaluate whether the capacity addition was justified. A second distribution center that sits at 60 percent utilization for 18 months will drag the ratio down by 0.15 to 0.25 points. The decision to lease instead of buy, or to sublet unused space, usually recovers 0.05 to 0.10 points within two quarters.

Combining Turnover with Margin Gives the Full Picture
Asset turnover alone is incomplete. DuPont analysis combines margin and turnover into return on assets, which is a more useful performance metric. ROA equals net profit margin multiplied by asset turnover. A company with 8 percent margin and 1.0 turnover generates 8 percent ROA. A company with 4 percent margin and 2.0 turnover also generates 8 percent ROA. The capital efficiency is identical. The operational strategy is completely different. The high-margin-low-turnover model requires different management discipline than the low-margin-high-turnover model. A luxury goods maker at 8 percent margin and 0.5 turnover needs to protect brand perception and control production volumes. A volume retailer at 3 percent margin and 2.5 turnover needs to optimize supply chain speed and minimize stockouts. Both can achieve the same ROA. Neither should copy the other's playbook. If your ROA is below your weighted average cost of capital, you are destroying value regardless of whether the ratio looks healthy. A 6 percent ROA with an 8 percent cost of capital means the business is running inefficiently, not that the turnover ratio is bad. The turnaround focus should be on improving the underlying margin or accelerating asset velocity, not on optimizing a single ratio in isolation. This is the distinction that separates strategic asset management from spreadsheet gymnastics.
Most practitioners track this metric quarterly, but the signal is clearer when viewed annually. Quarterly ratios are noisy because of seasonal inventory builds, interim capital expenditures, and accrual adjustments that reverse in the next quarter. An annual trend over three to five years filters out the noise and reveals the actual operational trajectory. The extra effort to compile annual figures is about 2 to 4 hours per year for a small finance team, which is negligible compared to the decision quality improvement.