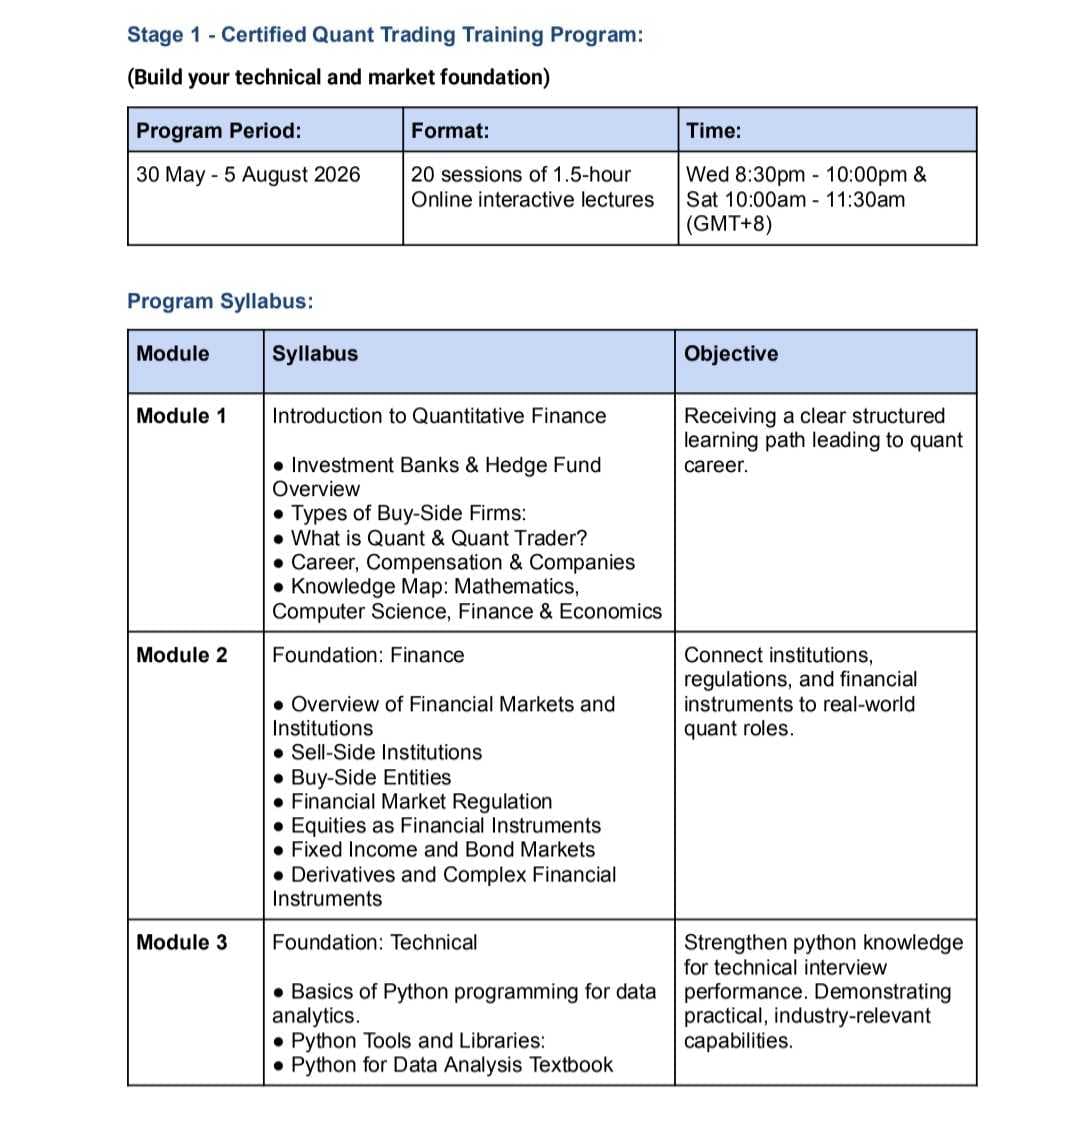
What You Actually Need To Get Into Quant Trading
Most people trying to break into quantitative trading have no idea what the actual path looks like until they've already spent two years on the wrong one. I spent five years recruiting at a mid-tier fund before moving over to the desk side, and the pattern never changes. Candidates obsess over the wrong prerequisites while missing the things that actually get interviews. The degree question comes up constantly, so let me clear it up directly. A PhD in physics or mathematics is the standard baseline for research-oriented quant roles. Not because you need the credential itself, but because three years of independent research under a harsh advisor filters for people who can survive continuous intellectual rejection. That's the real signal. A master's in financial engineering from a program like Baruch, CMU, or Princeton counts if it's from the right school. A bachelor's alone will mostly close doors unless your undergraduate institution is tier one and your math coursework is extensive. I had a candidate once with a perfect track record - MIT math undergrad, published in stochastic analysis, strong C++ skills. We passed him through technical screening without issue. Then during the live coding round he couldn't handle a timed implementation of a Kalman filter from scratch. He understood the theory backwards and forwards but had never coded a recursive estimator under pressure. We sent him home. Theory and implementation are two completely different skill sets in this industry.
The degree requirements aren't as rigid as they appear on job postings though. I've hired people with degrees in computational linguistics, electrical engineering, and even philosophy who had strong programming portfolios and solid probability fundamentals. What matters is whether you can derive and implement pricing models without referring to notes, not what your diploma says.
What The Work Actually Looks Like
Before you invest time preparing for this career, understand that quant trading is largely unglamorous debugging work with occasional bursts of high-intensity problem solving. Most of your day is spent understanding why a model that looked correct on paper produces garbage in production. You'll spend hours tracing a single decimal drift caused by floating point ordering differences between your research environment and the execution stack. Alpha decay is the real constraint nobody talks about. A strategy that works today may stop working in eighteen months because other firms have discovered the same signal. Your job isn't just finding edges. It's finding edges faster than everyone else, implementing them cleanly, and then moving on before the signal deteriorates to noise. This means constant learning is mandatory, not optional. If you're not comfortable spending 30 percent of your week reading papers outside your current focus area, this career will plateau quickly. Compensation varies wildly between buy side and sell side roles. Buy side quant researchers at top funds can expect total compensation in the six-figure range at junior level, climbing to seven figures within five to seven years at peak performers. Sell side quant developers at banks tend to have lower upside but more stable compensation structures. The gap between top and bottom performers in buy side is enormous - we're talking a 50x difference at the senior level between someone who generates consistent alpha and someone who mainly maintains legacy code.
Get the Full Details

Skills That Actually Move The Needle
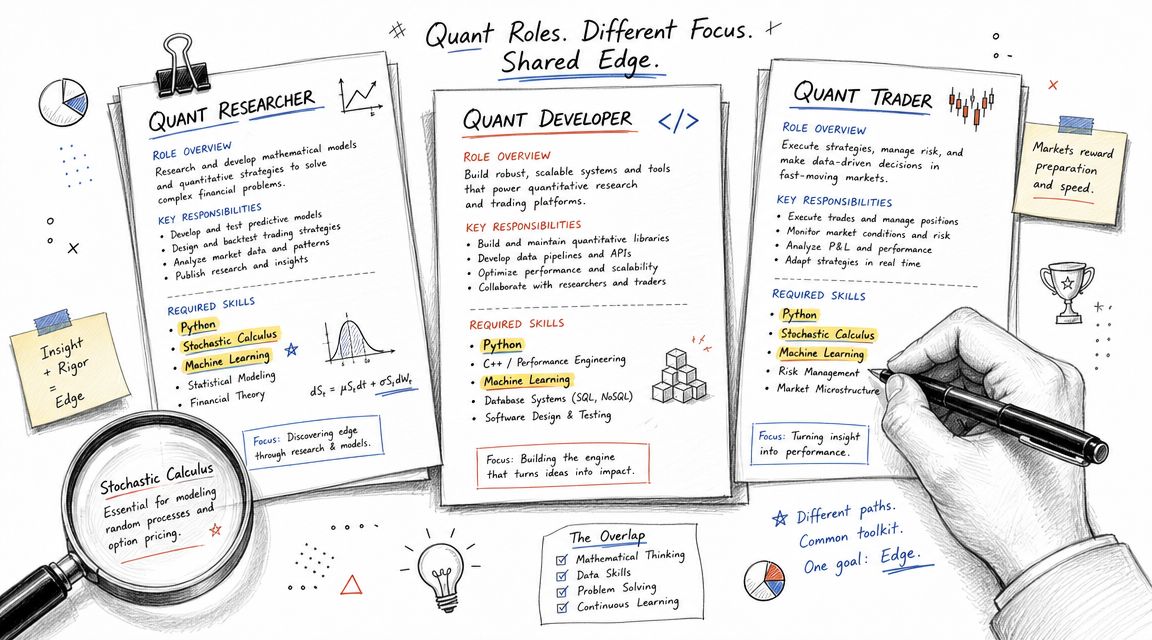
Stochastic calculus, partial differential equations, and time series analysis form the theoretical foundation. You need to be able to derive the Black-Scholes formula from first principles and explain where each assumption breaks down in real markets. If you can only recite the formula without understanding the boundary conditions, you won't last past the first year. Programming ability matters more than most candidates realize. C++ remains dominant in low latency environments while Python dominates research and prototyping. The firms that pay best expect fluency in both. You should be comfortable writing concurrent code, understanding memory management at a low level, and optimizing numerical code for vectorization. A lot of candidates talk a good game on their resumes and then can't write a lock-free queue or explain the cache implications of their data structure choices. Probability and statistics are non-negotiable. Bayesian inference, Markov chains, Monte Carlo methods, and hypothesis testing come up daily. I once worked with a quant who couldn't correctly calculate the posterior probability in a straightforward Bayes theorem problem during an interview. She had a PhD but clearly hadn't done the problem set work. It was the fastest rejection I've seen.
Common Pitfalls
The biggest mistake candidates make is optimizing their preparation for the wrong interview format. Some firms focus heavily on brainteasers and probability puzzles. Others care almost entirely about live coding and system design. Spending months grinding LeetCode hard problems is useless if the firm you're targeting evaluates you on stochastic process derivations instead. Research each firm's interview style specifically rather than treating all quant interviews as the same category. Another pitfall is treating academic knowledge as directly transferable. Real market data is messy, sparse, and non-stationary. A backtest on clean historical data often gives wildly optimistic results because it ignores slippage, liquidity constraints, and survivorship bias. I've seen candidates present backtests with Sharpe ratios above 2.0 that collapsed to below 0.5 once transaction costs and realistic execution assumptions were applied. Learning to build honest backtests early saves you from building strategies that look brilliant in simulation and fail in production. The work can also be isolating. Unlike many finance roles, quant teams are often small and deeply technical. Social interaction with non-technical colleagues is limited, and the intellectual stimulation comes primarily from your own work rather than client-facing interactions. If you expect a collaborative marketing-style environment, you'll be disappointed. The culture is closer to a research lab than a trading floor.
How To Actually Prepare
Start with a solid foundation in real analysis and linear algebra. These underpin everything else. Then move to stochastic processes and numerical methods. For programming, build a project that actually does something useful - a simple options pricer, a backtesting framework, or a market data simulator. Having working code to show is worth more than any certificate. Read the actual papers. Not blog summaries of papers. The original literature on things like Heston models, local volatility, and modern market microstructure theory. Many candidates have only encountered these concepts through secondhand explanations that omit the important details. When you read the original work, you'll notice assumptions and limitations that summaries routinely leave out. Networking in this field works differently than in most finance sectors. Cold outreach to practitioners on LinkedIn tends to get ignored. Engaging with the actual research community through conferences, arXiv discussions, and specialized forums produces better results. I found several of my best hires through people who had been visibly contributing to open source numerical libraries or publishing clear technical explanations online. That kind of demonstrated competence speaks louder than any cover letter.

The field changes fast. Machine learning has reshaped large parts of quant research over the past decade, but it hasn't replaced the core mathematics. The firms that survive are the ones combining deep statistical rigor with modern computational tools. Pure ML approaches without proper risk management frameworks have gotten some funds in trouble when tail events hit. A gradient boosting model trained on noisy financial data will overfit reliably if you let it. The discipline to regularize aggressively and validate out of sample is what separates professionals from hobbyists.