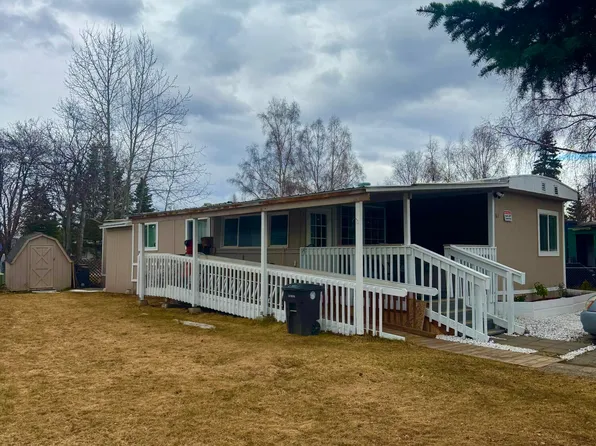
What You Actually Need To Know Before Buying A Mobile Home In Anchorage
The Anchorage market for manufactured housing isn't simple. Prices range from about $40,000 for a 1990s two-wide sitting on a lot you rent to over $300,000 for a newer model in a decent park with land owned outright. Most listings online still treat mobile homes like stick-built houses, and that causes problems. The paperwork, financing, zoning, and park rules are completely different. You have to approach this differently than a site-built home purchase or you'll walk into issues that eat up your budget before you move in. There isn't one single guide that covers everything accurately. What exists out there is usually written by people who sold one unit three years ago and never looked back. The reality is more complicated. I spent roughly two years helping friends and clients navigate this market before I stopped giving free advice and started doing it professionally. Here's what I actually learned doing the work. Anchorage has roughly 18,000 manufactured homes per the latest census data, and the majority sit on rented land in mobile home parks. Only about 35 to 40 percent of those homes are on owned lots. That distinction changes everything about how you buy and finance.
Park-owned units typically list between $45,000 and $95,000 for anything built after 2000. Older units from the late 80s and early 90s can drop into the $25,000 to $40,000 range if they need work. Single-wide homes in poor condition sometimes appear under $20,000 but those numbers almost always hide something. Double- wide or triple-wide homes command more, especially if they have been updated. You'll see well-maintained 1990s dual-sections in parks like Lake Shore or Knik River area moving around $75,000 to $130,000 depending on condition and lot rent.
How Financing Actually Works For Manufactured Homes
This is where most people get confused. If the home sits on land you own and the land is improved with a permanent foundation, you can usually get a conventional mortgage through Fannie Mae or Freddie Mac guidelines. That gives you 30-year fixed rates similar to site-built homes. If the home is on rented land in a park, you're looking at an FHA Title I loan or a personal property loan. Those rates are typically 2 to 4 percentage points higher than conventional mortgage rates, and the terms run shorter, usually 15 to 20 years max. I've seen borrowers get caught off guard by this. They find a great home for $55,000, assume they can throw a conventional loan at it, and then hit a wall because the lot is leased. Always check whether you're buying the home only, the home plus land, or taking over a lease in an existing park before you talk to a lender. Manufactured homes in Alaska go through a separate titling system managed by the Division of Motor Vehicles. The title might be marked as real property if it's been converted, or as personal property if it hasn't. This matters for taxes, insurance, and resale. I had a buyer last year who thought he was purchasing a home with clear title. The seller had never filed the conversion paperwork after anchoring the home to a permanent foundation. The DMV title remained in the seller's name. We spent six weeks and about $800 in legal fees sorting that out. The workaround is straightforward: before you sign anything, pull the current title status through the Alaska DMV using the serial number on the data plate. It takes ten minutes and prevents half the problems I see. There's also the HUD certification label to check. Every manufactured home built after June 1976 should have a red metal seal on the exterior and a data plate inside. The label tells you when and where the home was built and confirms it meets federal construction standards. If a home is missing the label or the label shows a pre-1976 build date, you're dealing with a older trailerpark-style home that carries different risks. Insurance becomes harder to place and financing gets worse. Most banks won't touch a pre-HUD home without significant documentation.
Get the Full Details

Inspecting These Homes Differently
Standard home inspections don't cover enough for manufactured housing. You need someone who knows skirting, undercarriage supports, axle assemblies, and vapor barriers. The most common failure point I see is the underbelly system. Moisture gets trapped between the skirting and the home, rotting the floor frame from underneath. This is invisible during a normal walk-through. I once found a dual-section home with $18,000 in floor joist repairs that a general inspector missed entirely because he never looked under the skirting. The fix is to hire an inspector who specifically mentions manufactured homes in their description, or better yet, someone familiar with Alaskan conditions where freeze-thaw cycles damage piers and supports faster than in warmer climates. Roof condition is another area where manufactured homes differ. These homes were designed with lower pitch roofs than site-built houses. Ice damming is a real issue here in Anchorage. I've seen roofs on 1998 single-wides that looked fine from the ground but had softened decking from repeated ice backup behind clogged gutters. Check the ceiling corners inside for water stains. Those tell you more about roof health than any exterior photo.
Park Rules Can Make Or Break Your Purchase
Many buyers don't realize they're also signing up for a landlord relationship when they buy into a mobile home park. Park rules govern everything from parking vehicles to allowing rental units to pet policies. Some parks have age restrictions. Some prohibit homes older than a certain year. A few require you to use their approved vendor for any modifications. Before you commit, request the full park rules and lease agreement. Read them. I had a client who bought a home in a popular Southside park and discovered too late that the park prohibited any subletting, which defeated his plan to rent out a second unit for extra income. He was stuck with a home he couldn't monetize the way he'd expected.
Where To Actually Find Listings
Zillow and Realtor.com carry some manufactured home listings but they are incomplete. A lot of sellers in this space use local methods. The Alaska Classifieds section on KXLY and other local outlets still works. Facebook Marketplace has become a major channel, especially for private sales. The Anchorage MLS does include manufactured homes but the filters are not always reliable. You'll see site-built homes mixed in and some manufactured homes omitted entirely. The most practical approach is to set up alerts on the MLS for manufactured housing, check Facebook Marketplace daily with location filtering, and drive the established parks in areas like Lake Shore, Knik River, and Mulcahy. Many owners post yard signs that never make it online.

The Numbers That Matter Beyond The Listing Price
Your total cost includes more than the sticker price. Property taxes in Anchorage are assessed differently for manufactured homes depending on whether the title is real or personal property. Real property titles get assessed like land and improvements and you pay standard municipal taxes. Personal property titles are assessed as vehicle property, which can be significantly cheaper but creates a different set of complications when you try to sell. Park rent, usually between $400 and $900 per month for a pad, is a permanent ongoing expense. Insurance for a manufactured home in Anchorage typically runs $800 to $1,500 annually depending on age and coverage. Utility costs can be higher than site-built homes because of the way these structures Insulate, especially older units with single-pane windows and thin wall construction. I always advise budgeting at least $150 to $300 more per month for heating compared to a similarly sized stick-built home.
A Practical Checklist Before You Sign
Verify the title status through DMV. Confirm the HUD label is present and legible. Review the park rules and current lease if applicable. Get a manufactured-home-specific inspection. Pull your financing pre-approval with the correct loan type for the property. Request a recent property tax statement. Check for any outstanding utility liens. I keep a simple spreadsheet with these items and mark each one off during the process. It took me three purchases to realize how easy it is to skip steps when you're excited about a home. The checklist prevents that.
When You Should Walk Away
Some homes are not worth the hassle. If the undercarriage shows extensive rot, if the title has a brand like salvage or reconstructed and you can't verify the repairs, if the park is facing a sale or conversion to condos, or if the home was built before 1976 without proper documentation, move on. I've turned away more deals than I've accepted simply because the foundation conditions were beyond reasonable repair. A $30,000 home with $40,000 in foundation and skirting work is not a deal. It's a problem with a price tag. The market has plenty of reasonably priced homes that are structurally sound. They just require patience to find.