What the Nikkei 225 Actually Measures
The Nikkei 225 is a price-weighted index of 225 blue-chip companies listed on the Tokyo Stock Exchange. It was launched by the Nihon Keizai Shinbun newspaper in 1950. People outside Japan often treat it as the definitive gauge of Japanese equity performance, but it works differently than the S&P 500 or FTSE 100 you might be used to. Price weighting means higher-priced stocks dominate the movement. A single ¥50,000 share moving 1% affects the index far more than a ¥100 share moving 10%. This creates some counter-intuitive behavior that catches people off guard when they first study it. You will see low-priced stocks bounce around wildly while the index barely budges because the heavy hitters aren't moving much.
Unlock The Secrets Of Japans Top Index Everything About Nikkei 225
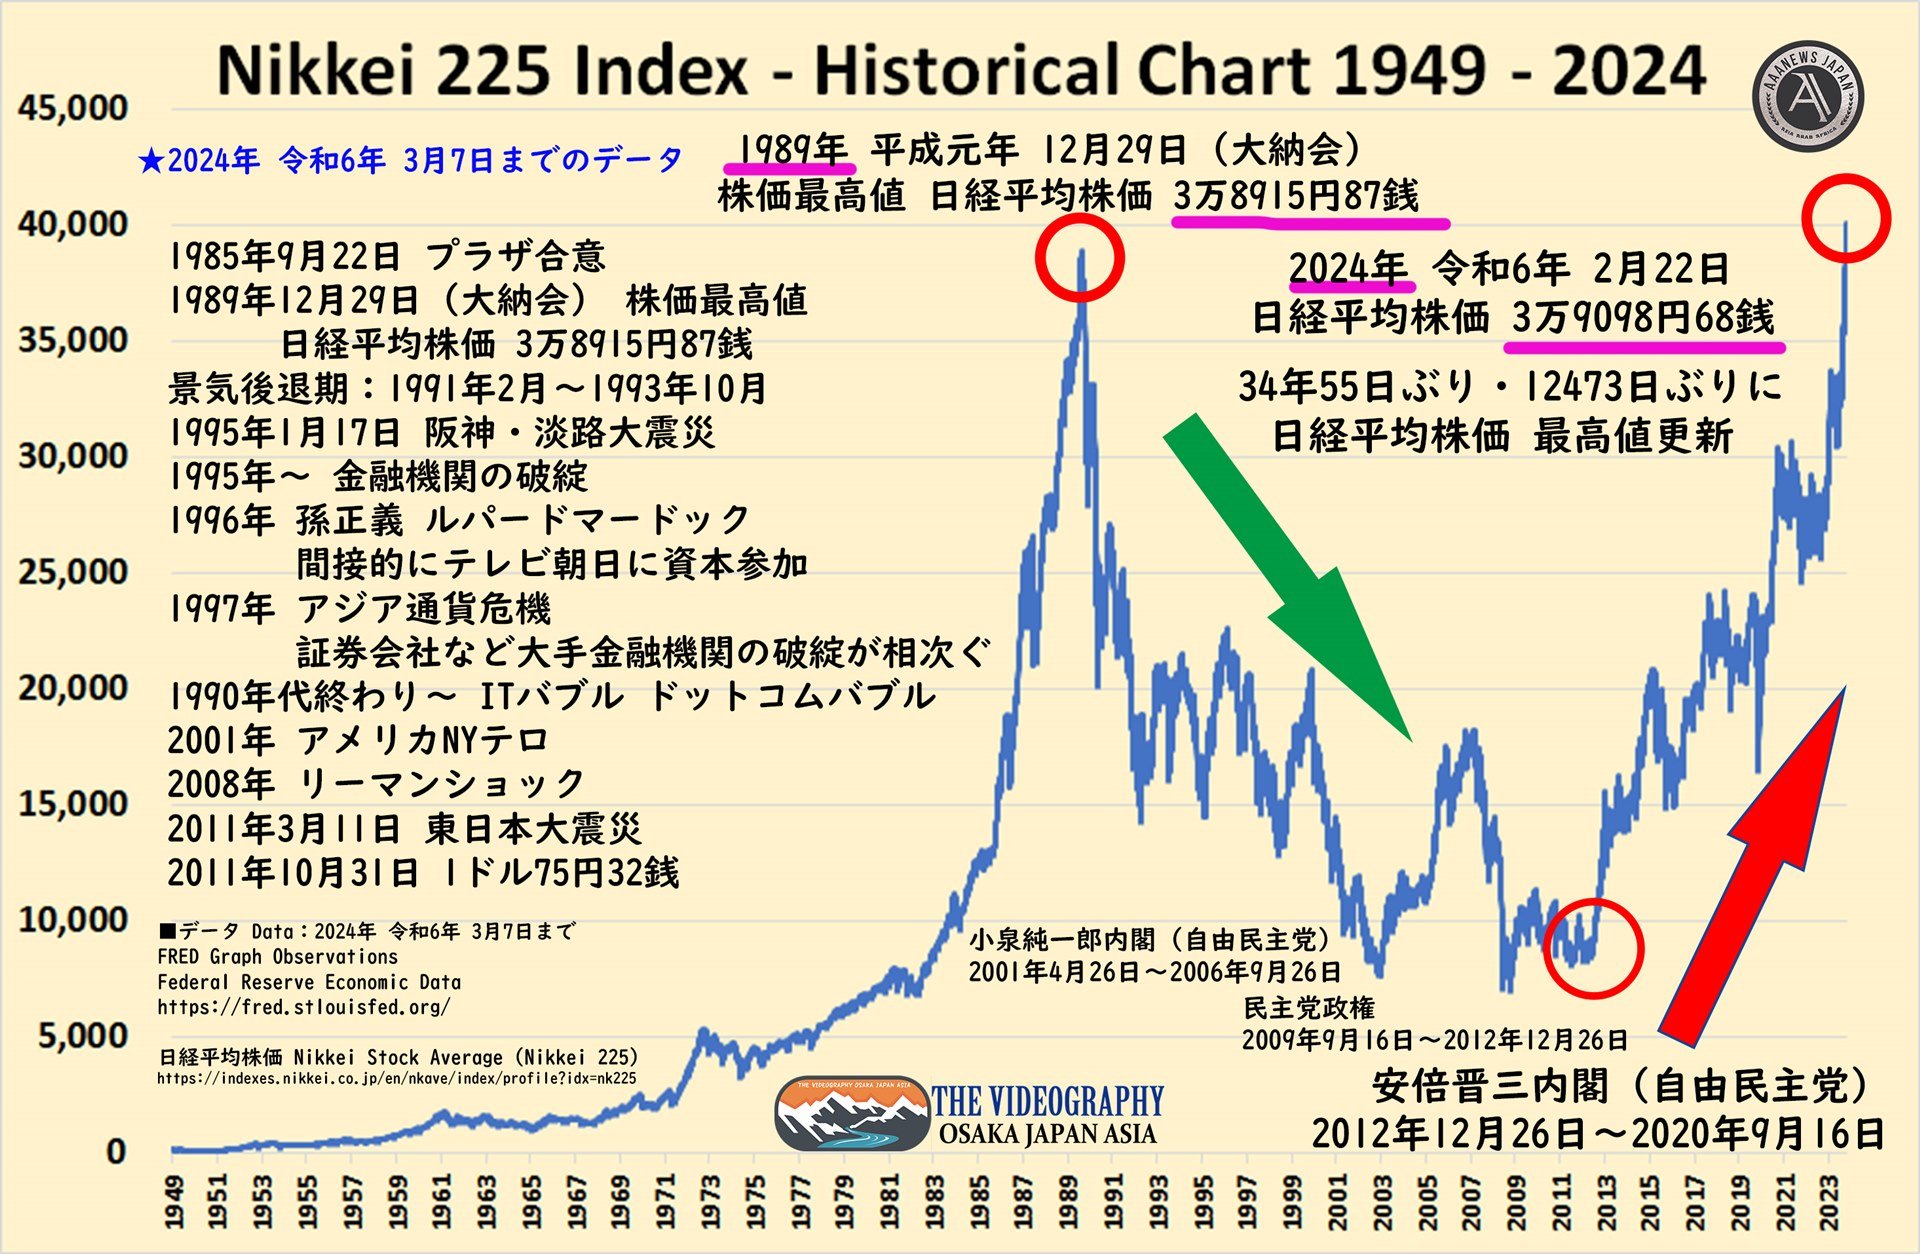
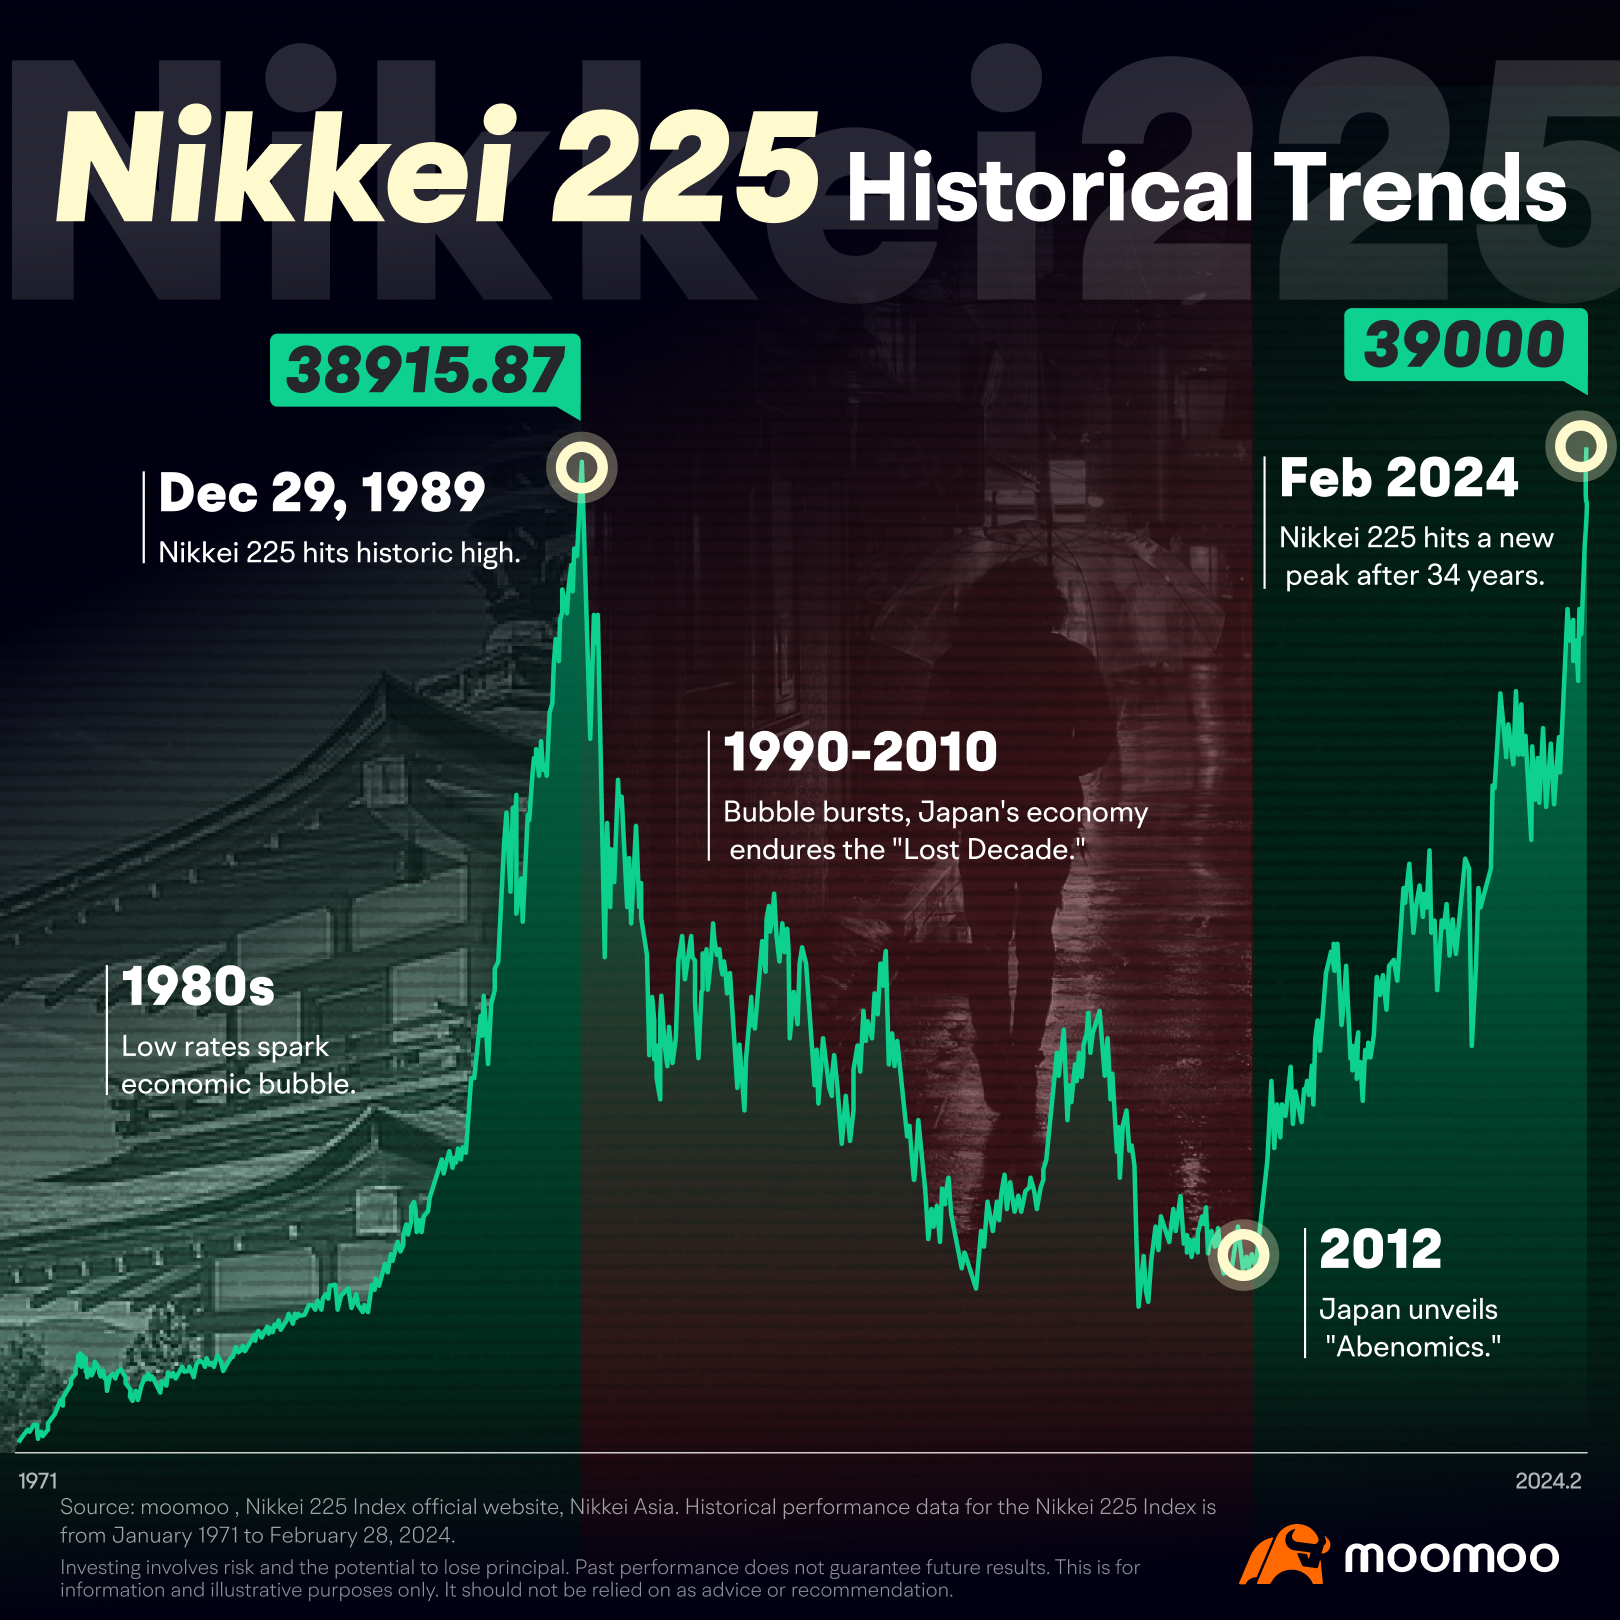
I have tracked this index for about twelve years across multiple market cycles. The first thing you need to understand is that the Nikkei 225 does not represent the broader Japanese economy the way people assume. It covers large-cap exporters heavily. Companies like Toyota, Sony, and Keyence make up a disproportionate share of the movement. When the yen weakens, the index tends to rise because those companies report better earnings in dollar terms. When the yen strengthens, the index falls even if corporate profits are fine. The weighting quirk creates a specific problem I ran into back in 2021. I was rebalancing a portfolio that included Nikkei futures and noticed the index jump nearly 400 points on a day when most of the component stocks actually closed flat. It turned out Takara Holding, which trades at a very high nominal share price, moved just two yen higher. That single yen shift accounted for almost the entire index gain. I had to adjust my hedge ratios because my model was assuming dollar-weighted behavior. The fix was to recalculate exposure using the actual price weights rather than market cap weights. It took about twenty minutes once I realized what was happening, but I had already taken a small loss on the mismatch.
How to Trade or Track the Index Practically
You can access the Nikkei 225 through several routes. Futures contracts trade on the Osaka Exchange under the code NK. The options market on those futures is quite liquid during Asian hours. Spot ETFs like the InvESCO Nikkei 225 ETF (308523) track the index but include currency exposure unless you use a hedged version. Direct index replication is impossible for most retail investors because of lot size requirements on the individual components. The trading hours are another detail beginners miss. The TSE main session runs from 9:00 to 11:30 and 12:30 to 15:00 Japan time. But the Nikkei is calculated throughout the day based on real-time prices. After-hours movement in US-listed Japanese ADRs or movements in related markets like the Hang Seng can create gaps at the open. I usually check closing prices in Shanghai and Hong Kong before deciding whether to adjust my Tokyo position the night before. If you want historical data, the quickest route is the Yahoo Finance API or the Tokyo Stock Exchange data portal. The Nikkei official website provides end-of-day snapshots but does not give intraday granularity without a paid feed. For backtesting purposes, I use daily close data and accept that intraday volatility gets smoothed out. This limitation matters less for long-term strategies but becomes a problem if you are testing mean-reversion approaches on short timeframes.
Get the Full Details
Common Mistakes When Analyzing the Index
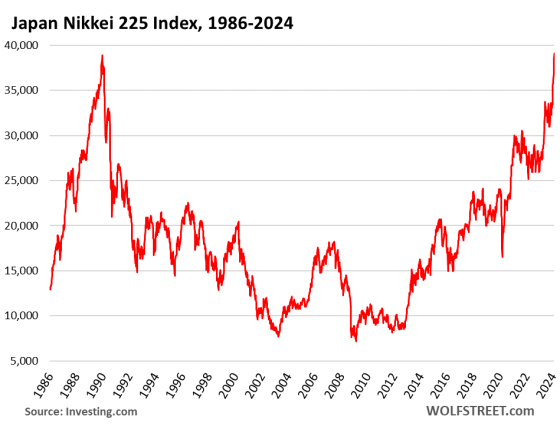
People routinely confuse Nikkei performance with yen performance. Those are different drivers. The index can fall while the yen strengthens, or rise while the yen weakens, depending on which effect dominates. I saw both happen in the same calendar year during 2022, which confused a lot of analysts at the time. Another issue is assuming the Nikkei reflects the whole of Japan. Small and mid-caps get ignored entirely. The TOPIX index covers roughly two thousand stocks and is market-cap weighted. If you want a broader view of Japanese equity performance, TOPIX is more representative. The Nikkei is useful for tracking large-cap sentiment and export-oriented corporate health, but it misses domestic consumption and regional banking, which matter during certain economic cycles. Rebalancing timing also trips people up. The index review happens every March, but constituent changes do not always announce far enough in advance for passive funds to adjust without tracking error. I worked with a client in 2019 who got caught on the wrong side of a component addition because the announcement came just three days before the effective date. The stock spiked on inclusion news and then dropped sharply as the index fund bought into the rally. That kind of event is hard to predict consistently.
When the Nikkei 225 Fails as a Benchmark
The index breaks down as a benchmark during periods of extreme yen volatility. Between 2020 and 2024, there were stretches where the currency swung enough to make the index meaningless as a standalone measure of Japanese economic health. If your strategy depends on the index reflecting domestic conditions, you will get false signals during those windows. The price-weighting distortion worsens during market stress. High-priced stocks tend to be the ones with the most institutional ownership and the least retail participation. When panic selling hits, those stocks often hold up better than lower-priced speculative names, which means the Nikkei can look deceptively stable during crashes that are actually brutal for small-cap investors. The 2008 financial crisis showed this clearly. The index fell about 55 percent from peak to trough, but the underlying selling pressure on smaller constituents was far worse than the headline number suggested. If you need a cleaner benchmark for diversified Japanese equity exposure, consider combining the Nikkei 225 with the TOPIX and the JPX-Nikkei 400. That composite approach smooths out the idiosyncrasies of price weighting and gives you better coverage of the actual investment universe. It adds about ten minutes of monthly reconciliation work but pays for itself in reduced tracking error.
Practical Data Sources and Tools
For free daily data, Bloomberg and Reuters terminals are overkill. I use a combination of the Yahoo Finance endpoint and a simple Python script that pulls the Nikkei close plus the USD/JPY rate each evening. The correlation between the two series over rolling twelve-month windows tells me whether currency risk is driving the returns or corporate fundamentals are. During normal periods that correlation sits around 0.3 to 0.5. During stressed periods it spikes above 0.7, which is when the index stops being useful as a pure equity signal. Real-time quotes require a broker account with JPMill or DAIWA direct access. Retail platforms like Interactive Brokers provide delayed data unless you pay for the data feed, which runs roughly fifty dollars per month for Level 2 quotes on the TOPIX. That cost is worth it only if you are actively trading the index futures or constructing a synthetic replication portfolio. For academic or institutional work, the Nikkei Historical Data Service provides adjusted closes going back to 1896. The adjustment factor accounts for dividend reinvestment and price-weight recalibrations after stock splits. This dataset is essential if you are building long-run models because unadjusted prices create artificial jumps whenever the weighting method changes. Those changes happen every few years and can distort any backtest that spans a methodology switch.

What I Wish I Had Known Earlier
The Nikkei 225 is not broken. It is just narrowly focused. It serves a specific purpose: tracking large-cap exporters and giving a quick pulse on Japanese market sentiment. If you treat it as the complete picture of Japanese equities, you will miss material risk. The index ignores the domestic side of the economy, overweights a handful of mega-caps, and distorts volatility through its weighting scheme. Learning to read the index alongside the yen and alongside TOPIX changed how I approach Japanese equity exposure. Instead of betting directionally on the Nikkei alone, I now build positions based on the differential between the two indices and the expected yen move over the holding period. That framework is more work upfront, but it reduces the chance of being surprised by a currency-driven gap that has nothing to do with corporate performance.