The Practical Side Of Tracking Dividend Streaks
Most people look at a list of dividend stocks and focus on the yield number. That is a mistake that cost me money early on. A high yield combined with a short streak usually means the company is paying out of debt or depleting its cash reserves. The market calls this a yield trap. I learned that the hard way when I bought a utility stock because it offered 8.4% yield and had a streak listed as 40 years. The board cut the dividend three months later. The streak reset to zero overnight. I held it for another six months waiting for a recovery that never came. The core skill here is not finding stocks with long streaks. It is understanding which streaks are sustainable and which are just accounting artifacts or lucky timing. You need to look at the payment history itself, the financial fundamentals behind each payment, and the business cycle the company operates in.Unlock The Secrets Of Dividend Payment Streak What Investors Need To Know
A dividend payment streak is the number of consecutive years a company has increased or at least maintained its dividend. The most recognized version is the Dividend Aristocrats, which requires 25 consecutive years of increases. Then there are the Kings, companies with 50+ years. But these labels miss something important. A company can maintain a $1.00 per share dividend for 20 years and qualify as a streak keeper even if the real value of that payment has been eroded by 40% in purchasing power. Maintenance is not the same thing as growth. The more useful metric is how many years of actual dividend growth a company has achieved, combined with whether the payout ratio leaves room for continuation during a downturn. I use a spreadsheet that tracks four data points for every dividend stock I hold or watch: the number of years of consecutive increases, the current payout ratio based on free cash flow rather than earnings per share, the revenue growth over the past five years, and the debt to equity ratio. I update this quarterly. The payout ratio based on free cash flow is critical because earnings can be manipulated through accounting adjustments. Free cash flow is harder to fake. If a company reports a 90% earnings payout ratio but a 140% free cash flow payout ratio, the dividend is already running ahead of the actual cash the business generates. That is a red flag regardless of how many years the streak claims to have.
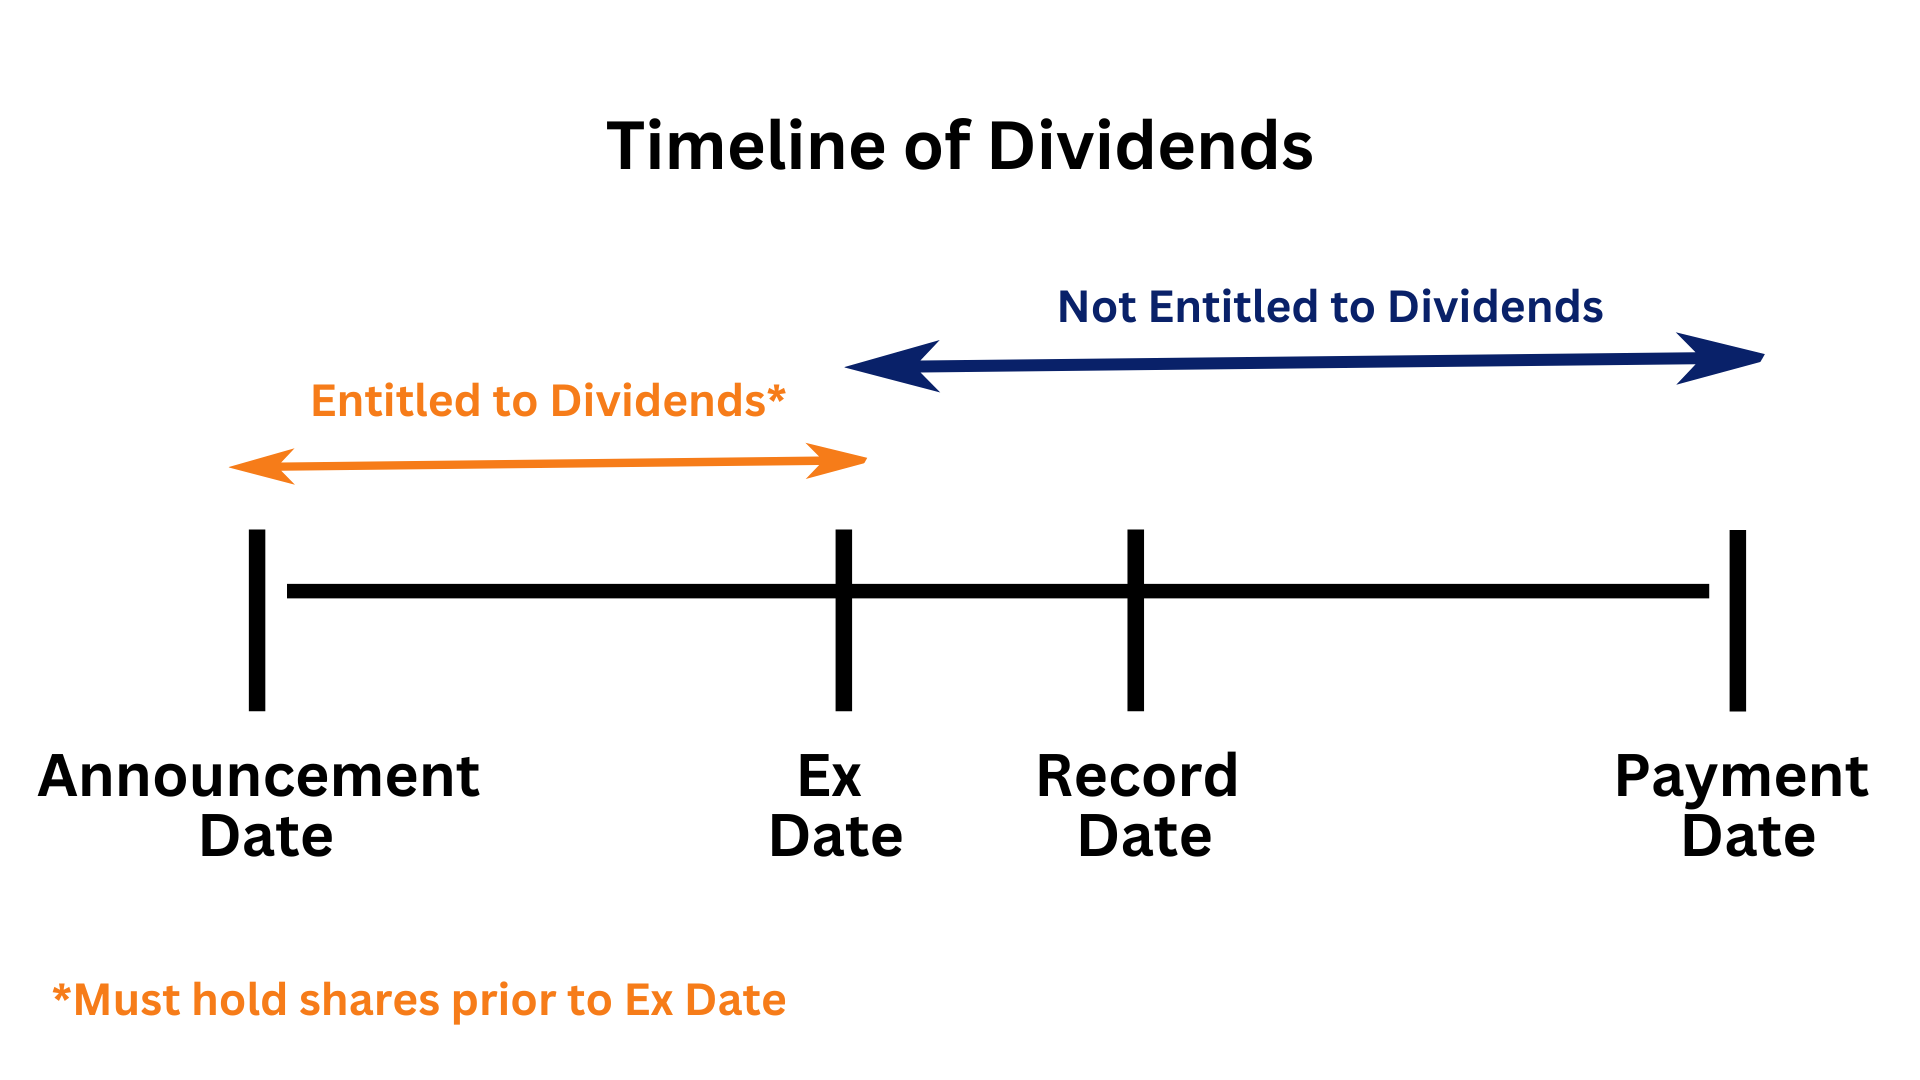
Here is the part most guides skip. The payment date itself matters more than people realize. When a company announces a dividend increase, there is typically a record date and a payment date about a month apart. The stock price usually adjusts downward by roughly the dividend amount on the ex-dividend date. If you buy the stock just before the ex-dividend date to capture the payment, you are not gaining anything free. You are simply shifting money from the stock price into your pocket. The real question is whether the company's earnings trajectory justifies the higher dividend going forward. I ran into a specific problem last year that exposed a flaw in how streak data is commonly displayed. I was reviewing a consumer staples company that claimed a 62-year dividend streak. The numbers looked fine on the surface. Payout ratio around 55%, steady revenue, solid balance sheet. But when I dug into the payment history, I noticed the company had only raised the dividend three times in the previous decade. The streak counted years of maintenance, not years of growth. The S&P Dividend Aristocrat index methodology accepts this because their rule is about not cutting the dividend, not about increasing it annually. This distinction matters enormously if your goal is income growth rather than just income stability. The workaround I developed was to cross-reference the streak claim with the actual dividend per share progression over the previous ten years. If the payment had only increased two or three times in a decade despite a 60-year streak claim, I treated the company as a stable dividend payer rather than a dividend growth stock. That classification changed my entire approach to the position. Stable dividend payers belong in the income portion of a portfolio where yield matters. Dividend growth stocks belong in the accumulation phase where reinvestment drives compounding. Mixing those two strategies causes confusion and poor timing decisions. There are several tools you can use to build this analysis yourself. Most major financial data platforms offer dividend history screens. Yahoo Finance provides free dividend history for individual stocks. The Dividend.com website tracks streaks across thousands of companies with filters for years of growth and payout ratios. For more granular data, the Morningstar dividend sustainability report covers the broader health of a company's payment policy. I also check the company's investor relations page directly, where the quarterly earnings releases include management commentary on dividend policy that sometimes reveals intentions not captured in the raw numbers. The fundamental issue with relying on streak length as a primary filter is that old companies tend to accumulate long streaks by default. They survived multiple recessions, but that does not mean their current dividend policy is optimal for today's environment. A company that started raising dividends in the 1970s may have been operating in a completely different tax and regulatory landscape. Their current business model might be declining while they prop up the dividend with buybacks or debt. I found this with a packaging company that had a 45-year streak. Their core business was shrinking because e-commerce was replacing their primary product line. The dividend increase was funded entirely by borrowing. The streak was real, but the foundation was rotting. The counter-intuitive insight is that sometimes a shorter streak on a younger company is safer than a long streak on an old one. A company that has been raising dividends for eight years with a payout ratio of 35% and accelerating revenue may be in a much stronger position than a 50-year streak company with a 75% payout ratio and flat to declining revenue. The shorter-streak company has more headroom. It can sustain increases through a recession without touching its balance sheet. The longer-streak company may be one bad year away from a cut, which would reset its streak and likely trigger a sharp price decline. You should also pay attention to the frequency and timing of payments. Most U.S. dividend stocks pay quarterly. Some pay monthly, like certain REITs and BDCs. Monthly payers can appear to have smoother income streams, but they often carry higher risk profiles. REITs and BDCs are required by law to distribute most of their taxable income, which means their payout ratios look different from regular corporations. A REIT reporting a 90% payout ratio is normal and not necessarily a warning sign. A regular corporation at 90% is already in dangerous territory. If you want a practical system, start by screening for companies with at least ten consecutive years of dividend increases. Filter for a free cash flow payout ratio below 60%. Exclude any company where revenue has declined for three straight years. Then manually review the payment history of the remaining candidates to distinguish between actual growth streaks and maintenance streaks. This process takes about 45 minutes for a portfolio of 20 to 30 holdings. The result is significantly more reliable than whatever ranking you will find on a generic dividend screener website. The biggest limitation of this entire approach is that past streaks predict nothing about future cuts. The 2008 financial crisis eliminated dividend streaks across financial stocks almost overnight. Companies that had paid dividends for decades cut them simultaneously. The streak data you see in historical tables is backward-looking. It tells you what happened, not what will happen next. The only forward-looking signals are the payout ratio, the debt profile, and the industry dynamics. If all three look healthy, the streak is more likely to continue. If any one of them is deteriorating, the streak length becomes irrelevant. I also recommend tracking the company's share buyback activity alongside dividend payments. When a company is buying back shares while maintaining or growing its dividend, it is often a sign that management is confident about future cash flows. When a company is buying back shares while the dividend payout ratio is climbing toward 70%, it may be using buybacks to offset the dilution from equity compensation while quietly preparing for a dividend pause. The combination of rising payout ratio and aggressive buybacks is a specific pattern I watch closely. It shows up in several companies before a dividend cut occurs.