So you want to squeeze value out of the Torrid rewards card
I've been working with retail credit programs for long enough that I can spot a bad deal from a mile away, and the Comenity-branded Torrid card is one of those things people either love or completely misunderstand. It's a store card, which means it's designed to keep you shopping at one place. The rewards structure looks decent on paper, but the real value comes down to timing, spending habits, and knowing the hidden mechanics most customers never bother to read. The Torrid rewards card is issued through Comenity Bank, which handles a large chunk of the retail credit card market. It operates primarily as a points-based rewards card where you earn 5% back on qualifying Torrid purchases. Points accrue in your rewards account and can be redeemed for future purchases. The card also typically offers promotional deals like 20% off your first purchase or double-point events during holiday seasons. These promotions aren't permanent fixtures though. They rotate, and if you miss them, you're leaving money on the table. Here's the thing about store cards that nobody mentions: they usually have a higher APR than general-purpose cards. The Torrid card carries a variable rate that can land somewhere between 25% and 30%. That means if you carry a balance, the rewards you earn get completely eaten by interest charges within a few billing cycles. I learned this the hard way after a customer of mine kept her card open for the 5% rewards but carried a $400 balance across multiple months. She earned roughly $30 in rewards over a year and paid about $110 in interest. The math is brutal when you stop to calculate it.
The rewards system uses points rather than straight cash back, which adds a layer of complexity. Points don't always have a 1-to-1 dollar value. During standard redemption, each point might be worth somewhere around one cent, but during special redemption windows, the value can shift. Comenity occasionally runs promo events where you get bonus points or reduced point thresholds for certain reward tiers. Tracking these events requires setting a calendar reminder or checking your account monthly. Without that discipline, you'll likely redeem at the worst possible time. One specific edge case I ran into involved a customer who returned a substantial portion of a big purchase. She had earned a significant amount of rewards points on that transaction, and when she processed the return, the system clawed back all the points associated with the returned items. But here's the problem: she'd already redeemed some of those points for a discount on a separate order. The account went negative on points, and she had to wait until her next qualifying purchase to get back into positive standing. This happens more often than the help desk admits. Always check your rewards balance before processing returns, and never redeem points that were earned on purchases you're thinking of returning. The welcome bonus is another area where people make mistakes. Depending on the current promotion, signing up might include a bonus like 10% or 20% off your first purchase. These offers usually require you to make a qualifying purchase within a certain timeframe, often 60 to 90 days from account opening. If you sign up and then forget to use the card for anything, the bonus expires. I've seen customers do this repeatedly. Make sure you know the expiration window and either plan your next Torrid shopping trip around it or don't bother opening the account.
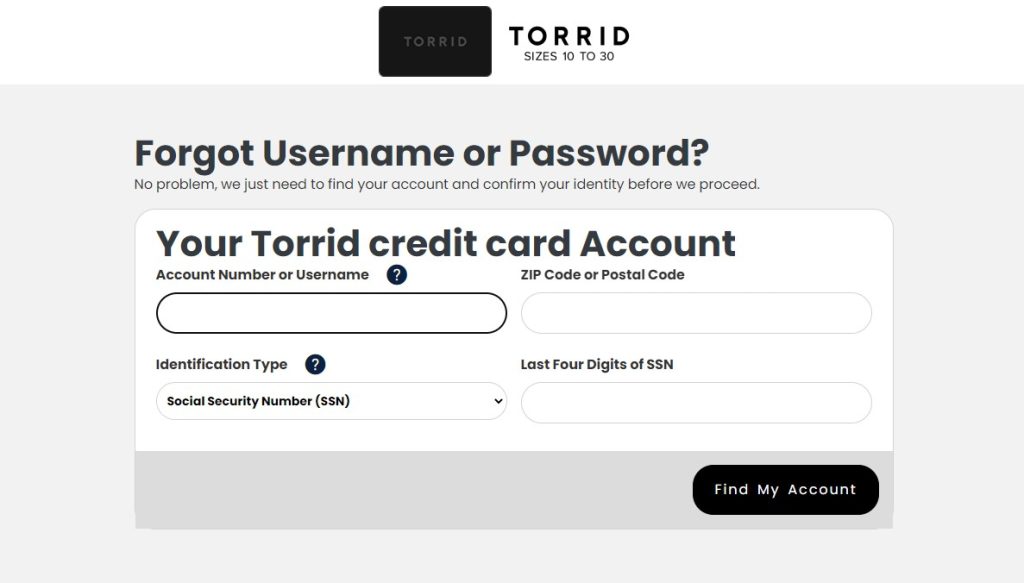
Another detail most people overlook is the tier structure. Comenity rewards accounts sometimes operate on tiered systems where your earning rate improves as you spend more throughout the year. There might be base-level earning, mid-tier, and top-tier brackets. The exact thresholds vary by promotion and change over time. If you know your typical annual spending at Torrid, you can plan larger purchases around times when tier benefits are most valuable. Spreading purchases evenly across the year might actually cost you more in missed tier upgrades. There are also birthday rewards and periodic email promotions that stack on top of the standard 5% earning rate. Birthday offers often come with extra point multipliers or a special discount code. You need to make sure your birthday is registered correctly in your account profile. I've encountered cases where the date was entered wrong or set to an old address, and the promotional email never arrived. Call customer service and verify your profile information at least once a year. It takes three minutes and prevents a lot of headaches. Let me address the limitations because this card isn't universally beneficial. If you're someone who shops at Torrid infrequently, maybe once or twice a year, the card's value drops considerably. The annual fees are usually zero, which helps, but the opportunity cost of having another credit account in your wallet isn't nothing. Store cards also tend to impact your credit utilization ratios differently than general-purpose cards because the credit limit is often modest to begin with. A low limit on a new account can temporarily ding your credit score through the hard inquiry and the new account marker. If you're actively shopping for a mortgage or major loan, think twice before applying.
Get the Full Details
The redemption minimum is another bottleneck. You usually need a certain number of points before you can redeem them for a reward certificate. This threshold varies but might sit around 500 to 1,000 points. If you're a casual shopper, it could take six months or more to reach that threshold. Meanwhile, those points are sitting in your account potentially losing value if there's any devaluation schedule in the terms, which Comenity does reserve the right to modify. For maximum value, the optimal strategy is straightforward but requires discipline. Pay your statement balance in full every month without exception. Never carry a balance. Time your purchases around promotional events and double-point weekends. Check your rewards balance after every return to catch any clawbacks immediately. Verify your account profile annually for correct birthday and contact information. Consider whether your shopping frequency justifies having yet another store card open, and if your credit situation is in flux, delay the application until after your major financial events. The card itself is a tool, not a solution. It works well for people who already shop at Torrid regularly and who pay their balances on time. For everyone else, it's just another account tracking an APR that will eventually consume any rewards you earn.