Getting Your Head Around Auto Financing Without Losing Sleep
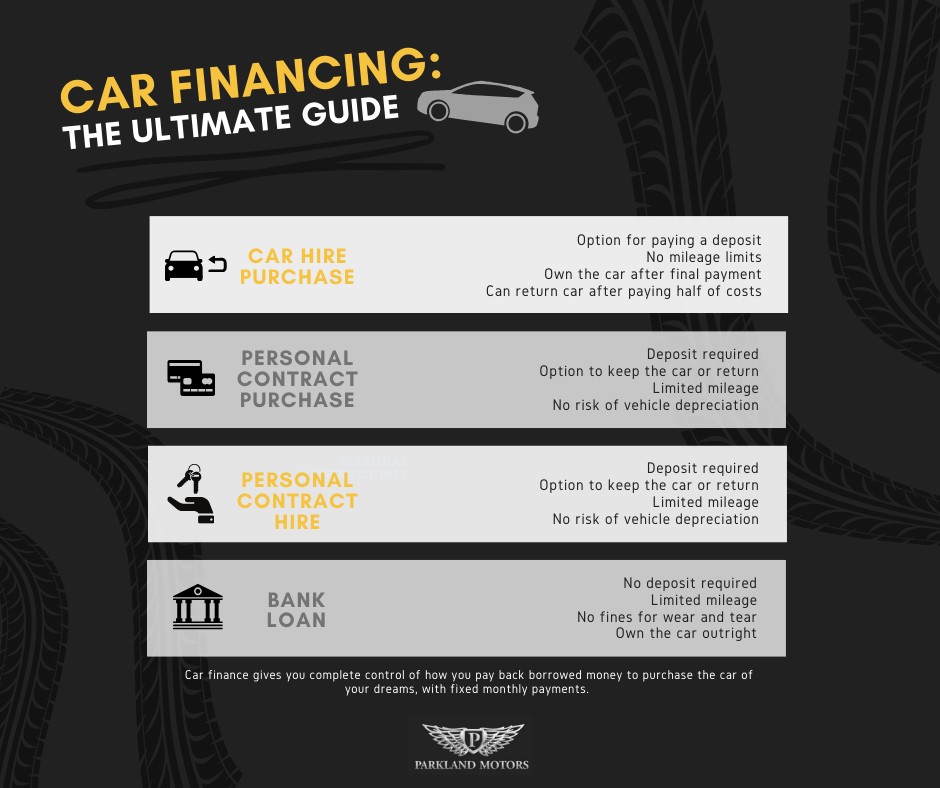
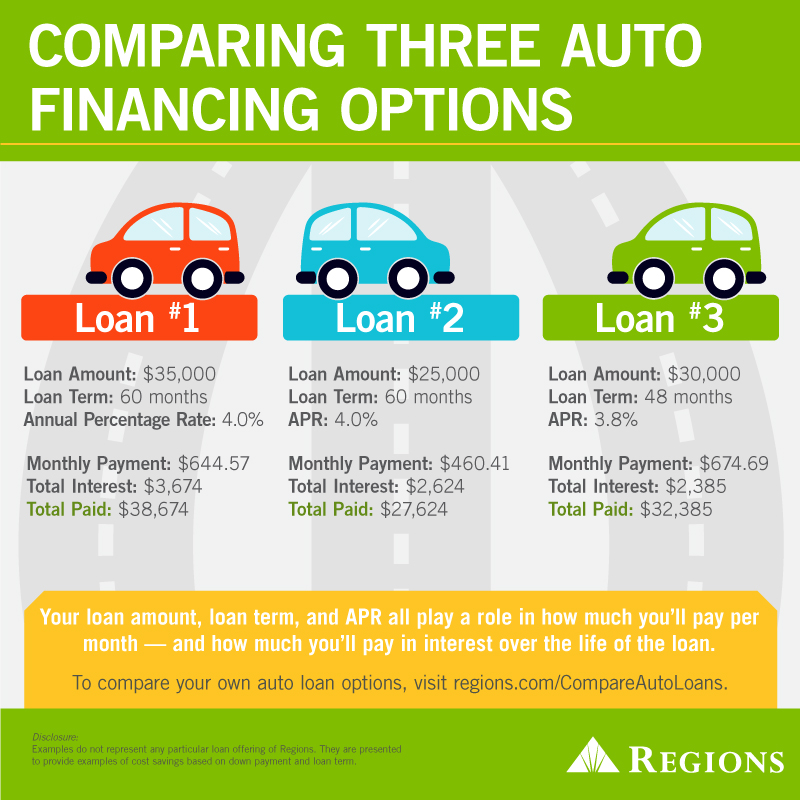
Car financing is one of those things that seems straightforward until you're sitting at a dealership with a salesperson circling numbers on a pad. I've sat through too many of those sessions. The core mechanics are simple enough, but the details trip people up constantly. Entender Auto Finance is essentially a tool for understanding what a car loan actually costs you before you commit. Most people walk into financing blind because they focus on the monthly payment. The monthly payment is the least useful number on the page. It's designed to be the number you fixate on because it sounds manageable. Here's what actually matters: the total cost of ownership including interest, fees, and the loan term. A $400 monthly payment over 72 months costs you roughly $28,800. A $400 monthly payment over 36 months costs you roughly $14,400. Same payment, wildly different financial outcomes. Entender helps you see both sides of that equation before you sign anything.
I learned this the hard way back in 2019 when I financed a used truck through a dealer. The payment looked reasonable at $520 a month. I didn't realize I was locked into a 84-month term with an effective APR that crept up to nearly 9% once all the add-ons folded in. The dealer had stacked GAP insurance, a maintenance plan, and an extended warranty into the principal. That meant I was paying interest on top of interest on products I didn't need. The workaround I ended up using was walking out, going home, and running the numbers myself with a clean spreadsheet. I stripped everything back to just the vehicle price, the actual interest rate the lender offered, and the term. Only then did I realize I was overpaying by roughly $4,200 in finance charges alone compared to what a credit union would have offered on the same vehicle. Going back to the dealer with those numbers changed the conversation entirely. They adjusted the terms because they could tell I wasn't guessing anymore.
How The Process Actually Works In Practice
When you use a financing analyzer like Entender, you input the vehicle price, your down payment, the loan term you're considering, and your estimated interest rate. The tool then breaks down the total cost, monthly payment, and how much of each payment goes toward principal versus interest over the life of the loan. That last part is the one most people skip, and it's the most important part. In the early years of a loan, the vast majority of your payment goes toward interest. On a typical 5-year auto loan at 6.5% APR, roughly 60% of your first payment covers interest. It takes about two years before that ratio flips and principal starts exceeding interest. If you're planning to trade in early or pay off the loan ahead of schedule, this amortization curve matters a lot. You could be months into payments and still owe nearly the full vehicle price. One counter-intuitive thing I've noticed: extending your loan term to lower your monthly payment is almost never financially smart unless you have a compelling reason. A longer term means more total interest paid, often double or triple what you'd pay on a shorter term. The lower payment feels like relief but it's usually an illusion. The money you save each month gets swallowed by accumulated interest over the extra years.
Get the Full Details
Another thing that catches people off guard: your credit score affects more than just your rate. It affects which lenders will touch your application at all. A score in the low 600s might eliminate the best rates from major banks and push you toward subprime lenders charging 12% or higher. Entender lets you model different scenarios so you can see how a 20-point score improvement changes your total cost. Sometimes it's worth taking three months to boost your score before you buy.
Where This Approach Falls Short
Entender and tools like it are only as good as the information you feed them. If you guess at your interest rate, the whole projection is wrong. The only way to get an accurate number is to get pre-approved by a lender before you shop. A pre-approval gives you a real rate, not a guess. Without it, you're working with estimates that can be off by a full percentage point or more. The tool also doesn't account for state and local taxes, registration fees, or title costs unless you manually enter them. Those can add several hundred dollars to your out-the-door price. A $30,000 vehicle in some states lands closer to $33,000 once you factor in everything. Entender won't warn you about that unless you build it in yourself. There's also a limitation with trade-ins. If you're rolling equity from a previous vehicle into a new loan, that changes your effective financing amount. Some analyzers handle this, some don't. You need to know your exact payoff balance on your current loan, not just what you think you owe. People frequently overestimate their trade-in equity because they confuse market value with loan balance.
Practical Steps To Take Before You Finance
Run your numbers independently first. Don't wait for the dealer to present terms. Get a pre-approval from a credit union or online lender. Write down the monthly payment, total interest, and total cost. Compare that against what the dealer offers. If the dealer's numbers are worse, you now have ammunition to negotiate or walk away. Factor in the full cost of ownership. Insurance premiums jump significantly when you add a financed vehicle, especially if it's a newer or more expensive model. Fuel costs, maintenance reserves, and depreciation all matter. A cheap monthly payment on a gas-guzzler with poor reliability ratings can cost you far more over three years than a slightly higher payment on an efficient, dependable vehicle. Watch for add-on products during financing. Dealers make most of their profit on GAP insurance, tire and wheel coverage, paint protection, and extended warranties. None of these are mandatory. Some are outright scams disguised as necessity. A $1,500 extended warranty rolled into your loan costs you roughly $1,800 over five years at a typical interest rate. You can often find the same coverage cheaper on your own or skip it entirely if the vehicle is reliable.
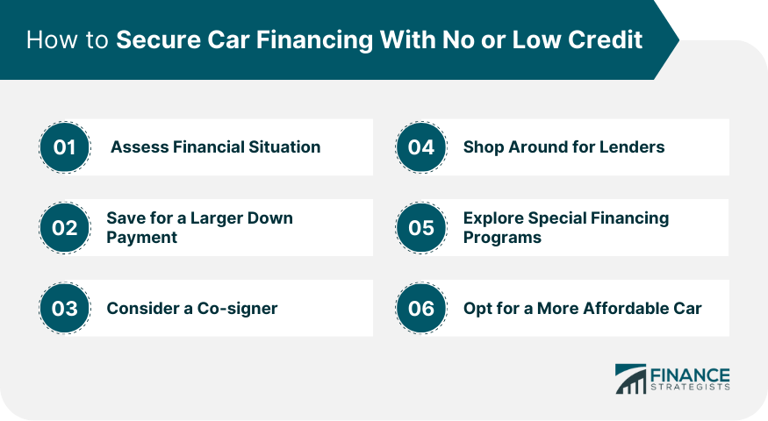
Know when to walk away. If the dealer won't break down the numbers transparently or pushes you toward a longer term than you want, that's a signal. Legitimate lenders and dealers have no problem explaining every line item on your contract. Pressure to decide quickly is never in your favor. The math behind car financing isn't complicated. The complexity comes from people who haven't done the math before they sit down to sign. Doing it yourself first changes everything. You stop reacting to whatever number the salesperson throws at you and start making decisions based on actual cost. That shift alone is worth the fifteen minutes it takes to run the numbers.