What Actually Happens When You Apply for a Bad Credit Truck Loan
Most people hit a wall the moment they tell a lender their credit score is below 600. The answer comes back fast, usually within minutes. Denied. The rate is terrible anyway, often 14% to 18% APR, and the terms lock you into payments that eat most of your monthly profit. I've seen guys try this five or six times across different dealerships and end up with five hard pulls on their report, making things worse before they even got close to a decision. The real problem isn't that approval is impossible. It's that the market for these loans is fragmented and mostly unhelpful. You'll find lenders who advertise bad credit truck loans everywhere online, but most of them are brokers who forward your application to five different wholesale shops and wait to see what sticks. That process alone creates the hard inquiry cascade. A direct lender approach changes the timeline entirely. Some credit unions and regional banks actually have specific programs for used truck financing that don't follow the same scoring rules as big national auto lenders. NCCO and USDA loans exist for agricultural and rural commercial use, and they offer rates in the 5% to 7% range even with subprime credit. The catch is the vehicle has to qualify as commercial equipment, and you need to show business income tied to the truck's use. That changes everything about how the application gets evaluated.
Here is the detail most people miss. Lenders look at debt-to-income ratio harder than the credit score itself for truck loans. If you make $3,200 a month and your existing debts total $900, that's a 28% DTI. Most subprime lenders will still approve you at that level. But if your score is 540 and your DTI is 42%, you are going to get rejected every time, no matter which lender you target. The score opens doors, but the DTI decides if you walk through them. I ran into a specific case last year with a client who had a 562 score, two prior auto loan charge-offs, and needed a 2012 Ford F-250 for his hauling business. The truck was $14,800. Three lenders denied him flat out. The fourth required a 40% down payment, which he didn't have. The workaround was applying through a SBA 7a loan program for small equipment financing instead of a traditional auto loan. He set up an LLC the week before applying, got a DUNS number from Dun & Bradstreet, and pulled six months of bank statements showing consistent revenue from his side contracting work. The SBA-backed lender approved him at 9.2% APR with a 72-month term and only 12% down. The process took 11 days instead of the usual 48 hours, but the rate was half of what he would have gotten from a subprime auto dealer. The SBA route only works if you can document business income. Personal income from W-2 jobs doesn't qualify for the commercial program. You need to show the truck generates revenue. Invoices, delivery records, contractor payments, whatever proves the asset is income-producing. Without that, you are back to the standard subprime market where rates are brutal and approval is uncertain.
Another edge case that trips people up is loan amounts below $5,000. A lot of subprime lenders won't touch anything under that threshold because the processing cost eats their margin. If you need a $4,000 work truck, your options narrow to payday-style auto lenders or private sellers willing to finance directly. Neither is good. A private seller note at 10% interest with a personal guarantee is actually better than a predatory subprime lender at 19%. Take the paperwork seriously either way.
Get the Full Details
How to Actually Get Approved Without Destroying Your Credit
Stop applying to multiple lenders in a short window. The scoring models penalize rapid sequential auto loan applications heavily. You get about two weeks of rate shopping where multiple pulls count as one. After that, each application is a fresh damage event. Space your applications out by at least 30 days between lenders that don't share inquiry data, or better yet, get pre-qualified through soft inquiry channels first and only submit the full application once you have a conditional approval in hand. Shop the dealer floor carefully. Some dealers have relationships with captive finance companies like Ford Credit or GM Financial that have more flexible subprime tiers. A used 2015 or newer truck bought through a dealer with a manufacturer backing program often gets better rates than a direct application to a bank. The dealer marks up the rate, yes, but the starting rate is lower, so your final number might still be competitive. Get the dealer to disclose the buy rate before you sign anything. Ask directly what rate they are getting from the lender and what their markup is. Most will tell you if you press. Consider a co-signer only if you trust that person completely and have a written agreement about responsibility. A co-signer with good credit can drop your rate by 4 to 7 percentage points. But if you miss a payment, it hits their credit report just as hard as yours. I've watched friendships end over exactly this scenario. Get everything in writing before anyone co-signs.
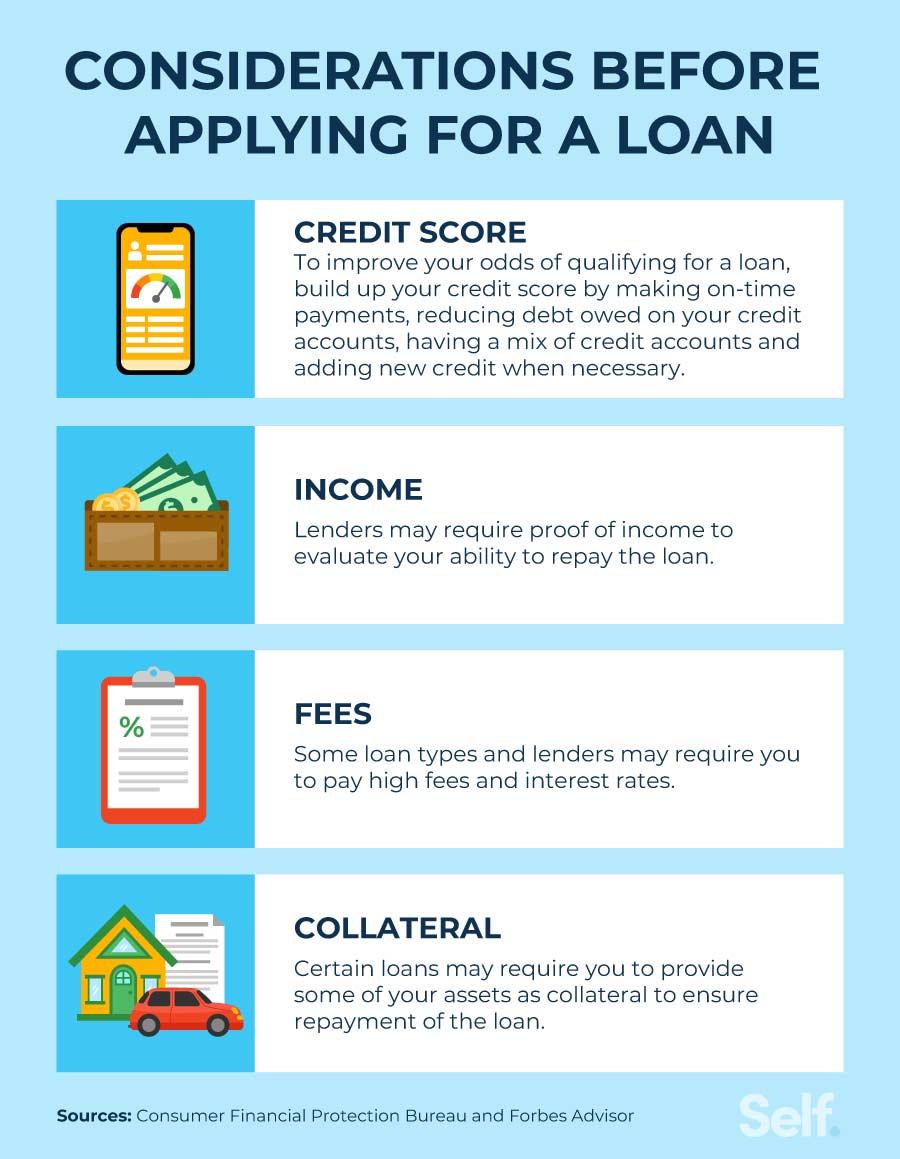
The down payment question matters more than people think. Putting 20% down minimum is the standard requirement for subprime truck loans. Some lenders will accept 10%, but the rate jumps. Twenty percent also reduces the loan balance enough that default risk looks lower on paper. If you can scrape together 20% from savings or a family gift, it changes the approval odds significantly. A gift letter from a family member is usually sufficient documentation for the lender.
The Real Limitations You Should Know About
Bad credit truck loans will never match prime rates. Accept that upfront. Even with the best strategy, you are looking at 8% to 16% APR depending on your score band, loan amount, and whether the truck qualifies as commercial equipment. If your score is below 520, most mainstream lenders will simply not touch the application. At that point, you are in private lending territory with terms that can be predatory. Loan terms are shorter for bad credit applicants. Instead of 72 or 84 months, you might get 48 or 60. That increases your monthly payment substantially. A $18,000 loan at 14% over 60 months costs about $418 per month. The same loan at 14% over 72 months drops to $352. The longer term saves money monthly but costs more in total interest. With subprime rates, the total interest paid can exceed 30% of the loan amount over the life of the loan. Some lenders require gap insurance as a condition of the loan. That adds $800 to $1,200 to the total cost depending on the provider. Factor that in when comparing offers. Other lenders bundle it in, so check the breakdown before signing.
Prepayment penalties exist on some bad credit truck loans, though they are less common now than they were five years ago. Read the fine print. If you get a windfall and want to pay off the loan early, a prepayment penalty could cost you a few months of interest. Look for loans that explicitly state no prepayment penalty. It is negotiable in some cases, especially if you have leverage like a co-signer or a large down payment.
Practical Steps If You Need This Right Now
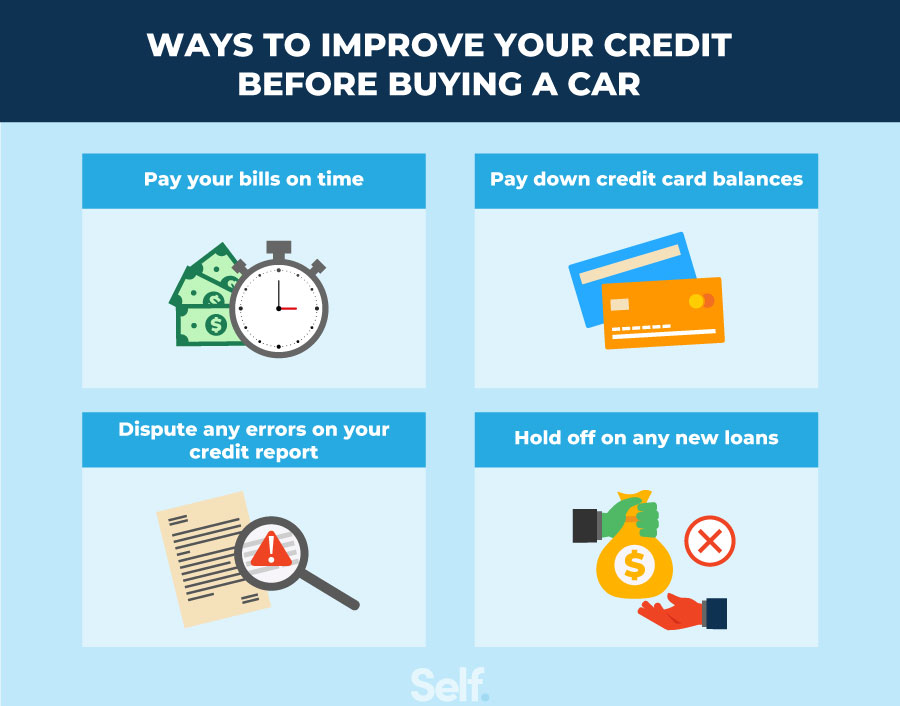
Check your credit report first. Dispute any errors. A single incorrect late payment can drop your score 50 points. Fixing it before applying changes your entire position. This takes about a week if you catch mistakes early. Check annualcreditreport.com for free reports from all three bureaus. Gather documentation before you apply. Pay stubs, bank statements, tax returns if self-employed, proof of residence, and a list of existing debts. Having everything ready cuts the application time from two hours to about 20 minutes per lender. Most rejections happen because the applicant couldn't produce documents quickly enough and lost momentum. Target two or three lenders maximum. Start with a credit union if you qualify for membership. Then try one regional bank with commercial lending experience. Finally, if those fail, go to a specialized bad credit auto lender. Do not submit more than three applications in a 60-day window unless you have a very specific reason.
If you own a business, explore the SBA and commercial equipment loan routes seriously. The extra paperwork is real, maybe three to five days of document gathering, but the rate difference is often worth it. A 9% SBA rate versus a 15% subprime rate on an $18,000 truck loan saves roughly $1,600 over the life of the loan. Used truck values have been inflated since 2021. A 2013 Chevrolet Silverado 2500HD that sold for $16,000 in 2019 is now $20,000 to $24,000 depending on condition. Factor current pricing into your loan amount calculation. Overborrowing to cover a higher purchase price with bad credit is a fast path to negative equity. If the truck is worth less than what you owe, you are stuck paying for a vehicle you cannot sell or trade without adding more cash. There is no magic fix for bad credit truck financing. The best outcome depends on your score band, your ability to document commercial use, and how much time you have to shop compared to how urgently you need the truck. Most people who get a reasonable rate do it by combining a solid down payment, accurate documentation, and targeting the right lender type for their situation. The wrong lender choice at the wrong time is the single biggest mistake I see people make.