What a Land Sales Agreement Actually Is
A land sales agreement is a contract where the seller agrees to transfer ownership of a parcel of real estate to a buyer at a future date, provided certain conditions are met. It is not a deed. It is not a closing document. It is an executory contract that binds both parties until the transaction reaches the point where title actually transfers. Most people confuse it with a purchase agreement, which is a different instrument with different legal consequences depending on your state. The core mechanism is straightforward: the buyer deposits earnest money, the seller carries the title, and the buyer gets equitable interest in the property during the interim period. But the specifics vary significantly by jurisdiction, which is why I stopped trusting generic templates about a decade ago. I switched to drafting or heavily modifying every agreement based on the actual property characteristics and the local recording statutes. The difference in risk exposure between a template-driven deal and a properly tailored agreement is measurable. You can lose a deposit, or worse, the entire property, because a single clause was written for a different state or a different type of parcel.
Unlock The Secret To Stressfree Land Transactions A Comprehensive Guide To Land Sales Agreement
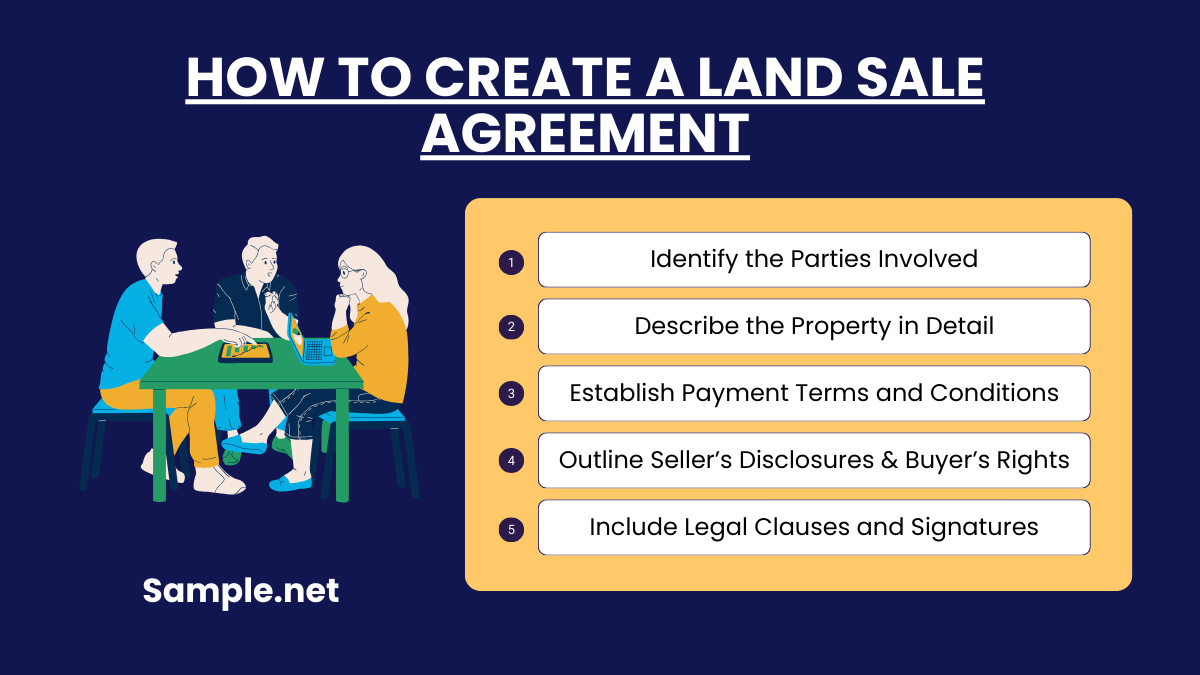
Stress-free land transactions don't come from avoiding complications. They come from catching them before you sign. The majority of deals I see fall apart because the buyer and seller had different assumptions about what the contract actually covered. Here is how I approach it now. Every land sales agreement begins with the legal description, not the street address. A street address is useful for mailing and navigation. It means nothing in a contract. The legal description — lot and block, metes and bounds, or government survey section — is what defines the property boundaries in the eyes of the court. If the legal description is wrong, vague, or copied from an outdated deed, the entire agreement can be unenforceable. I run into this constantly with older rural parcels. A seller will provide a description pulled from a 1978 tax assessment, which may reference a removed monument or a discontinued survey line. In one transaction I handled last year, the legal description in the seller's packet referenced a "" (iron pin) that had been removed during a road widening project ten years prior. The actual current survey had a different boundary monument location. The buyer's attorney caught this during the title review, but only because we included a requirement that the legal description be confirmed against the most recent recorded survey before earnest money became non-refundable. That single clause saved the buyer from locking in a deposit on a property whose boundaries were arguably in dispute.
Step Two: Define the Consideration and Payment Structure Clearly
The purchase price section needs to specify not just the total amount but the payment schedule, the earnest money deposit amount and who holds it, the balance due at closing, and any seller financing terms if applicable. Vague language here creates the most litigation I see in land transactions. If you are doing seller financing, the agreement must include the interest rate, amortization period, balloon payment terms if any, default provisions, and whether the note is secured by a deed of trust or a land contract itself. In some states, a land contract functions as the security instrument. In others, you need a separate deed of trust recorded simultaneously. I once worked a deal where the seller and buyer agreed on oral terms for a $85,000 balance at 6 percent over ten years with a balloon at year five. They put nothing in writing beyond the basic purchase agreement. When the balloon came due and the buyer couldn't refinance, the seller sued for the full balance while the buyer claimed the terms were never finalized. The case settled at considerable expense to both sides, and the property sat in limbo for eighteen months. The lesson: write down every financial term explicitly. Not "to be agreed." Not "as discussed." Every number, every date, every percentage.
Get the Full Details
Step Three: Address Title and Survey Contingencies Properly
Raw land rarely comes with clean title in the way a developed residential property does. Easements, rights of way, mineral reservations, utility crossings, and boundary discrepancies are the norm, not the exception. The land sales agreement should include a title contingency that gives the buyer a defined period — typically 10 to 30 days — to object to any encumbrances discovered in the title commitment. The buyer should also have the right to request a new survey if the existing one is older than a few years or if the parcel's boundaries are unclear. Here is a detail most guides miss: the difference between an ALTA survey and a boundary survey matters more than people realize. A boundary survey shows the property lines. An ALTA/NSPS survey shows boundary lines, easements, encroachments, zoning restrictions, flood zone designations, and access points. If you are buying land for development, you need the ALTA. If you are buying it for recreational use, a boundary survey may suffice. I once had a buyer who accepted a boundary survey on a 20-acre parcel intending to build a cabin. Three weeks after closing, the county sent a stop-work order because a drainage easement running through the proposed building site was not shown on the boundary survey. It was visible on an ALTA. The buyer had to relocate the foundation plan, delay construction by six weeks, and pay for a revised survey. The contract had specified only a boundary survey, and the seller had no obligation to provide anything more. That is a costly oversight to make.
Step Four: Specify Closing Conditions and Timelines
The agreement should state when closing will occur, what conditions must be satisfied before closing, and what happens if those conditions are not met. Common conditions include: title clearance, survey completion, environmental assessments, zoning verification, utility availability confirmation, and satisfaction of any financing contingencies. Include a force majeure clause if the transaction spans several months. I learned this the hard way during the early pandemic period when county recorder offices closed for three weeks and title companies operated on reduced staff. A standard 30-day closing timeline became impossible not because of anything either party did wrong, but because the infrastructure supporting the transaction was temporarily unavailable. Without a force majeure provision, the buyer could have been in default for failing to close on time through no fault of their own. I now include a brief force majeure clause in every agreement that extends deadlines proportionally when government offices or recording facilities are unexpectedly closed.
Step Five: Include Remedies and Default Provisions
What happens if the buyer walks away? What happens if the seller refuses to close? The agreement needs to specify the remedies available to each party. In many states, the seller's remedy for buyer default is retaining the earnest money as liquidated damages. In others, the seller can pursue specific performance or actual damages. The default should be stated clearly, with a defined notice period and cure window before remedies kick in. I prefer a staggered approach: a 10-day notice to cure for minor issues, a 30-day notice for material breaches. This gives both parties a reasonable window to resolve problems without immediately triggering termination. I have seen agreements where a single missed payment deadline, noticed after only three days, allowed the seller to cancel and keep the deposit. That is aggressive and often challenged in court, but it creates uncertainty for both parties. A measured approach reduces conflict and keeps the transaction moving.

When a Land Sales Agreement Is the Wrong Tool
Not every land transaction needs a land sales agreement. Here are the situations where you should consider alternatives: Quick closings under 30 days: A standard purchase agreement with a simultaneous closing is simpler and carries less risk than an executory contract. The longer the gap between signing and closing, the more exposure both parties have to title issues, market changes, and regulatory shifts. Transactions involving complex environmental liabilities: If the property has known contamination, wetland designations, or pending remediation orders, a land sales agreement may not provide enough structure. You need a more detailed environmental addendum or a separate remediation agreement that addresses liability allocation, cost sharing, and regulatory compliance timelines.
Heirship or probate transfers: When the seller inherited the property and the title has not been cleared through probate, a land sales agreement locks you into a transaction that may never close if the court does not approve the sale. In these cases, waiting for the probate process to complete before entering into any purchase agreement is the safer path. Land contracts with seller financing in states that regulate them heavily: Some states treat seller-financed land contracts as consumer credit transactions subject to lending regulations, disclosure requirements, and usury limits. If you are in one of these states, a standard land sales agreement may not be sufficient. You may need a promissory note, a deed of trust, and compliance with state-specific disclosures. I have seen deals in California and Texas invalidated because the seller failed to include required truth-in-lending disclosures in a seller-financed land contract.
A Real Problem I Solved: The Undivided Interest Trap
Several years ago, a buyer came to me after their land sales agreement fell apart. They had purchased what they believed was a 5-acre parcel with road frontage. The contract described the property as a specific fraction of a larger tract, but the legal description was ambiguous about whether they were receiving a severed 5-acre portion or an undivided 5/40th interest in the entire 40-acre parcel. The seller had sold the same fractional interest to two different buyers in separate transactions. Neither buyer had a clear, exclusive parcel. Both had undivided interests in the same land. The fix was not simple. We had to negotiate with the other buyer's attorney, who was not cooperative. In the end, we structured a partition agreement that physically divided the 40-acre tract into four 10-acre parcels, with each owner receiving a clearly defined boundary. The process took four months and cost approximately $18,000 in surveying, legal, and mediation fees. The original land sales agreement was voided and replaced with a new partition and exchange agreement. The workaround I now use to prevent this: every land sales agreement I draft requires the seller to warrant that the property being conveyed is a legally severable, separately describable parcel with exclusive possession rights. The agreement also includes a contingency allowing the buyer to terminate and receive a full refund of earnest money if a title search reveals any co-ownership, tenancy in common, or undivided interest that was not fully disclosed in the contract. This caught the issue early in subsequent deals and prevented a repeat of that situation.
Common Pitfalls That Destroy Land Deals
Assuming the listing description is accurate: MLS listings and online descriptions are marketing documents, not legal instruments. I have seen buyers rely on a listing that claimed "2 acres of buildable land" only to discover the actual parcel was 1.3 acres with a steep slope that made construction impossible under local zoning. The contract should always reference the legal description and survey, not the listing. Skipping the zoning verification: Land use restrictions can change. A parcel zoned agricultural today may be rezoned for commercial use tomorrow, or vice versa. The buyer should verify the current zoning with the local planning department and include a zoning contingency in the agreement. I once had a client who planned to subdivide a 10-acre parcel into two 5-acre residential lots. The zoning allowed it at the time of contract. Six weeks later, the county updated the comprehensive plan and the zoning was reclassified to exclude residential use on parcels under 8 acres. The contract's zoning contingency allowed the buyer to exit without penalty. Ignoring access and ingress/egress rights: A landlocked parcel is a liability, not an asset. Even if the contract mentions a road, you need to verify that the road provides legal, recorded access to a public way. Private roads with shared maintenance obligations can become sources of conflict. I recommend requiring the seller to provide copies of all easement agreements and a current title report showing all recorded access rights before the buyer deposits earnest money.
Overlooking utility availability: If the buyer needs a well, septic system, electric service, or internet connectivity, the agreement should address whether these are available at the parcel and who is responsible for extending them. I have seen deals fall apart because the buyer assumed a well was possible based on a neighbor's successful drill, only to discover the aquifer level had dropped significantly and the parcel's well permit application was denied.
The Bottom Line
A land sales agreement is a risk management tool, not a formality. The quality of the agreement determines whether the transaction proceeds smoothly or ends in litigation. I treat every land sales agreement as a site-specific document that requires careful attention to the legal description, title status, zoning, access, utilities, and local recording requirements. Generic templates save time in the short term but create problems that cost far more to fix later. The extra hour spent tailoring the agreement to the specific property and jurisdiction is almost always worth it.