Understanding The Victoria's Secret Credit Card Without The Marketing Hype
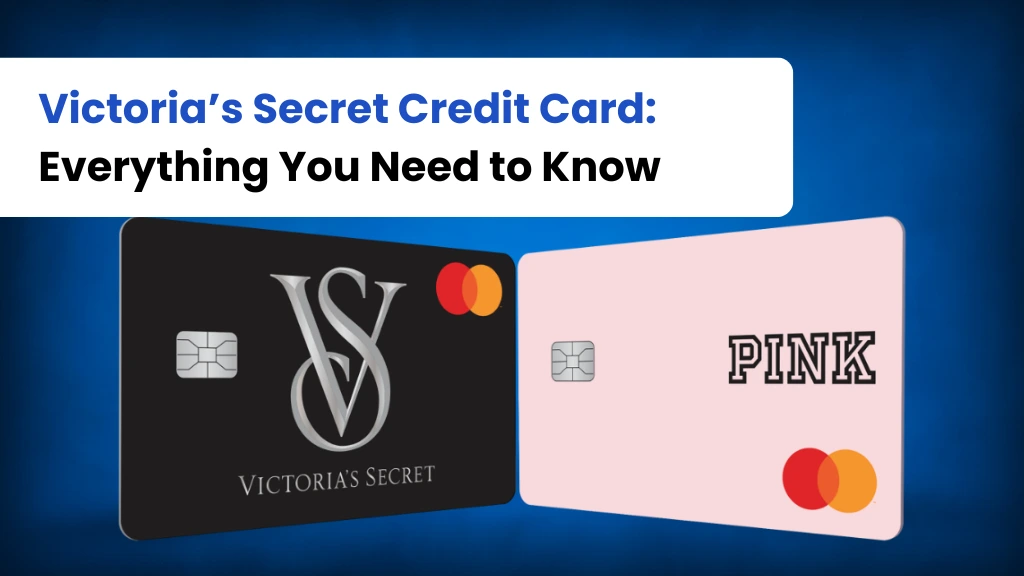
The Victoria's Secret credit card works like most store cards. It is issued by Comenity Bank and it gives you rewards points on purchases at Victoria's Secret, La Senza, and PINK. The rewards are called VIP Points. You earn one point per dollar on everyday purchases. When you hit certain spending thresholds, the card unlocks access to exclusive discounts that are not available to non-cardholders. Here is the thing people miss when they read the glossy brochures. The biggest value is not in the points you earn on purchases. It is in the milestone rewards and those special discount events that only cardmembers can use. During the year, Victoria's Secret runs 30-40% off sales. With the card, you sometimes get early access to those sales or even an extra 20-25% off on top of the already discounted merchandise. That stacked discount is where the real savings live.
Unlock The Secret To Saving A Comprehensive Guide To The Victorias Secret Credit Card
I learned this the hard way. Back in 2022, I bought a bra that was marked down 60% during a semi-annual sale. I also had the card and the checkout system did not automatically apply the cardmember discount. I ended up leaving $18 on the table because I did not know to ask the associate to run the transaction again with the card linked. Now I always make sure the cashier verifies the VIP pricing before the register closes the sale. It takes three seconds and it matters more than you think. The card has three tiers. The Victoria's Secret Credit Card is the entry level. There is also a Visa card and the older store card with slightly different perks. The entry-level store card gives you 1% back in points on every purchase. The Visa version gives you 1% cash back but it works everywhere, not just at Victoria's Secret. If you shop at their stores regularly, the store card is worth more. If you occasionally browse or want the flexibility to use it outside the brand, go with the Visa.
How To Maximize The Savings Without Overspending
The most important rule is to never buy something just to hit a spending threshold for a milestone reward. I have seen people do this at least twice a year during promotion periods. They hit $250 or $500 in spending and unlock a 20% off coupon or a $20 reward card. The math almost never works out in your favor if the purchases were unplanned. Instead, plan your regular purchases around the milestone windows. If you already needed to replace some lingerie or buy workout gear from PINK, time it so that your total reaches the threshold during an active promotion period. The rewards are usually valid for 30 days after you unlock them, so you do not need to spend everything in one sitting. Another thing most people overlook. The points do not expire as long as you keep the account active and make at least one purchase every 12 months. If you close the card and reopen it later, your points balance resets to zero. I lost about 4,200 points this way in 2019 because I had forgotten about the card sitting dormant in my drawer. It was a painful reminder that store cards are not set-and-forget accounts.
Get the Full Details
The Downsides That Nobody Talks About
The annual fee is zero, which is good. But the APR is steep. Current rates sit around 29.99% variable. If you carry a balance month to month, the interest will completely erase any rewards value. This is not unique to this card but it is easy to dismiss when the marketing focuses on free points. There is also the approval hurdle. Comenity Bank tends to be stricter than major issuers on credit score requirements. You usually need a FICO score of 640 or higher for the standard card. If your score is below that, the chances of approval drop significantly. I helped a friend apply and she got denied despite having a 620 score and a history of on-time payments. The bank seemed to weigh recent credit inquiries heavily. Another edge case. Some users report that the discount stacking does not work correctly during online checkout. I ran into this last fall when I tried to use a 30% off code alongside the cardmember 20% discount on a pair of bras. The website applied only the higher discount and ignored the second one. I had to call customer service and they manually adjusted the order after about 20 minutes on hold. It worked but it was frustrating. I now test small purchases first when trying to stack discounts online.
Practical Steps To Get Started
Apply through the official Victoria's Secret website. The application takes about five minutes and you get a decision instantly in most cases. If approved, you receive a digital card in your email within 24 hours. The physical card arrives within 7 to 10 business days. After you activate the card, enroll in the VIP program through your online account. This is where you track your spending milestones and claim your rewards. The portal is not the most intuitive interface but it gets the job done. Make sure to save the rewards codes to a notebook or phone note so you do not miss the expiration dates. If you already shop there frequently, the card pays for itself within the first purchase cycle. I calculate roughly $40 to $60 in savings during a typical year for an average shopper who uses the card for existing needs rather than impulsive buys. That is a rough estimate based on my own receipts and the promotions I have tracked over the past three years.
For deeper information about the current terms and conditions, you can visit the Comenity Bank website or the Victoria's Secret rewards page. The details change periodically and I do not track every update in real time. What I can tell you with confidence is that the card is worthwhile if you are a regular shopper and disciplined about paying the balance in full each month. If you tend to carry debt or shop once a year, skip it and save yourself the hard inquiry.