The Math Nobody Warns You About
Most people stare at their revenue number and assume growth is automatic. It isn't. Revenue means nothing without subtracting every cost that actually came out of your bank account, and the math gets messy fast. I once ran a quarterly review for a client who had $340,000 in revenue and a gross margin that looked healthy at 58 percent. When I dug into their expense categorization, I found they had classed $22,000 worth of subcontractor payments under "professional services" instead of COGS, which artificially inflated their gross profit. More importantly, their operating expenses included two SaaS subscriptions they'd been paying for but barely used, and a third annual insurance renewal that should have been amortized across twelve months instead of hitting one quarter. The fix was straightforward once I saw the problem: recategorize the subcontractor costs into COGS, cancel the unused tools, and move the insurance payment into a prepaid expense schedule. That changed their net profit from a thin $18,000 to $41,000 for the same quarter. Same revenue, same business, just accurate books. Start with your total revenue. This is the gross amount earned from all sales before any deductions. If you run multiple product lines or service categories, pull the combined figure from your general ledger or accounting software. Do not pull it from your bank statement unless you are prepared to correct for deposits that aren't actually revenue, like owner contributions or loan proceeds. Revenue should match what your invoicing system says was billed and collected during the period. Next, subtract your cost of goods sold. COGS includes everything directly tied to producing what you sell. For a product business, that is raw materials, direct labor, and freight-in. For a service business, it is the wages of people delivering the service and any materials those people consume on the job. A common mistake here is forgetting to include your own ownership time if you take draws instead of a formal salary. If you pay yourself through payroll, include those wages. If you take distributions, you need to account for that gap somewhere in your calculation or your net profit will look better than it actually is.
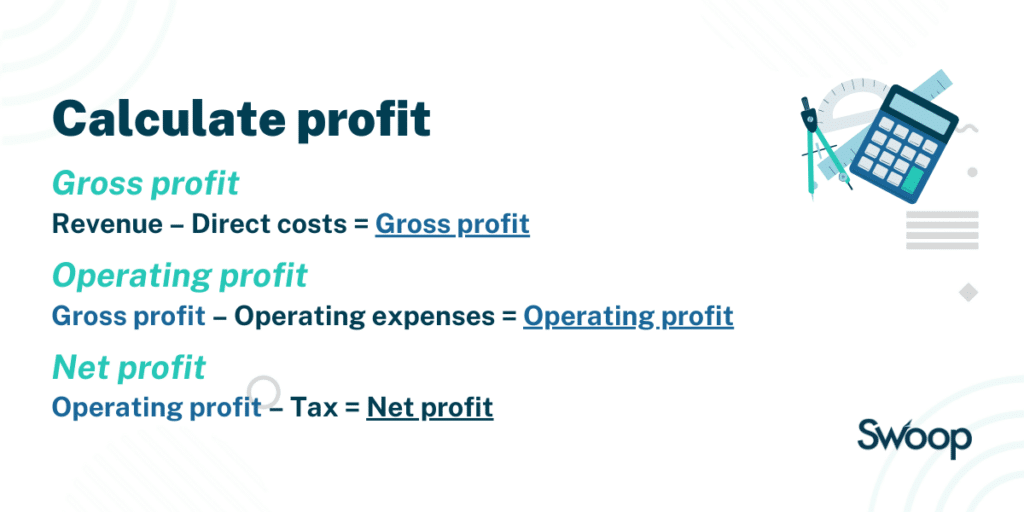
That gives you gross profit. Now subtract operating expenses. This is where most people lose track. Operating expenses cover rent, utilities, marketing, software, office supplies, insurance, professional fees, and depreciation. Depreciation is the silent one. A piece of equipment you bought for $12,000 last year does not disappear from your P&L in one hit if you depreciate it over five years. You need to include the monthly depreciation expense, not just the cash outflow, because depreciation is a real cost even though no money left your account this month. I keep a separate depreciation schedule in a spreadsheet because accounting software sometimes rolls it into a summary line and it is easy to miss if you do not know where to look. Operating income comes after those subtractions. Then you factor in non-operating items. Interest expense on loans, gains or losses from asset sales, foreign exchange adjustments if you deal internationally. These are not part of your core business operations but they still hit your bottom line. Add or subtract them to get your pre-tax income. Then apply your effective tax rate. The effective rate is usually different from your statutory corporate rate because of deductions, credits, and the way your jurisdiction structures things. If you do not have a precise effective rate, use the weighted average from your last three years of tax returns. That is more accurate than guessing based on current law. The result is your net profit. Here is the formula condensed into something you can actually use without drowning in accounting jargon. Net profit equals total revenue minus COGS minus operating expenses minus interest minus taxes plus or minus any non-operating items. That is it. The trick is getting every line item right so the number means something when you look at it six months later.
One counter-intuitive thing about net profit that beginners miss is that two businesses with identical revenue and identical net profit margins can have completely different cash positions. This happens because net profit includes non-cash items and accruals. If you book a large sale in December but the customer pays in February, your December net profit reflects that revenue while your cash does not. If you prepay rent for the next six months, your January P&L shows less expense even though you spent six months worth of cash. Understanding this distinction matters more than the calculation itself. Net profit tells you profitability. Cash flow tells you whether you can stay open. Another nuance people overlook is how owner compensation affects the number. If you pay yourself a salary, it shows up as an operating expense and reduces net profit. If you take owner draws instead, net profit looks higher, but that is misleading because you are still paying yourself, just through a different mechanism. When comparing your net profit to industry benchmarks or trying to value your business, you need to normalize for owner compensation. Add back your draw and subtract a market-rate salary for the work you do. The adjusted number is what you should actually compare against. There are also scenarios where net profit is almost useless on its own. If you are in a capital-intensive business with heavy depreciation, net profit will look artificially depressed in the early years. If you are in a service business with minimal fixed costs, net profit might look healthy while you struggle to collect receivables. A more useful lens in those cases is EBITDA, which adds depreciation and amortization back into the picture. It is not a perfect metric either, but it smooths out the noise from non-cash charges and gives you a cleaner view of operational performance. I usually calculate both and compare them side by side so I can see what the depreciation schedule is doing to my bottom line.
Get the Full Details

When I work with clients on this, I recommend building a simple template that pulls your revenue and expense data in one place. Use categories that match your chart of accounts exactly. Run it monthly, not quarterly. Monthly runs surface problems earlier. A quarterly review means three months of drift that you have to backtrack and fix. The time investment is roughly fifteen to twenty minutes per month if your books are already clean. If they are messy, factor in another hour for reconciliation. It pays for itself within one cycle. Accuracy matters more than speed here. I have seen entrepreneurs double down on bad numbers because they were attached to the story those numbers told. Your net profit should not be a number you want it to be. It should be a number you are honest about. That honesty is what lets you make decisions. Revenue doubling strategies fall apart the moment you realize your net profit margin is compressing because your COGS is rising faster than your prices. Knowing that early changes everything. If you want a practical way to get started right now, download the template I use for this calculation. It has the revenue line, the COGS section with common categories pre-filled, the operating expense section with depreciation built in, and a non-operating items tab. It also includes a normalized net profit section that adjusts for owner compensation automatically. Download the Net Profit Calculator Template.
One edge case I want to mention because it comes up more often than you would think. If you operate across multiple legal entities, do not simply add the net profit from each entity together and call it a day. Intercompany transactions, transfer pricing, and shared expenses distort the picture. I had a client who combined three LLCs and reported a combined net profit of $120,000. When I eliminated the intercompany service fees between the entities and adjusted for the overhead allocation, the true consolidated net profit dropped to $87,000. The template handles this by flagging intercompany entries so you can strip them out before finalizing. It takes an extra ten minutes and saves you from making decisions based on inflated numbers. Finally, keep in mind that net profit is backward-looking by definition. It tells you what happened. It does not tell you what will happen next quarter. Pair it with a rolling forecast that adjusts for known variables like contract renewals, seasonal hiring, or anticipated price increases. That gives you a number you can actually act on instead of a historical artifact you file away and forget.